Tag: Samsung Page 4 of 7

Good bye Symbian?

First, Samsung announced it would drop Symbian from its smartphones in 2010 in favour of its new, home-brew bada OS. Then Nokia said it would drop Symbian (albeit not immediately) from its flagship N-series devices replacing it with Maemo, the OS that premiered on a Nokia device on the recently released geek dream, the N900.

It is said that there are

no current plans for Maemo devices in the […] X-Series range or the popular [?] E-Series enterprise range

but the word “current” suggests that this might well change soon, too.

This would leave Symbian without its two largest OEM supporters. Will there still be a future for it?
Symbian of course boasts a still very impressive number of legacy devices, and it will therefore be here for a while. However, what does the long-term outlook look like? Android, LiMo, etc all “boast” a nimbler, more agile set-up, allowing for faster development and, arguably, better user experience. This is not necessarily Symbian’s fault (it carries with it its legacy around) but it makes it that much harder for it to reinvent itself.

I am not sure if there is place (and – timewise – the runway) to reinvent itself without the backing of big OEMs. I would be surprised if carriers would use it; they – even more than OEM – require adaptability and customization, which the newer platforms seem better suited to serve. Vodafone’s choice of LiMo for their first two Vodafone 360 devices is testament to that.

The ever-bright Tomi Ahonen suggested a comparison with DOS/Windows and MacOS: he compares Symbian to DOS, Maemo to Windows and iPhone to MacOS: MacOS led in UI and leads to this day. DOS outsold MacOS in spite of its dramatic inferiority because of the legacy instal base. Windows then overlaid DOS and rolled out on all the legacy devices with MacOS, as a result, always playing second fiddle despite its superiority.

The market place in mobile looks different though: DOS was nigh dominant (outside the mainframe and large enterprise side of things) whereas Symbian “only” covers about 5% of the current market. It is big but probably not big enough to bridge the DOS/Windows migration gap. With Android, Blackberry, Windows Mobile, LiMo, JavaFX (if that ever takes of properly), etc all on the map, too, the situation is very different to the DOS/Windows/MacOS world. Would Nokia be quicker in execution, I might still look at it differently but, unfortunately, it doesn’t seem to be that way.

So is it good bye, Symbian, then?
Android 2.0 a Motorola Exclusive???

There have been reports (referred to by this here) pondering if Motorola grabbed an “exclusive” deal with the Google-led Open Handset Alliance for Android 2.0 on its Droid (or, in Europe et al, Milestone) handset. There does not appear to being any formal confirmation of this but it was mentioned that, anecdotally, other vendors (and fellow members of the Open Handset Alliance) like HTC, LG, Kyocera and Samsung were still deploying version 1.5.

They quoted industry analyst Ross Rubin as to why Android 2.0 debuted on a Motorola device:

[…] There could be several reasons. Verizon’s subscriber strength and more direct competition with AT&T and the iPhone may have led it to push for Android 2.0 to be more competitive. Or it could be simple product development timetables. Moving forward, HTC will want to put its Sense user experience on top of Android 2.0, which requires development time. Google wants a healthy Android ecosystem and a competitive Motorola contributes to that.

The article went on to refer to the respective releases for 1.0 and 1.5 (both to HTC). However, one might argue that, for the first two releases, there was not much harm done in working more closely with HTC as they were the front-runners on deploying an Android phone, so that the concerted marketing buzz etc might have been justified. However, now that there is a large number of vendors deploying, one might query the compliance of the term “open source” with such exclusivity arrangements.

It also highlights the dominance Google has in the Open Handset Alliance which might, longer-term, lead to assertions that Google is in fact using the open source road as a cover to push what is effectively an OS largely driven by them. I am not implying that it is and a healthy ecosystem with multiple strong is important in particular for the launch of a new OS in a space so full of powerful multi-nationals but there is a fine line to walk in order to get it right.
Conference: Symbian Exchange & Exhibition

The conference formerly known as Symbian Smartphone Show (or something along those lines) is back this year as the Symbian Exchange & Exhibition (or SEE09). It kicks off this Tuesday in London’s Earl’s Court Exhibition Grounds and boasts a rather impressive line-up:
Jimmy Wales (Wikipedia Founder and one of TIME’s 100 most influential people) will be the headliner. There will be keynotes and panels with senior executives from the world’s leading vendors and carriers, including Nokia, IBM, Sony Ericsson, NTT DoCoMo, Vodafone, Qualcomm, Texas Instruments, Samsung, as well as application pros from the BBC, Guardian, GetJar, Navteq and many, many more.

SEE09 is the world’s largest event for the Symbian platform, which is – even if recently often maligned – still the largest smartphone platform anywhere!

Attendance is FREE. You can register here (it’s not too late…).

I’ll be there, too, so please drop me a line if you want to meet for a coffee (or beer at the party – attendance of which is also FREE). See you in London this week then!

Vodafone 360: the Good, the Bad and the Ugly

After much huffing and puffing, Vodafone unveiled yesterday what everyone had been waiting for for months and months: its new Vodafone 360 concept, which will replace Vodafone Live! It launches on – drumroll – LiMo-OS Linux phones from Samsung with touchscreen and GPS and, for the H1, AMOLED display (yum!), WiFi, HSDPA, etc, etc, etc. and also supports a fairly big range of Nokia (not on the N97 though!) and Sony Ericsson devices (although, judging by the screenshots, it doesn’t look as sexy on those).
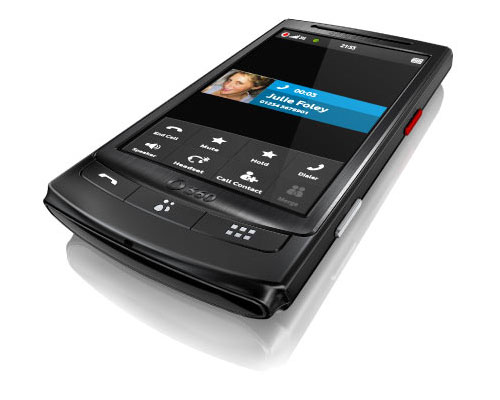
The 360 thing is, according to the press release

a brand new set of internet services for the mobile and PC which gathers all of a customer’s friends, communities, entertainment and personal favourites (like music, games, photos and video) in one place.

It has an address book with nodes into Facebook, IM (Windows and Google) and will “soon” also cover Twitter, Hyves and StudiVZ (the German Facebook clone). Two tailor-made (!) handsets that use a proprietary (!) interface based on LiMo’s release 2 mobile Linux OS. Users can create groups across different networks (which is very neat!), an app store with 1,000 apps at launch (no word so far what this comprises) and syncing with your computer.
So is this the big thing then? Here’s the good, the bad and the ugly:

The Good

  • The service reaches out. It acknowledges (this is a big step for most carriers!) that users have a life outside their carrier. Facebook, Live Messenger and Google Talk are a bit thin, I’d say, but let’s cut them some slack; the others will follow.
  • It has a couple of neat twists built-in: I mentioned a few above but there is also a feature that uses some spooky thing called the “Vodafone’s proximity algorythm” and which basically automatically favourites your most-loved people: the most frequently contacted people (like your mom?) come closer to the front.
  • At least on the custom-built devices, it looks much better than previous attempts by carriers to make something look and feel a little more user-friendly.
  • I hear that the whole widget-thing should be really neat. Now, I haven’t seen any of it as yet but the concept sounds good.
  • It works across different operating systems (at least LiMo and Symbian).

As a funny side remark, the PR blurb points out that

The beauty of Vodafone 360 is that all the services work together and they are easy to use.

So they weren’t before, huh? 😉 — sorry, couldn’t resist…

The Bad

Some commentators mentioned that the cloud-hosted address book and generally aggregation of contacts, networks etc through a provider rather than through the handset would tie people to the provider more closely (which might not actually be anything Vodafone would object to). I am not sure how tough it would really be (as you have your computer back-up), so easy on that.

It is still very much a closed-circuit affair: It is Vodafone and no one else. It is proprietary, tailor-made and not open. This is not good (and, yes, I know that the oft-cited iPhone is proprietary and tailor-made, too). Alas, its applications are not – unless your name is Spotify; then it takes a little longer… 😉

The Ugly

The underlying proprietary thinking is nothing I can see working longer term. In a world that is (Vodafone press speak)

a substantiator of Vodafone’s new brand expression – ‘power to you’ – which is focused on putting the customer in control and enabling simple and easy to manage communications, both mobile and fixed

this is also a little bit of a contradiction.

But I will say that it seems to be the nicest operator-built environment I have seen so far. And for this to come from the world’s largest operator is no mean feat and might actually yield some results. Go on, guys, tweak it, improve it, show us!

US Mobile Advertising Snapshot August 2009

I had covered the monthly Scorecard for Mobile Advertising Reach and Targeting (what a mouthful) from Millenial Media before (see here for the May figures), so here’s an update on this (and note that these are all US-only figures). The firm covers just under 50m users, which seemingly represents 79% of the mobile web (but only 11 of the top 25 sites as per Nielsen). However, it should provide for a very decent overview of the state of advertising on the mobile web. So here it goes:

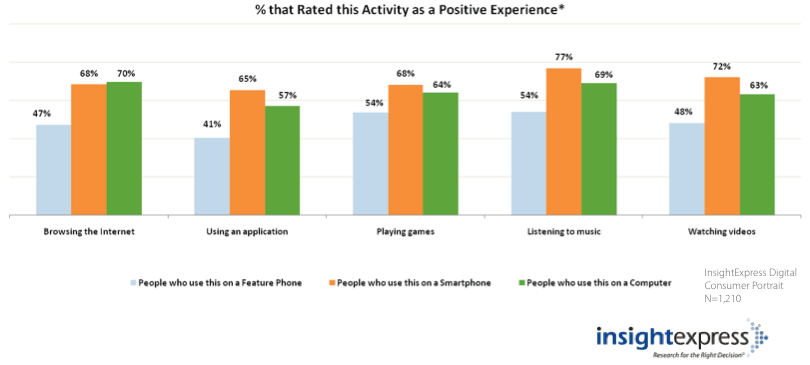
The first really noteworthy piece has not actually anything to do with advertising but with user satisfaction: would you actually have thought that users enjoy most things more when done on their smartphone than on their computer, including playing games and watching video? The computer only leads (and by a meager 2% higher rates) for web browsing (70% vs 68% on smartphones). Wow! Here’s the graph:

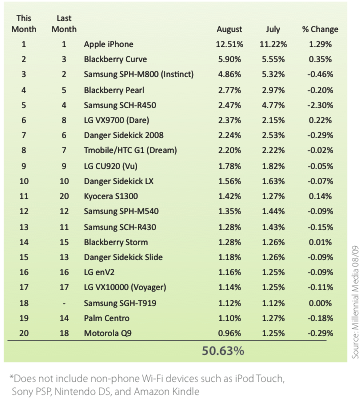
This is very encouraging and probably also owed to the market leader when it comes to ad impressions received on a mobile device, which is – moan – the iPhone of course. The last snapshot I covered had the Samsung Instinct in front but this has slipped back to a still respectable #3 now. Blackberry’s Curve takes 2nd place. Here’s the top 20 list:

Compared to their old format, Millenial Media is no longer spitting out a comprehensive chart showing the CPEU (cost per engaged user) per demographic/targeting method. They have adopted their proprietary “Mydas” tool, which appears to enable them to mix things together in an optimal way. It is understandable since this is their business but the look under the bonnet was great. Alas, no more. So here’s what we still learn:

  • iPhone and iPod Touch impressions are still growing with double-digit numbers (month on month they grew 68% in June, 29% in July and 15% in August).
  • Average monthly page views is 111 (up 5 views).
  • The top 20 phones (see above) make for 50.63% of all device traffic, which is drop by nearly 4% compared to the previous month.
  • A whopping 26.15% of all ad impressions were achieved on devices on a WiFi connection (bandwidth is king!).
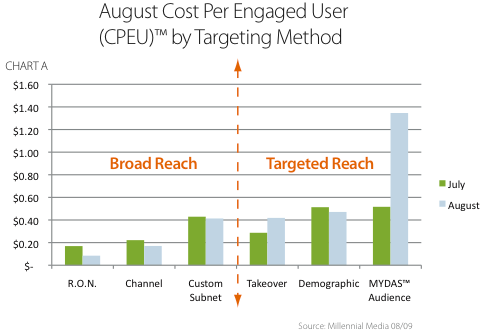
  • Cost per Engaged User for audience targeting increased very significantly from ¢52 to $1.35, which is owing to Millenial’s aforementioned Mydas thing (or so they say). Most CPEU rates decreased however. Here’s the chart:

So what does it teach us? Well, due to the new format unfortunately less than previously… but then: I’d love to have that Mydas touch… 😉

EA Mobile, Namco Bandai and the State of Carrier Decks

After many rumours and ominous statements that it was “reviewing its activities” Namco Bandai confirmed today that EA Mobile will thenceforth act as its distributor for mobile games outside the US and outside any app store.
After Taito and Eidos, EA Mobile just gobbled up another major distribution deal and the exodus from J2ME games distributed via carriers continues. It also means that EA’s dominance over the operator decks has just increased a little more yet again. It had estimated (back in June) that its 2009 mobile revenues would reach $185m (although this arguably includes Apple’s and other people’s app stores as well as embeds).

What is worrying is that this cements the oligopoly of games distribution in all major markets. EA Mobile, Gameloft occupy the top 2 slots very comfortably with Glu an equally comfortable but distant third. I-Play, Digital Chocolate, Real and Connect 2 Media are fighting for place and Xendex, Handy Games and a few others seek (and sometimes find) niches to prosper. THQ Wireless, Vivendi Games Mobile have departed. Player X found a new home under the mighty wings of Zed. And then? If the above companies all manage to maintain a healthy business, this might be enough; there are silverback gorillas in every market segment. If not though, this might become a doomed sub-sector; the limelight would then be on the (failed) ecosystem operators tried to build: overly fragmented with everyone of them wanting it just so and just their way rather than agreeing on a largely unified structure and processes pressed margins from a system that has been tough from the outset (handset fragmentation and international spread mean fairly high cost per capita anyway).
The accumulation of external properties arguably also mean that EA will need to run a business that is almost a combination of a publisher and an aggregator (with its very own challenges). The issue of shelf position (will they give Tetris and the Sims undue preference over Space Invaders, Pac-Man and Cooking Mama?), the commercials of their own deals (they anecdotally paid Hasbro a handsome sum), and the generally dominant position will all come into play and it is inconceivable (well, is it really?) that their partners will continue to play ball.

It might of course only be a brief interregnum on the way to an app store world. Smartphones are very much on the rise and, in that world, such stores seem to rule. Apple has taken the lead, Android followed suit and new stores are springing up almost by the day, which also includes operator-led ones: Orange already has one, Verizon Wireless has announced one (mobile web-based) and so has Vodafone (which might actually be bigger than Apples) as well as many others. The OEM all do the same (even though some carriers want to disallow them): Nokia Ovi, Blackberry App World, Sony Ericsson, LG, Samsung, you name them, they have it. The question of course is if that might mean the same thing all over again: will they again want it all just so? Will they again have it just their way so that a user would have the unique flavour of operator X on handset Y in this unique way, meaning that – again – thousands of SKUs would be required to service them? Groundhog Day? I hope not!
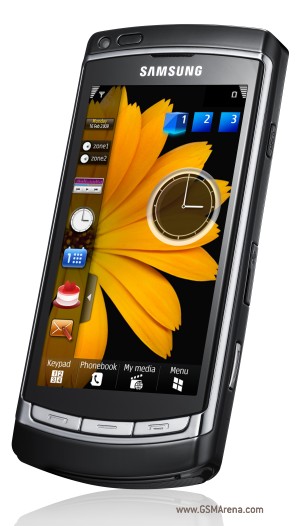
Image credit: http://www.antitrustreview.com/files/2007/07/files51lsaydhrsl.-ss500-.jpg

Handmark powers Samsung’s App Store

Samsung’s new app store (no one can do without one these days!) will be operated by Handmark and is set to go live on 14 September (2009, that is), I read. The respective site is (sort of) live and appears to accept registrations of prospective vendors. Go here if you feel like it… Launch will be in the UK, France and Italy first. No word when the others follow.

According to the press release, the content available will consist of Windows Mobile and Symbian s60 titles and will be available on the Omnia, I8910HD, Omnia II and Omnia Lite (so a true omni-store then). Billing is available via both credit cards and operator billing, which is – on the face of it – good (i.e. plain and simple credit card-billing doesn’t often work; Apple’s app store is an exception, I’d say, because input is via iTunes with which people are already familiar).

I’ll spare you the rest of the lyrical odes to the various partners… But let’s try and break this down: how big will this thing then be? Samsung is a force in mobile and its Omnia phones have had some very significant success indeed: in some markets (Germany was one), the Omnia outsold the iPhone by some margin (in December 2008, the Omnia had a 14.9% share of the German smartphone market compared to the iPhone 3G with 7.6%). It also launches in India now. I could not get my hands on solid sales numbers though (in the top 10 list by accessory sales for June, the Omnia came in on #10)… However, anecdotally, it is behind Nokia, RIM and Apple in global smartphone market share. So if we say that, on a global basis, there will be about the same number of devices around, that would make the phones a good success for Samsung.

However, when it comes to usage, I am not sure if the Omnia can compete with the iPhone. If we take ad impressions as an indicator (and it really is just that), we’ve seen that the iPhone’s 8% market share translates into 40% ad impressions. And because a lot of apps (and web “apps”) use ads, I think it is probably safe to assume that usage is higher. And this is arguably the crux of app successes: they need to be available but they also need to be discoverable and usable, and all of this with a lot of ease. Will they succeed? I hope so as it would do a ton of good to the industry would there be more than the niche player Apple. Their new TouchWiz SDK (see here) should help ease development for better UI, and the features of the store they announced look decent so far, so let’s keep our fingers crossed!

Image credit: GSM Arena

Page 4 of 7

Powered by WordPress & Theme by Anders Norén