Tag: Samsung Page 5 of 7

Mobile Innovation; in Response to Scoble

Egoblogger extraordinaire Robert Scoble has never been known to be shy, and so he declared with his usual great fanfare that Europe did not matter any more in terms of mobile innovation. Why did he say that, you ask? Well, Nokia apparently took him to visit their research lab in Cambridge (no, not in Espoo) as part of a (Nokia-)sponsored geek tour. And Scoble was not impressed. Because (1) everyone appears to have been texting when he was on the tube (how quaint), (2) the N97 isn’t cooler than the iPhone and (3) Symbian is much clunkier than the iPhone’s OS or Palm’s WebOS, Scoble deduces that Europe has had it.

He reduces this loss of leadership in mobile innovation to handsets or, more specifically, to the coolness factor of handsets (“London’s cool kids are [not] hot and bothered” about the N97). And, with that somewhat tight limitation, he might actually be right. Nokia has been losing ground on the coolness and usability front for quite a while. However, when it comes to technical ability, their devices are still quite hot. Scoble basically uses the iPhone plus the first Android-based (Taiwanese [sic!]) phones to declare that the king is dead.

Hardware is a Commodity
Now, let’s try to differentiate a little. Would you say the US have the lead in computer manufacturing? Well, probably not. IBM’s ThinkPads are Chinese, then there is Sony, Samsung, Toshiba, and there is HP and Dell. There is of course also Apple (“designed in California”). Does it matter at all where the hardware is from? No, not at all, and no one really cares anymore. And why not? Because hardware is basically a commodity, that is in a world where one does not actually see that much of the hardware because the interfaces are software-driven. And these are from Microsoft, etc.

In mobile, this has not been true in the past because their were such vast differences in the available hardware that the usability was severely impaired should you have been using, say, a low-end Motorola device as opposed to a high-end Nokia. This is where the myth of European mobile superiority comes from. And, with Apple, RIM and maybe Palm again, this is firmly in North American hands. There are of course Samsung and LG, the Korean powerhouses who drive their market share up and up. Android devices G1, G2 and Magic are from Taiwanese HTC. However, given how far mobile software and indeed services have come: does it really matter either way today? I say it does not.

Here’s the Innovation: Services

If one wants to see where mobile innovation is happening, one would need to go to South Korea, Japan, Finland (not the Nokia research labs but, say, the public transport system where you can pay via SMS for the past couple of years already), Austria (mass deployment of mobile RFID-payments), South Africa (mobile wallets and very evolved mobile marketing services), Malaysia, the Philippines and even Kenya (mobile money transfers). Certainly not the US though, I’m afraid. They are still the country where “can you hear me now?” campaigns rule.
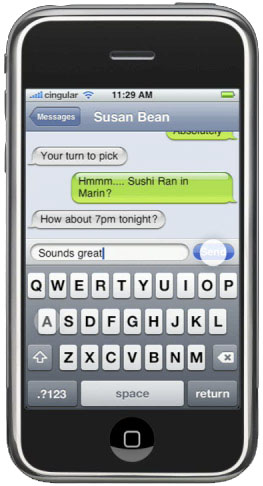
The iPhone has changed a lot of things of course. However, American Idol arguably did a lot more. It brought, shock, horror, texting to the Americans. SMS being, of course, a service. And why, Mr Scoble, should that be bad? Carriers (other than in the US) have made 25% of their revenues and 50% of their profits over the last 10 years with this unassuming little thing. That’s not too shabby, is it? The iPhone (and Palm’s WebOS) have introduced a new level of ease of use, and one that was long overdue. One that woke Nokia, which had comfortably dominated the space with less and less innovation on the software side, up (and Nokia might be a little slow to open their eyes properly). And one that will improve service levels all over the world.

Where the Big Market is

However, let us also not forget that the best-selling phone of all times is the Nokia 1100. No, it doesn’t do Java. It has a battery life of close to 20 years though and comes with a flashlight installed. Both very handy things to have in rural parts of developing or emerging countries. Nokia is having a fairly comfortable market share in these countries. I am not sure if that is a good thing to rest on though: as these markets, they demand more sophisticated devices. And because the computer penetration is much lower than in Europe, Japan, South Korea and North America, the significance of evolved mobile devices will be even more important. Nokia thought this would carry it through. However, we are seeing now that that might not be so: its smartphone market shares are rapidly decreasing.

Europe is not Europe
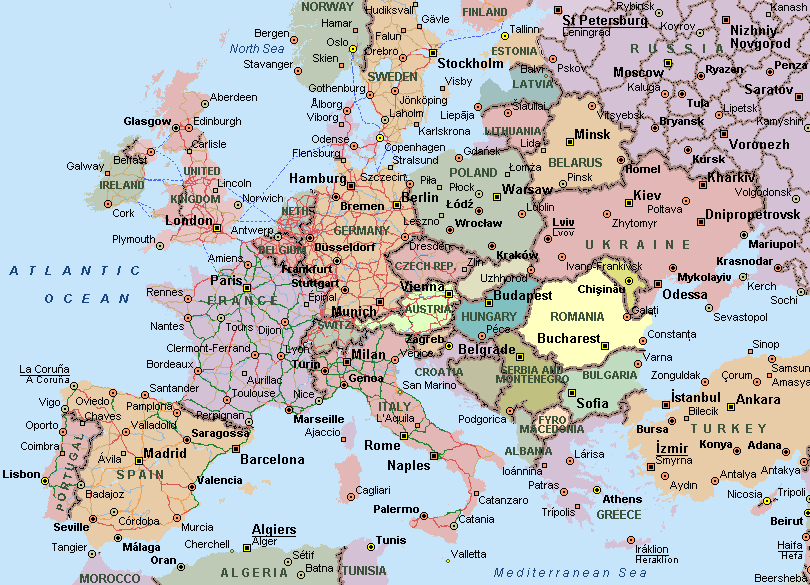
One last word on Europe: distinct to what Mr Scoble appears to have in mind, Europe is not a country, and this is not meant to be sarcastic. Europe is a pile of little countries and in each of them a couple of carriers rule like little kings. It makes for an extremely complex (and, consequently, low-margin) playground to deploy services. The US (as well as some of the huge Asian countries) have the incredible opportunity to deploy applications and services in one language through less than a handful of carriers to hundreds of millions. No such thing in Europe.

And this is why the US should lead in every aspect really: it is an evolved, competitive economy and it enjoys the tremendous upside of being (almost) completely aligned as to the framework: language, currency, carriers, billing systems, legal system, etc. This is the reason why the US has indeed leapfrogged Europe, the continent, when it comes to basic mobile applications: economies of scale are much easier to achieve there.

Software, Services, Interfaces

When one looks at Nokia in its current state as the sole indicator of where European mobile innovation is, one might be disappointed (as I pointed out numerous times, e.g. here). However, when one looks at how concert tickets are being sold via mobile, public transport, parking fees and vending machines all using mobile as a wallet solution, or indeed Obama making his latest speech available via SMS (there are more than 10x as many mobile phones in Africa than PCs according to Tomi Ahonen), then one can and should still be awed. And, no, in spite of its President the US is not (yet) close in this respect.
I hope, however, the US will catch up on this front sooner rather than later, too. Because of the size of the market and the aforementioned advantages, it would unleash incredible opportunities that would bring all of us fantastic new services and applications. And, Mr Scoble, it does not matter if these are 160 characters or polished web pages; it depends on what you want to do with it (as you, being one of the most prolific Twitterati, surely know).

I did not text anymore because I hated the UI and could not stand the clunky interfaces (in spite of T9; I’m too old, I guess). I started again with the iPhone. Why? Because – distinct what some people say – it’s a great interface: it displays the conversation, it looks neat and I have a full keyboard (the touch screen works much better than I feared; and I used a Blackberry for years and years). But that is not a question of the device or the technology, it is solely a question of the software. I would be much happier if I could also use my iPhone (or any other phone) to buy my newspaper (which I can with an RFID-equipped credit card in this country and which I could do in, say, Austria, a country with 2/3 the population of Illinois and a footprint smaller than Maine).

What Scoble misses (or omits in his post) is that the next leap in innovation will be a service-driven one (just as we saw on the Internet: first hardware, then basic apps, now sophisticated services).

Mobile has had the hardware phase, it is going through a “basic” app phase, and some European, African and Asian countries have entered the value-added services phase already, some years and years ago in fact! Compared to the US, they’re leading, by a lot! They’re perhaps just too small for the Robert Scoble to realize they’re there… But, as I said above: this is not about Europe leading the US (apart from the fact that it would appear to being Asia that is truly leading and has been for a while): it is about the evolution of an incredibly powerful communication device that is being unlocked for more and more applications and services; and this is independent from country and nationality!

Along those lines: why, Mr Scoble, should it be a bad thing that Europeans now “must” visit Cupertino and Mountain View. California is nice, isn’t it? Not a bad thing to go visit every now and then at all! We’re living in a large world, Mr Scoble, not only on a single continent, and mobile is a facilitator spurning new ecosystems, not only a device.

Image credit drawing: http://www.aartkom.cz
LG is Bullish: 9% growth in 2009

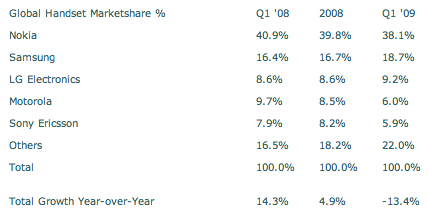
Not all is in recession it seems. The handset vendor world #3, LG predicts to ship 110m phones this year, which would represent a 9% increase in volumes on a year-on-year basis (see the market shares for 2008 and Q1/2009 below; courtesy of Strategy Analytics) in the face of what it believes will be an overall flat market this year.

So whilst everyone is shrinking, LG is growing. Everyone? Ah, now, Samsung is growing, too. The victims? Seemingly Motorola and Sony Ericsson with Nokia also suffering. No news then? Well, by 2012 LG wants to be #2 and ship around 200m devices (which would be 100% more than in 2008). So 9% growth wouldn’t get them there, would it?

Joking aside. Is this surprising? I think not. LG had had a couple of very “pretty” devices out. Starting with the LG Prada, they came out with the “Shine” and had a great success with the Viewty. They have been upping their game at a time where in particular Sony Ericsson and Motorola had been struggling to compose a coherent product strategy, and this will have enhanced the overall effect.

The Others: Where Android, Symbian & LiMo are

The title of this post is not meant in any way derogatory but with all the hype about the iPhone it is sometimes easy to forget that we are talking about a niche product that will probably remain a niche product (albeit a powerful and cool one!). In the rest of the world (feature phones aside), a few consortia are fighting for the open-source market, which is – let’s face it – a considerably larger piece than the small premium segment served by Apple.

So, where were we? There is the LiMo Foundation, which is onto establishing a mobile Linux standard. There is the Symbian Foundation and there is Android, a Linux-based OS from the Open Handset Alliance led by Google. One by one then:
LiMo Foundation

LiMo boasts a membership based comprised of the Who’s Who in mobile. Powerhouses from around the world like Vodafone, Orange,
Verizon Wireless, NTT DoCoMo, Telefonica, SFR, TIM and SK Telecom, Samsung, NEC, LG, Panasonic, Huawei, Motorola, and ZTE (and quite a few more) are all in there. LiMo has released an SDK a while ago. Now though, they decided that enough is enough and that the world should know that their OS was actually making headway. In 2009, there will be new handsets based on LiMo’s s
tandards released by Orange, Telefonica, Vodafone, NTT DoCoMo, SK Telecom and Verizon Wireless. Now, that’s a statement. Non-phone devices are in the works, they say…
There are already more than 20 LiMo phones out there (without very many people having realized it). They include such mundane devices like Motorola’s U9, ROKR EM30, ROKR Z6 and ROKR E8 as well as the RAZR2. Panasonic and NEC pboth produced a whole raft of devices for NTT DoCoMo. See here for a list of available phones.
Symbian

Symbian of course is coming from a differen
t mould: having been (co-)owned by Nokia for, like, ever, there are already over 200m devices running on its OS. After going open-source, they are working on consolidating the sister formats S60, UIQ and MOAP(S) now into one. Membership-wise, they’re not doing badly either: they target to having more than 100 members by year-end. Membership with them is only $1,500 p.a. It remains to be seen to what extent they will extend their handset footprint beyond Nokia though. Little has been heard so far…
Android

Both foundations felt compelled to state their cause, also in response to Eric Schmidt’s continued mantra that 2009 will be very, very strong for Android. The Open Handset Alliance had gone off to a well-publicized start with the T-Mobile G1. They recently announced that it had sold 1m devices (regarding which some people pointed out that Apple shipped as many iPhones on the first weekend), and are now gearing up more devices for launch (Vodafone got its hands on the HTC Magic). Samsung, LG, HTC and Sony Ericsson have all announced Android devices this year, and the first Samsung (I7500) has just been officially confirmed.
Multiple Membership
Wait a minute? Samsung? Weren’t they part of the LiMo foundation? Well, yes, and that is part of the problem: a lot of the big players have their fingers in all the pies (and why should they not?). This is favouring Apple since they are a single organization producing hardware and software. It could also be argued that it is favouring Android because Google throws so much marketing and PR behind it. However, maybe not. The big OEMs and the big carriers all work according to their own agenda. And this might very well be a very different one to Eric Schmidt’s: to an OEM, production cost, stability and versatility without impacting standardization are key. To a carrier, a lot will (also) ride on the ability to customize the handset so as to give it a distinct branded feel. Less PR from someone like Google makes it easier to them to focus on their own brand.
So: rock-solid, clean code, transparent and clear SDKs, no hidden hooks will mean that a lot of the feature phones that create the vast majority of handset sales (even if sales of the “classic” J2ME ones had been declining in 2008 when compared to smartphones) will quite possibly see a larger and larger move towards the open platforms. It makes it cheaper to produce and, with Apple having given the world the app store idea, content should flow in sooner or later. They “only” need to keep the standards, well, standard!
The iPhone is of course looming large, and it is the one device that has shown the old school of the telco world how 21-st-century marketing can impact market perception and sales. They have also all realized that this might actually be a very good thing, hence the eager discussions many are purported to be having on getting their hands on the next generation. However, last time I looked, the streets were not full of Porsche Boxsters either. Quite a few Hyundais, Fiats, Peugeots, BMWs, Volvos, well, you get it…

Smartphone Market Shares & Growth

World market leader Nokia had a bruising 2008, at least in the smartphone field. According to a study, the Finns’ market share in this segment dropped by 10% to a – well – still fairly respectable 40.8% in Q4/2008 (as compared to 50.9% a for the quarter in the previous year). Painful!

The big winners were RIM (growth of 84.9% year-on-year), Apple (111.6%) and Samsung (138%) although the latter grew from a fairly low share (1.8%). HTC was up 20% but its carrier-branded handsets (T-Mobile G1, etc) were not listed under its own tab but under “others”, so there might actually have been more (probable when considering that the company’s profits rose sharply in Q4/2008 on G1 sales).
Apple, interestingly, is said to have suffered a fall of sales during Q4/2008 with growth in that quarter driven by the Blackberry Storm, T-Mobile G1 and strong Samsung sales. On the OS side, Windows Mobile made headway, mainly via the successful HTC Touch line and the Samsung Omnia.
Overall smartphone sales in Q4/2008 were 38m and 140m for the whole year. This seems to tie in roughly with the numbers I discussed earlier this month.
The changes are of interest to the content industry, too. Smartphones make for a disproportionate amount of content consumption, and smartphones also lead the way for the new app stores that are breaking through everywhere after Apple showed its competitors just how much consumers are craving content. RIM is out of the blocks, as is Android. Nokia announced its Ovi Store and runs similar programmes with N-Gage, NCD and Comes with Music already and Windows Mobile has just announced the shop it will launch itself. Remains to be seen where Palm will go with its Pre and WebOS: it only had 0.9% of the market (some faithful Treo users!) and hence lots of catching up to do. And what about the newly coined JavaFX?
Here are the charts (courtesy of Gartner via Cellular News) for 1) Q4 2008 by vendor, 2) all of 2008 by vendor, 3) Q4/2008: by operating system and 4) all of 2008 by OS:

Worldwide: Smartphone Sales to End Users by Vendor

(Thousands of Units)

Company 4Q08 Sales Market Share4Q08 (%) 4Q07 Sales Market Share4Q07 (%) 4Q07-4Q08 Growth (%)
Nokia 15,561.7 40.8% 18,703.3 50.9% -16.8%
RIM 7,442.6 19.5% 4,024.7 10.9% 84.9%
Apple 4,079.4 10.7% 1,928.3 5.2% 111.6%
HTC 1,631.7 4.3% 1,361.1 3.7% 19.9%
Samsung 1,598.2 4.2% 671.5 1.8% 138.0%
Others 7,829.7 20.5% 10,077.3 27.4% -22.3%
Total 38,143.3 100% 36,766.1 100% 3.7%

Worldwide: Smartphone Sales to End Users by Vendor, 2008

Company 2008 Sales Market Share 2008 2007 Sales Market Share 2007 Growth
2007-2008
Nokia 60,920.5 43.7% 60,465.0 49.4% 0.8%
RIM 23,149.0 16.6% 11,767.7 9.6% 96.7%
Apple 11,417.5 8.2% 3,302.6 2.7% 245.7%
HTC 5,895.4 4.2% 3,718.5 3.0% 58.5%
Sharp 5,234.2 3.8% 6,885.3 5.6% -24.0%
Others 32,671.4 23.5% 36,176.6 29.6% -9.7%
Total 139,287.9 100% 122,315.6 100% 13.9%

Worldwide: Smartphone Sales to End Users by Operating System, 4Q08

Company 4Q08 Sales Market Share 4Q08 4Q07 Sales Market Share 4Q07 Growth
4Q07-4Q08
Symbian 17,949.1 47.1% 22,902.5 62.3% -21.6%
RIM 7,442.6 19.5% 4,024.7 10.9% 84.9%
Windows Mobile 4,713.9 12.4% 4,374.4 11.9% 7.8%
Mac OS X 4,079.4 10.7% 1,928.3 5.2% 111.6%
Linux 3,194.9 8.4% 2,675.9 7.3% 19.4%
Palm OS 326.5 0.9% 449.1 1.2% -27.3%
Other OSs 436.9 1.1% 411.3 1.1% 6.2%
Total 38,143.3 100% 36,766.1 100% 3.7%

Note: The “Other OSs” category includes sales of Sharp Sidekick devices based on the Danger platform.

Worldwide: Smartphone Sales to End Users by Operating System, 2008

Company 2008 Sales Market Share 2008 2007 Sales Market Share 2007 Growth
2007-2008
Symbian 72,933.5 52.4% 77,684.0 63.5% -6.1%
RIM 23,149.0 16.6% 11,767.7 9.6% 96.7%
Windows Mobile 16,498.1 11.8% 14,698.0 12.0% 12.2%
Mac OS X 11,417.5 8.2% 3,302.6 2.7% 245.7%
Linux 11,262.9 8.1% 11,756.7 9.6% -4.2%
Palm OS 2,507.2 1.8% 1,762.7 1.4% 42.2%
Other OSs 1,519.7 1.1% 1,344.0 1.1% 13.1%
Total 139,287.9 100% 122,315.6 100% 13.9%

Note: The “Other OSs” category includes sales of Sharp Sidekick devices based on the Danger platform.

Top 10 Mobile Phones in February 2009

Here’s the list of the 10 best-selling phones (judged by accessory sales) as compiled by Krusell, our Swedish holster-maker friends. I will not comment further on the sense or nonsense of this information but reference what I said previously about it.

So without any further ado, here’s the list (in brackets the ranking from the previous month):
1. (1) Samsung SGH-i900/i910 Omnia
2. (2) HTC Touch HD
3. (5) Nokia 6300
4. (3) Nokia E51
5. (4) Blackberry Storm
6. (8) Nokia E71
7. (6) Nokia 3109
8. (-) Nokia 5800
9. (7) Sony Ericsson X1 Xperia
10. (-) Nokia 3120
The most noteworthy new entry is the Nokia 5800 (XpressMusic), and the holster-maker’s CEO reckons it would shake up the top 3 next month. After Nokia’s most recent US launch disaster (see even more poignantly here) for the device, this will sadly but almost certainly not be driven by US sales though…
And as for the remainder: I remain skeptical about the measure (holsters). Other surveys (based on sales, like Sound-Scan used to do for CDs) show VERY different results.

Top 10 Phones in the US, December 2008: the Ascent of the Smartphone

There’s new data out on the bestselling handsets, and this time it is not being derived from accessory sales (which may have its flaws as I pointed out here) but from a survey amongst service reps and store managers across the 4 big US mobile networks (Verizon Wireless, AT&T, Sprint Nextel and T-Mobile; these comprise 85% of the total subscriber base). Now, this would arguably reduce the recorded sales for the iPhone since this is also being sold via Apple’s own retail stores as well as Walmart, Best Buy, etc. So again not an entirely accurate yardstick, huh?

It is noteworthy that only one handset is available on more than one carrier (and, yes, it ranks prominently amongst the top 1) and that Nokia, despite all waiting, has still not managed to break the top 10.
It is also noteworthy that most of the handsets would certainly be classified at smartphones (the Samsung Rant might be the exception). And this is certainly good news. The T-610 and RAZR may finally have left the building…
So here we go (number in brackets is the previous month’s rank):
1. (1) Blackberry Curve
2. (2) iPhone
3. (3) Blackberry Storm
4. (6) LG Voyager
5. (4) LG Dare
6. (5) Blackberry Bold
7. (-) Samsung Rant
8. (9) Samsung Behold
9. (10) Samsung Instinct
10. (8) LG Env2
Source: Rankings are by Avian Research LL.C. (via the above link)

Samsung Goes Green (or Blue?)

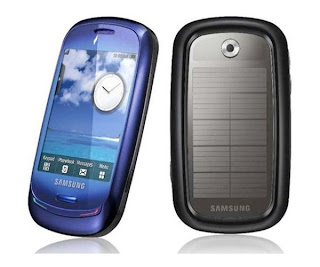
Ahead of the Mobile World Congress, Samsung announced a super-cool device. Cool because it has the word “blue” in its name (it’s name is “Blue Earth”)? Or because it’s all touchscreeny-feely? No! Because it’s very green: 

It’s solar-powered, it is made from recycled plastics (water bottles, just like the Motorola one I blogged about recently). Packaging? Recycled paper. And then it also has a couple of sweet little gadgets: you can for instance see how much CO2 you saved by using the in-built pedometer. Now, this (not the pedometer, the phone) is something rather cool! 

I will maintain – again – though that the question remains why they then do not do this kind of thing across all their products? In particular a company of Samsung’s size and might could surely make a difference if this would not only concern one handset but their entire product portfolio. Come on, guys!

Page 5 of 7

Powered by WordPress & Theme by Anders Norén