Tag: mobile applications Page 7 of 10

Vodafone 360: the Good, the Bad and the Ugly

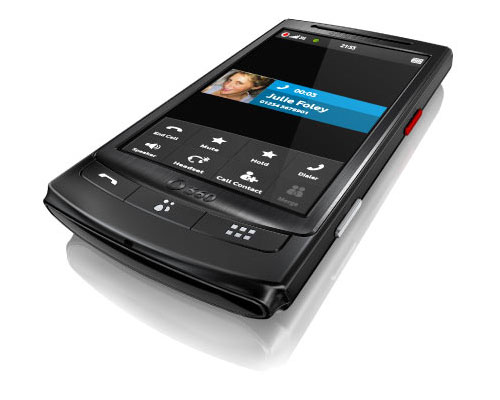
After much huffing and puffing, Vodafone unveiled yesterday what everyone had been waiting for for months and months: its new Vodafone 360 concept, which will replace Vodafone Live! It launches on – drumroll – LiMo-OS Linux phones from Samsung with touchscreen and GPS and, for the H1, AMOLED display (yum!), WiFi, HSDPA, etc, etc, etc. and also supports a fairly big range of Nokia (not on the N97 though!) and Sony Ericsson devices (although, judging by the screenshots, it doesn’t look as sexy on those).

The 360 thing is, according to the press release

a brand new set of internet services for the mobile and PC which gathers all of a customer’s friends, communities, entertainment and personal favourites (like music, games, photos and video) in one place.

It has an address book with nodes into Facebook, IM (Windows and Google) and will “soon” also cover Twitter, Hyves and StudiVZ (the German Facebook clone). Two tailor-made (!) handsets that use a proprietary (!) interface based on LiMo’s release 2 mobile Linux OS. Users can create groups across different networks (which is very neat!), an app store with 1,000 apps at launch (no word so far what this comprises) and syncing with your computer.

So is this the big thing then? Here’s the good, the bad and the ugly:

The Good

  • The service reaches out. It acknowledges (this is a big step for most carriers!) that users have a life outside their carrier. Facebook, Live Messenger and Google Talk are a bit thin, I’d say, but let’s cut them some slack; the others will follow.
  • It has a couple of neat twists built-in: I mentioned a few above but there is also a feature that uses some spooky thing called the “Vodafone’s proximity algorythm” and which basically automatically favourites your most-loved people: the most frequently contacted people (like your mom?) come closer to the front.
  • At least on the custom-built devices, it looks much better than previous attempts by carriers to make something look and feel a little more user-friendly.
  • I hear that the whole widget-thing should be really neat. Now, I haven’t seen any of it as yet but the concept sounds good.
  • It works across different operating systems (at least LiMo and Symbian).

As a funny side remark, the PR blurb points out that

The beauty of Vodafone 360 is that all the services work together and they are easy to use.

So they weren’t before, huh? 😉 — sorry, couldn’t resist…

The Bad

Some commentators mentioned that the cloud-hosted address book and generally aggregation of contacts, networks etc through a provider rather than through the handset would tie people to the provider more closely (which might not actually be anything Vodafone would object to). I am not sure how tough it would really be (as you have your computer back-up), so easy on that.

It is still very much a closed-circuit affair: It is Vodafone and no one else. It is proprietary, tailor-made and not open. This is not good (and, yes, I know that the oft-cited iPhone is proprietary and tailor-made, too). Alas, its applications are not – unless your name is Spotify; then it takes a little longer… 😉

The Ugly

The underlying proprietary thinking is nothing I can see working longer term. In a world that is (Vodafone press speak)

a substantiator of Vodafone’s new brand expression – ‘power to you’ – which is focused on putting the customer in control and enabling simple and easy to manage communications, both mobile and fixed

this is also a little bit of a contradiction.

But I will say that it seems to be the nicest operator-built environment I have seen so far. And for this to come from the world’s largest operator is no mean feat and might actually yield some results. Go on, guys, tweak it, improve it, show us!

App Bonanza or Analyst Bonanza?

In the last two days, two forecasts informed us about the value of the mobile app market in – convenient as ever – the distant future that is 2013. US analyst firm Yankee Group predicts the US app mobile market to be worth $4.2bn by then. Today, British analyst Wireless Expertise (run by former Netsize exec Anuj Kanna) topped this easily by predicting the (global) app market size to be $16.6bn by that time (free copy of the report here).

I can hear your moans…

However, let’s have a look at the numbers then, shall we? At the end of 2008, there were 4.1bn mobile phones in the market. Because apps tend to thrive most on smartphones (and the analysts seem to thrive on them, too), let’s have a look at that sub-sector. I would estimate the smartphone share to being somewhat under 10% (Symbian claims c. 250m devices in market, Apple has some 30-odd million, so RIM, Windows Mobile, Android, Palm, etc should probably be OK with the balance of some 100m). In Europe and the US, the share is much larger but in the big volume markets China and India it is bound to be much smaller, at least for the time being. Global smartphone shipments in 2008 were around 140m.

If we estimate a 20% growth year-on-year for smartphones (vs. 5% for the overall phone market, which seems to be loosely in line with the general dynamic), then we would end up with something like 900m smartphones by 2013. Yankee Group predicts that smartphones in the US will quadruple by then (from 40m to 160m) and does not seem to be very far off. Wireless Expertise thinks the global number will be 1.6bn, which again, might not be that far off.

The question is however if people will really download this much stuff: Yankee Group predicts that the actual value of the market will rise 10-fold and that the average price point of an app will be $2.37. Why that is so, you ask? Well, pay $495 and you will know; I don’t…

Now, the good folks of Wireless Expertise see the thing quadrupling until 2013. They do, however, count “ordinary” mobile games as they are being sold through carriers amongst the apps, which means that their starting point is higher, namely $4.6bn in 2009, so they’re looking at this quadrupling. They raise some smart points on app stores and how they (well, it) changed the way users access and consume content, how carriers will need to look for alternatives to increasingly commoditized voice and messaging propositions, etc. But why there should be a 400% rise in e.g. traditional J2ME mobile games remains – whilst it would be wonderful – pretty much in the dark.

Talking of J2ME and feature phones: I do not know how they are being woven into the equation but there would certainly be a wide field for any self-respecting crystal-ball-reader here: on the one hand, app consumption on such devices has traditionally been fairly shabby but, on the other hand, this could well change if connectivity, bandwidth, UI and the right price plans would come together to offer a compelling mobile web solution. So then apps would need to be translated into widgets or something like that. Would users then pay for them? Don’t know. Or would it be the “Freemium” model according to which “Free gets you to a place where you can ask to paid?”

The challenge of these reports is their “simplified” assumptions: if only one of them fails, you go “oops”, and your prediction is halved (or worse). On Wireless Expertise’s case, this is particularly clear: their assumption is that there will be a dual strategy of (presumably OEM-driven app stores) and mobile web-based widget stores. Now, they further assume that Ovi, Windows Market, etc will all be as successful as Apple’s App Store. By early (anecdotal) data, this could not be further from the truth (see here for what that may mean). Nokia in particular struggles to get its head around a viable and compelling media strategy (cf. here and here). And hence the beautiful hockey stick would actually fall flat on its face.

Now, I am not predicting total doom and gloom, in the contrary. I do think that Apple’s wake-up call has brought a much-needed new wave of innovation and I also believe that this will be successfully incorporated by some carriers and OEMs. But by all of them? Not very likely.

And so we see: the reports are a touch on the optimistic side when it comes to volumes and assumptions. But, hey, that’s their job, I guess, and after all they have at least dropped their masks now: Yankee Group call it fairly openly a “gold rush”. And what happens then we had been shown a long time ago: you end up eating your shoelaces. So maybe this is less of an app bonanza and more of an analyst bonanza then…

EA Mobile, Namco Bandai and the State of Carrier Decks

After many rumours and ominous statements that it was “reviewing its activities” Namco Bandai confirmed today that EA Mobile will thenceforth act as its distributor for mobile games outside the US and outside any app store.

After Taito and Eidos, EA Mobile just gobbled up another major distribution deal and the exodus from J2ME games distributed via carriers continues. It also means that EA’s dominance over the operator decks has just increased a little more yet again. It had estimated (back in June) that its 2009 mobile revenues would reach $185m (although this arguably includes Apple’s and other people’s app stores as well as embeds).

What is worrying is that this cements the oligopoly of games distribution in all major markets. EA Mobile, Gameloft occupy the top 2 slots very comfortably with Glu an equally comfortable but distant third. I-Play, Digital Chocolate, Real and Connect 2 Media are fighting for place and Xendex, Handy Games and a few others seek (and sometimes find) niches to prosper. THQ Wireless, Vivendi Games Mobile have departed. Player X found a new home under the mighty wings of Zed. And then? If the above companies all manage to maintain a healthy business, this might be enough; there are silverback gorillas in every market segment. If not though, this might become a doomed sub-sector; the limelight would then be on the (failed) ecosystem operators tried to build: overly fragmented with everyone of them wanting it just so and just their way rather than agreeing on a largely unified structure and processes pressed margins from a system that has been tough from the outset (handset fragmentation and international spread mean fairly high cost per capita anyway).

The accumulation of external properties arguably also mean that EA will need to run a business that is almost a combination of a publisher and an aggregator (with its very own challenges). The issue of shelf position (will they give Tetris and the Sims undue preference over Space Invaders, Pac-Man and Cooking Mama?), the commercials of their own deals (they anecdotally paid Hasbro a handsome sum), and the generally dominant position will all come into play and it is inconceivable (well, is it really?) that their partners will continue to play ball.

It might of course only be a brief interregnum on the way to an app store world. Smartphones are very much on the rise and, in that world, such stores seem to rule. Apple has taken the lead, Android followed suit and new stores are springing up almost by the day, which also includes operator-led ones: Orange already has one, Verizon Wireless has announced one (mobile web-based) and so has Vodafone (which might actually be bigger than Apples) as well as many others. The OEM all do the same (even though some carriers want to disallow them): Nokia Ovi, Blackberry App World, Sony Ericsson, LG, Samsung, you name them, they have it. The question of course is if that might mean the same thing all over again: will they again want it all just so? Will they again have it just their way so that a user would have the unique flavour of operator X on handset Y in this unique way, meaning that – again – thousands of SKUs would be required to service them? Groundhog Day? I hope not!

Image credit: http://www.antitrustreview.com/files/2007/07/files51lsaydhrsl.-ss500-.jpg

Mobile App Market worth $25 bn by 2014!?

Juniper is a research firm that regularly puts out 5-year forecasts, which it then varies equally regularly with new 5-year forecasts. So following on from the app vs web debate, Juniper rides to the rescue of the app world with its latest (well, not so fresh anymore really), predicting a not so modest $25 bn industry from mobile applications by 2014. There you have it, Google…

The big hockey stick will kick in from 2011 and it will come from value-added services rather than revenues from one-off downloads. Games will remain the biggest

So with this I wholeheartedly agree (as I pointed out here): the sector went from innovation through handsets to innovation through apps and is starting to enter innovation through services. If it will be a $25bn market in 5 years time, I don’t know. But then: the report is from April, so maybe they have varied it since.

The underlying rationale however is correct: mobile applications are merely a facilitator for the delivery of services to mobile devices, and there lies a lot of revenue hidden. So upwards, onwards!

So, Google: App Store or Web? Or Both?

Last week, there was the Mobilebeat conference on, and – amongst many other things – a lot of guys felt they had to air their opinions on the future of mobile apps or, errh, no apps. They spoke so elaborately about it that even the revered FT (albeit in its blog section) and the BBC felt compelled to run stories. Amongst others, the CEO of “indie” app store Get Jar and Google’s wonderful Vic Gundotra, VP Engineering and also equipped with this most valleyed of all Silicon Valley job titles, i.e. “Evangelist” (I would really like one like this, too!), in his case for developers spoke about where they saw information and entertainment on mobile phones going in the future and how the ecosystem would look like.

Now, let’s get serious.

What was Said?

First, GetJar‘s CEO sees the market for mobile applications becoming – get this – as big as the Internet (woah!). He then said also that it would peak at about 10m apps (in total?) by 2020. Hmm. GetJar then went on to warn that the number of developers would drop “drastically” and that only about 10% would be able to survive. The others would take their skills elsewhere. So where then? To the web? (This is of course interesting also because GetJar will deliver Sony Ericsson’s App Store…).

It is here where Google comes in. Gundotra said that, according to Google (and who would question them), the web had won. Even (!) Google was struggling with the device fragmentation in mobile and many, many applications could be delivered through “incredibly powerful” browsers as well. He even borrowed Steve Jobs for his argument, pointing out that the Apple CEO had announced that the iPhone was “Built for the Web” upon its launch.

There were others who contributed: Nokia’s Head of Services reminded everyone that Nokia was there to help with its Qt (Cutie, geddit?) cross-platform application network . The Symbian Foundation’s Executive Director, Lee Williams queried the need for more app stores and called, instead, for more than “just a bucket of apps”, which should look like an aisle with the very stuff that specific consumer is interested in and which (s)he could wander down at leisure.

They all however concluded that it [scil. the mobile web] was not there yet. Hm again… Let’s try to disentangle this all:

The Needle in the Haystack
Upon the launch of the app store and the wondrous stories of the iShoot developer Ethan Nicholas who coded in his bedroom after work only to resign from his day job weeks later because he made more money than he had ever thought. A lot of developers read that and, since it is the wet dream of every games developer (earn cash with an honest game without the “suits” fiddling with your game in between; anyone remember Copeland’s skateboarding turtle?), embarked on the journey themselves. And then they found, oops, it does not work that way? Why not? Well, because there are more than 400 applications going live every day. And with the sheer number of them, it could well be that the best app ever written is already out there but buried deep a couple of categories down in the app store.

This is no big surprise. It is how it works in any sector: one smart kid is not enough, you also need the environment and a lot of other building blocks to have a winner (as reigning F1 World Champion Lewis Hamilton is painfully realizing this year).

In the app store’s (and a gazillion other) case, this means that you have to make sure that you gain some attention. From Apple (or any other app store operator), from the press, from the users out there. And this is not news. There have been very well written pieces about this galore (see here for just one of them).

So will this mean the fall of a lot of the developers that went about their business thinking the app store magic would do away with centuries of business logic (there is a reason why companies have sales & marketing departments, you know…)? Yes, very probably. But does that mean the app model is flawed? No.

The Hit Dilemma

One of the Mobilebeat participants, namely Playfish, creators of some of the most successful Facebook games who released on the iPhone, too, complained about the hit-driven nature of games on the App Store. Whilst I am painfully aware of this dilemma, one has – again – to point out that this is pretty much how most of the economy works, too, unless, that is, one builds a superior and dominant brand (Tetris would be the example for the games world).

Other industries know this, too. Everyone knows IBM is a leading computer maker. Hardly anyone remembers that the Dutch electronics giant Philips used to be one of the biggest players in that market (not even Wikipedia mentions this); their CeBIT booth was bigger than IBM’s throughout the 70’s and early 80’s (my dad worked for Philips then; I need to dig out some pictures). What happened? Hey, they missed some crucial disruptive innovations and they were history…

What I want to say is that no one is immune to the demand for constant innovation and improvement (otherwise some Firefox will sneak around the corner and steal market share). The reason why this hit dilemma is more painful in mobile games than elsewhere is the relatively small size of the market to date: it is more difficult to build reserves than in other, more established sectors.

How Many App Stores? Mee too, me three, me four, …
With Apple’s roaring success with the app store, the whole industry stampeded to put out their own, and they have been moderately successful or failed. But it is early days! Why did they fail? Because they equally had hoped that one thing and one thing only (just name your bucket of apps an “app store”) would heal the painful failure of the sector in converting otherwise gladly paying users to also using, consuming, contributing to entertainment and information on their mobiles. Now, this overlooked that Apple’s model did not only consist of a storefront. It also consisted of a fairly simple developer programme (with a click-through agreement), a fair(er) revenue share to the developers and unprecedented ease of use in getting to the app of one’s choice. Try and apply this to, say, the launch of Nokia’s Ovi Store…

So do users need more than one store? No, not in general. If you can get all you ever need, want or desire from one destination, you don’t need another one. This however becomes a little precarious with a view to monopolizing channels. You would never know if there are not some that are a little more equal than you… So, having Firefox, Chrome, Opera, etc. next to Internet Explorer did the world a ton of good. And having Nokia, Sony Ericsson, the carriers working on alternatives to Apple’s app store is arguably of equal value. Will the user care? It depends on the execution: Google’s superior search algorithms made the old-style catalogue model previously found in search engines superfluous; why do I need to sort something if I have a little fairy that races to get me what I want in no time? So: if I have a bucket that comes with a little fairy, I don’t need long, long supermarket aisles. I’d rather get it home-delivered by the search fairies.

It’s the Usability, stupid!

Now to the key question: separate apps or web? Now in Google’s case, their pleading is somewhat obvious: well, they would, wouldn’t they?

Google, on the other hand, has apps out on most platforms for most of their web services: Be it Gmail (great Blackberry app!), Maps, or – all in one – their iPhone Google app, it comes as an app. And why?

Because it would otherwise be unusable! OK, let me rephrase that: the delivery of browser-based applications through mobile phones suffers some very severe setbacks today, amongst which usability on a small screen, constant connectivity and bandwidth. Whilst the latter two are arguably solvable some time soon, the former is a little trickier: when delivering to a mobile device, you not only have to download all underlying data (graphical assets, etc) but also an interface that works on that device. And because of the small form factor of mobile phones (even in the case of large-screen touchscreen phones like the iPhone), this is likely that your user experience will be significantly worse than on a large screen equipped with mouse, touchpad, etc. Apps can bridge this usability gap, and I would argue that this is precisely why Google is producing them. The underlying content can often (not always) well be delivered from the cloud but the UI of small devices is crucial to their sensibility.

With both (mobile) browser technology and handsets improving, the space available for services that can sensibly (and with superior costs) be delivered from the cloud (i.e. through the web) will increase, and steeply. However, there will always be applications that will either be impossible to deliver via the web (name a high-end 3D racing game on the web) or where a specific mobile UI would greatly improve the usability of any service.
It is another question if these will be delivered via flexible widgets or larger, more comprehensive apps (functionally, a lot of apps effectively are covert widgets); this will simply be (and remain) a question on the complexity of any given task and the ease and superior (or not) delivery an app would provide over a browser-based service. There will be an equilibrium between the two but I posit that there will remain large areas where browser-based delivery will not be able to compete with specific applications (that will draw on data from the cloud as well). Incidentally, 58% of Wired readers agree with me (and another 17% don’t care; check the bottom of the article) 😉

This can be seen on the (“normal”) web, too: Google Docs (Google’s online suite of office applications) is, despite a lot of effort and being free to use, an utter underdog to MS Office or Open Office (the only numbers I could find give Google Docs a market share of between 1% and 5%). It is, I think, because downloadable office “apps” are so much more usable (and react instantaneously irrespective of my ISP’s moods) than online services. The complexity of the computing (and – more importantly – the bandwidth necessary to deliver it) is just too overwhelming (see here for a previous post on this).

More evolved mobile apps often are (and/or will be) a hybrid: they offer a front-end that optimizes the data drawn from an online environment for use on a specific mobile device. It will not be an “either/or” but an “and”. Anything else would anyway be so last century!

In Conclusio:

Whenever possible, services will move online because it is cheaper to produce. Whenever necessary, they will be delivered through dedicated apps because it is required to use them!

Is Apple to break iPhone exclusivity?

There have been rumours galore about Apple’s exclusive deals for its iPhone all over the place (see e.g. here for Verizon). New reports have now surfaced that appear to confirm that Apple is looking at this option for both the US and the UK (and, if this works, presumably also for other territories):
In the UK, T-Mobile confirmed it was in talks with Apple over stocking the iPhone 3G (the 3GS remaining exclusive to O2, which also has its hands on the Palm Pre) and Orange is “believed”, to be as well.

In the US, the Verizon discussion has been around for a while. A new report now suggests that losing the exclusivity would spell doom for AT&T: the report estimates that as much as 30% of AT&T’s customer are with the carrier solely because of the iPhone exclusivity. This sounds a little high to me: after all, the iPhone penetration in the US is much lower than that (it held just under 11% market share globally in Q1/2009). Are they saying that all the other users (those with the less fancy handsets) just stay on AT&T to share into the iPhone limelight? No, I thought not…
Apple is in any event in a beautiful position at the moment: so far, most of its competitors’ “iPhone killers”(Palm Pre, Blackberry Storm and innumerable devices from Samsung, LG and Nokia) have failed to challenge its numbers and, quite literally, all of the app stores set up by competitors showed meagre results compared to the – now – 1.5 bn (!) downloads in a little over a year from the Apple App Store. The good folks from Cupertino are therefore now in a pretty good position: they proved (a couple of times now) that they shift 1m+ devices – on the opening weekend! They bring a lot of sex appeal in which the carriers, not generally known for coolness, can bask. They cracked the content dilemma and produced a thriving developer community, which made people actually use their phones for all these things that have been promised for so long (iPhones are connected, most others can connect). In short: in carriers eyes, they are – aside from the horrible fact that Apple takes a healthy cut – a really good thing for networks that see themselves locked into cut-throat pricing wars over voice and SMS (bringing in, anecdotally, up to 50% of European carrier profits over the past 5 years) and craving for a way to increase user ARPU (app revenue on the iPhone is, apparently, $27 per device). Happy days…
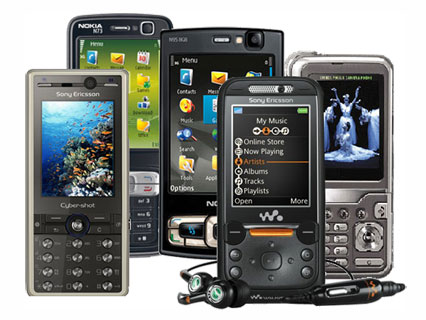
Mobile Innovation; in Response to Scoble

Egoblogger extraordinaire Robert Scoble has never been known to be shy, and so he declared with his usual great fanfare that Europe did not matter any more in terms of mobile innovation. Why did he say that, you ask? Well, Nokia apparently took him to visit their research lab in Cambridge (no, not in Espoo) as part of a (Nokia-)sponsored geek tour. And Scoble was not impressed. Because (1) everyone appears to have been texting when he was on the tube (how quaint), (2) the N97 isn’t cooler than the iPhone and (3) Symbian is much clunkier than the iPhone’s OS or Palm’s WebOS, Scoble deduces that Europe has had it.

He reduces this loss of leadership in mobile innovation to handsets or, more specifically, to the coolness factor of handsets (“London’s cool kids are [not] hot and bothered” about the N97). And, with that somewhat tight limitation, he might actually be right. Nokia has been losing ground on the coolness and usability front for quite a while. However, when it comes to technical ability, their devices are still quite hot. Scoble basically uses the iPhone plus the first Android-based (Taiwanese [sic!]) phones to declare that the king is dead.

Hardware is a Commodity

Now, let’s try to differentiate a little. Would you say the US have the lead in computer manufacturing? Well, probably not. IBM’s ThinkPads are Chinese, then there is Sony, Samsung, Toshiba, and there is HP and Dell. There is of course also Apple (“designed in California”). Does it matter at all where the hardware is from? No, not at all, and no one really cares anymore. And why not? Because hardware is basically a commodity, that is in a world where one does not actually see that much of the hardware because the interfaces are software-driven. And these are from Microsoft, etc.
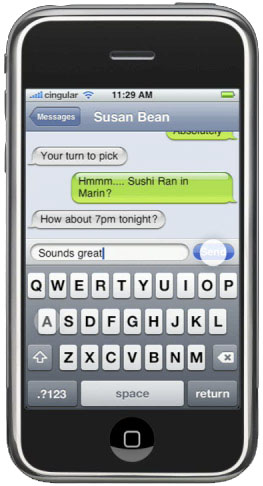
In mobile, this has not been true in the past because their were such vast differences in the available hardware that the usability was severely impaired should you have been using, say, a low-end Motorola device as opposed to a high-end Nokia. This is where the myth of European mobile superiority comes from. And, with Apple, RIM and maybe Palm again, this is firmly in North American hands. There are of course Samsung and LG, the Korean powerhouses who drive their market share up and up. Android devices G1, G2 and Magic are from Taiwanese HTC. However, given how far mobile software and indeed services have come: does it really matter either way today? I say it does not.

Here’s the Innovation: Services

If one wants to see where mobile innovation is happening, one would need to go to South Korea, Japan, Finland (not the Nokia research labs but, say, the public transport system where you can pay via SMS for the past couple of years already), Austria (mass deployment of mobile RFID-payments), South Africa (mobile wallets and very evolved mobile marketing services), Malaysia, the Philippines and even Kenya (mobile money transfers). Certainly not the US though, I’m afraid. They are still the country where “can you hear me now?” campaigns rule.

The iPhone has changed a lot of things of course. However, American Idol arguably did a lot more. It brought, shock, horror, texting to the Americans. SMS being, of course, a service. And why, Mr Scoble, should that be bad? Carriers (other than in the US) have made 25% of their revenues and 50% of their profits over the last 10 years with this unassuming little thing. That’s not too shabby, is it? The iPhone (and Palm’s WebOS) have introduced a new level of ease of use, and one that was long overdue. One that woke Nokia, which had comfortably dominated the space with less and less innovation on the software side, up (and Nokia might be a little slow to open their eyes properly). And one that will improve service levels all over the world.
Where the Big Market is

However, let us also not forget that the best-selling phone of all times is the Nokia 1100. No, it doesn’t do Java. It has a battery life of close to 20 years though and comes with a flashlight installed. Both very handy things to have in rural parts of developing or emerging countries. Nokia is having a fairly comfortable market share in these countries. I am not sure if that is a good thing to rest on though: as these markets, they demand more sophisticated devices. And because the computer penetration is much lower than in Europe, Japan, South Korea and North America, the significance of evolved mobile devices will be even more important. Nokia thought this would carry it through. However, we are seeing now that that might not be so: its smartphone market shares are rapidly decreasing.

Europe is not Europe

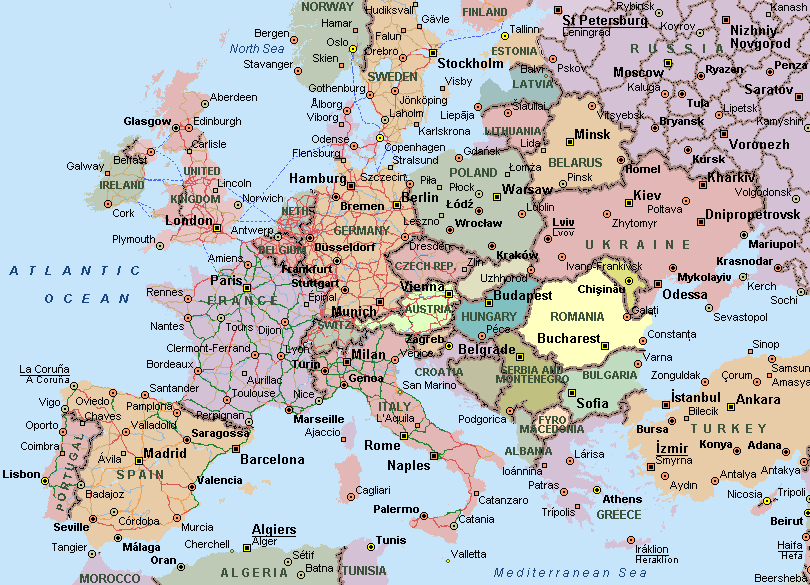
One last word on Europe: distinct to what Mr Scoble appears to have in mind, Europe is not a country, and this is not meant to be sarcastic. Europe is a pile of little countries and in each of them a couple of carriers rule like little kings. It makes for an extremely complex (and, consequently, low-margin) playground to deploy services. The US (as well as some of the huge Asian countries) have the incredible opportunity to deploy applications and services in one language through less than a handful of carriers to hundreds of millions. No such thing in Europe.
And this is why the US should lead in every aspect really: it is an evolved, competitive economy and it enjoys the tremendous upside of being (almost) completely aligned as to the framework: language, currency, carriers, billing systems, legal system, etc. This is the reason why the US has indeed leapfrogged Europe, the continent, when it comes to basic mobile applications: economies of scale are much easier to achieve there.

Software, Services, Interfaces

When one looks at Nokia in its current state as the sole indicator of where European mobile innovation is, one might be disappointed (as I pointed out numerous times, e.g. here). However, when one looks at how concert tickets are being sold via mobile, public transport, parking fees and vending machines all using mobile as a wallet solution, or indeed Obama making his latest speech available via SMS (there are more than 10x as many mobile phones in Africa than PCs according to Tomi Ahonen), then one can and should still be awed. And, no, in spite of its President the US is not (yet) close in this respect.

I hope, however, the US will catch up on this front sooner rather than later, too. Because of the size of the market and the aforementioned advantages, it would unleash incredible opportunities that would bring all of us fantastic new services and applications. And, Mr Scoble, it does not matter if these are 160 characters or polished web pages; it depends on what you want to do with it (as you, being one of the most prolific Twitterati, surely know).

I did not text anymore because I hated the UI and could not stand the clunky interfaces (in spite of T9; I’m too old, I guess). I started again with the iPhone. Why? Because – distinct what some people say – it’s a great interface: it displays the conversation, it looks neat and I have a full keyboard (the touch screen works much better than I feared; and I used a Blackberry for years and years). But that is not a question of the device or the technology, it is solely a question of the software. I would be much happier if I could also use my iPhone (or any other phone) to buy my newspaper (which I can with an RFID-equipped credit card in this country and which I could do in, say, Austria, a country with 2/3 the population of Illinois and a footprint smaller than Maine).

What Scoble misses (or omits in his post) is that the next leap in innovation will be a service-driven one (just as we saw on the Internet: first hardware, then basic apps, now sophisticated services).

Mobile has had the hardware phase, it is going through a “basic” app phase, and some European, African and Asian countries have entered the value-added services phase already, some years and years ago in fact! Compared to the US, they’re leading, by a lot! They’re perhaps just too small for the Robert Scoble to realize they’re there… But, as I said above: this is not about Europe leading the US (apart from the fact that it would appear to being Asia that is truly leading and has been for a while): it is about the evolution of an incredibly powerful communication device that is being unlocked for more and more applications and services; and this is independent from country and nationality!

Along those lines: why, Mr Scoble, should it be a bad thing that Europeans now “must” visit Cupertino and Mountain View. California is nice, isn’t it? Not a bad thing to go visit every now and then at all! We’re living in a large world, Mr Scoble, not only on a single continent, and mobile is a facilitator spurning new ecosystems, not only a device.

Image credit drawing: http://www.aartkom.cz

Page 7 of 10

Powered by WordPress & Theme by Anders Norén