Category: OEM Page 6 of 15

Handmark powers Samsung’s App Store

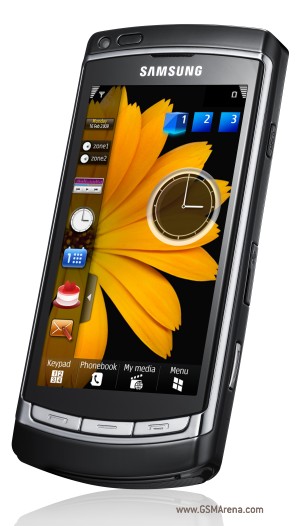
Samsung’s new app store (no one can do without one these days!) will be operated by Handmark and is set to go live on 14 September (2009, that is), I read. The respective site is (sort of) live and appears to accept registrations of prospective vendors. Go here if you feel like it… Launch will be in the UK, France and Italy first. No word when the others follow.

According to the press release, the content available will consist of Windows Mobile and Symbian s60 titles and will be available on the Omnia, I8910HD, Omnia II and Omnia Lite (so a true omni-store then). Billing is available via both credit cards and operator billing, which is – on the face of it – good (i.e. plain and simple credit card-billing doesn’t often work; Apple’s app store is an exception, I’d say, because input is via iTunes with which people are already familiar).

I’ll spare you the rest of the lyrical odes to the various partners… But let’s try and break this down: how big will this thing then be? Samsung is a force in mobile and its Omnia phones have had some very significant success indeed: in some markets (Germany was one), the Omnia outsold the iPhone by some margin (in December 2008, the Omnia had a 14.9% share of the German smartphone market compared to the iPhone 3G with 7.6%). It also launches in India now. I could not get my hands on solid sales numbers though (in the top 10 list by accessory sales for June, the Omnia came in on #10)… However, anecdotally, it is behind Nokia, RIM and Apple in global smartphone market share. So if we say that, on a global basis, there will be about the same number of devices around, that would make the phones a good success for Samsung.

However, when it comes to usage, I am not sure if the Omnia can compete with the iPhone. If we take ad impressions as an indicator (and it really is just that), we’ve seen that the iPhone’s 8% market share translates into 40% ad impressions. And because a lot of apps (and web “apps”) use ads, I think it is probably safe to assume that usage is higher. And this is arguably the crux of app successes: they need to be available but they also need to be discoverable and usable, and all of this with a lot of ease. Will they succeed? I hope so as it would do a ton of good to the industry would there be more than the niche player Apple. Their new TouchWiz SDK (see here) should help ease development for better UI, and the features of the store they announced look decent so far, so let’s keep our fingers crossed!

Image credit: GSM Arena

iPhone outsells N-Series

Last week was quarterly reporting week, and both Apple and Nokia let us have a glimpse on whatever they did. Subsequently, some reported (via Twitter) that the iPhone outsold the N series for the first time.

Nokia first: In Q2, Nokia sold 103.2m units (down 15% year-on-year but 11% as compared to Q1). Total sales of “smartphones” amounted to 16.9m devices, of which 4.6m were N series (the balance being made up of E series and some “numbered” devices, of which the 5800 series took the biggest share). The total number of Nokia smartphones (or “converged devices”) in market was thought to be 41m. Nokia estimated its share of the smartphone market to amount to 41%, which would be up 2 points from the previous quarter. I wonder…

Apple, by contrast, reported that it sold a whopping 5.2m iPhones in Q2 (Apple’s financial Q3), which means that the iPhone outsold the Nokia flagship smartphone series for the first time. A couple of years ago, no one would have thought this was possible! It is noteworthy that this does not even include the iPhone 3GS, which only went on sale after the close of the quarter.

After all the worries about Nokia’s performance (see e.g. here, here and here) and the relevance of Apple’s “minute” market share in relation to the total handset market, this is a very important benchmark: not only does Apple beat Nokia in an important segment (the N-series traditionally spear-headed Nokia’s mass market assault on the higher-end side of handsets) but it also shows the dynamics behind Apple. Nokia’s distribution and incumbent market footprint is hugely superior than Apple’s and yet Apple manages to outsell them. Very impressive indeed!

Is Apple to break iPhone exclusivity?

There have been rumours galore about Apple’s exclusive deals for its iPhone all over the place (see e.g. here for Verizon). New reports have now surfaced that appear to confirm that Apple is looking at this option for both the US and the UK (and, if this works, presumably also for other territories):

In the UK, T-Mobile confirmed it was in talks with Apple over stocking the iPhone 3G (the 3GS remaining exclusive to O2, which also has its hands on the Palm Pre) and Orange is “believed”, to be as well.

In the US, the Verizon discussion has been around for a while. A new report now suggests that losing the exclusivity would spell doom for AT&T: the report estimates that as much as 30% of AT&T’s customer are with the carrier solely because of the iPhone exclusivity. This sounds a little high to me: after all, the iPhone penetration in the US is much lower than that (it held just under 11% market share globally in Q1/2009). Are they saying that all the other users (those with the less fancy handsets) just stay on AT&T to share into the iPhone limelight? No, I thought not…

Apple is in any event in a beautiful position at the moment: so far, most of its competitors’ “iPhone killers”(Palm Pre, Blackberry Storm and innumerable devices from Samsung, LG and Nokia) have failed to challenge its numbers and, quite literally, all of the app stores set up by competitors showed meagre results compared to the – now – 1.5 bn (!) downloads in a little over a year from the Apple App Store. The good folks from Cupertino are therefore now in a pretty good position: they proved (a couple of times now) that they shift 1m+ devices – on the opening weekend! They bring a lot of sex appeal in which the carriers, not generally known for coolness, can bask. They cracked the content dilemma and produced a thriving developer community, which made people actually use their phones for all these things that have been promised for so long (iPhones are connected, most others can connect). In short: in carriers eyes, they are – aside from the horrible fact that Apple takes a healthy cut – a really good thing for networks that see themselves locked into cut-throat pricing wars over voice and SMS (bringing in, anecdotally, up to 50% of European carrier profits over the past 5 years) and craving for a way to increase user ARPU (app revenue on the iPhone is, apparently, $27 per device). Happy days…

Mobile Innovation; in Response to Scoble

Egoblogger extraordinaire Robert Scoble has never been known to be shy, and so he declared with his usual great fanfare that Europe did not matter any more in terms of mobile innovation. Why did he say that, you ask? Well, Nokia apparently took him to visit their research lab in Cambridge (no, not in Espoo) as part of a (Nokia-)sponsored geek tour. And Scoble was not impressed. Because (1) everyone appears to have been texting when he was on the tube (how quaint), (2) the N97 isn’t cooler than the iPhone and (3) Symbian is much clunkier than the iPhone’s OS or Palm’s WebOS, Scoble deduces that Europe has had it.

He reduces this loss of leadership in mobile innovation to handsets or, more specifically, to the coolness factor of handsets (“London’s cool kids are [not] hot and bothered” about the N97). And, with that somewhat tight limitation, he might actually be right. Nokia has been losing ground on the coolness and usability front for quite a while. However, when it comes to technical ability, their devices are still quite hot. Scoble basically uses the iPhone plus the first Android-based (Taiwanese [sic!]) phones to declare that the king is dead.

Hardware is a Commodity
Now, let’s try to differentiate a little. Would you say the US have the lead in computer manufacturing? Well, probably not. IBM’s ThinkPads are Chinese, then there is Sony, Samsung, Toshiba, and there is HP and Dell. There is of course also Apple (“designed in California”). Does it matter at all where the hardware is from? No, not at all, and no one really cares anymore. And why not? Because hardware is basically a commodity, that is in a world where one does not actually see that much of the hardware because the interfaces are software-driven. And these are from Microsoft, etc.

In mobile, this has not been true in the past because their were such vast differences in the available hardware that the usability was severely impaired should you have been using, say, a low-end Motorola device as opposed to a high-end Nokia. This is where the myth of European mobile superiority comes from. And, with Apple, RIM and maybe Palm again, this is firmly in North American hands. There are of course Samsung and LG, the Korean powerhouses who drive their market share up and up. Android devices G1, G2 and Magic are from Taiwanese HTC. However, given how far mobile software and indeed services have come: does it really matter either way today? I say it does not.

Here’s the Innovation: Services

If one wants to see where mobile innovation is happening, one would need to go to South Korea, Japan, Finland (not the Nokia research labs but, say, the public transport system where you can pay via SMS for the past couple of years already), Austria (mass deployment of mobile RFID-payments), South Africa (mobile wallets and very evolved mobile marketing services), Malaysia, the Philippines and even Kenya (mobile money transfers). Certainly not the US though, I’m afraid. They are still the country where “can you hear me now?” campaigns rule.
The iPhone has changed a lot of things of course. However, American Idol arguably did a lot more. It brought, shock, horror, texting to the Americans. SMS being, of course, a service. And why, Mr Scoble, should that be bad? Carriers (other than in the US) have made 25% of their revenues and 50% of their profits over the last 10 years with this unassuming little thing. That’s not too shabby, is it? The iPhone (and Palm’s WebOS) have introduced a new level of ease of use, and one that was long overdue. One that woke Nokia, which had comfortably dominated the space with less and less innovation on the software side, up (and Nokia might be a little slow to open their eyes properly). And one that will improve service levels all over the world.

Where the Big Market is

However, let us also not forget that the best-selling phone of all times is the Nokia 1100. No, it doesn’t do Java. It has a battery life of close to 20 years though and comes with a flashlight installed. Both very handy things to have in rural parts of developing or emerging countries. Nokia is having a fairly comfortable market share in these countries. I am not sure if that is a good thing to rest on though: as these markets, they demand more sophisticated devices. And because the computer penetration is much lower than in Europe, Japan, South Korea and North America, the significance of evolved mobile devices will be even more important. Nokia thought this would carry it through. However, we are seeing now that that might not be so: its smartphone market shares are rapidly decreasing.

Europe is not Europe
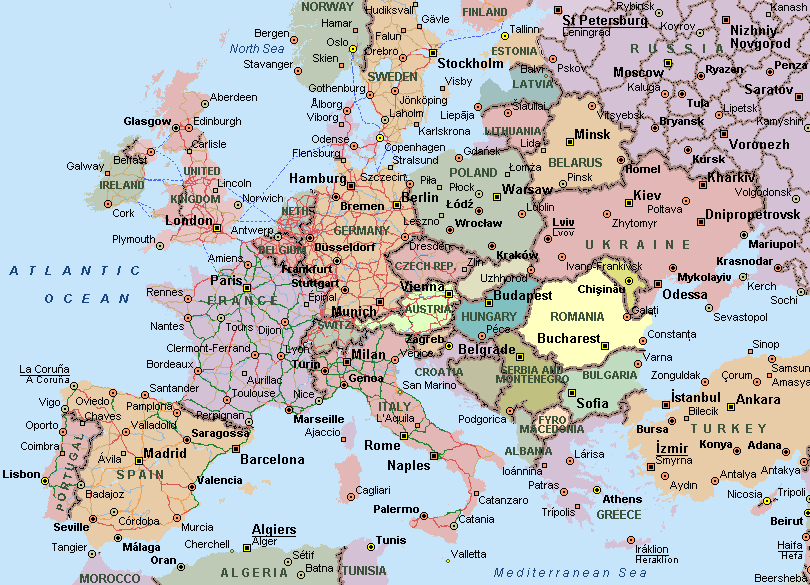
One last word on Europe: distinct to what Mr Scoble appears to have in mind, Europe is not a country, and this is not meant to be sarcastic. Europe is a pile of little countries and in each of them a couple of carriers rule like little kings. It makes for an extremely complex (and, consequently, low-margin) playground to deploy services. The US (as well as some of the huge Asian countries) have the incredible opportunity to deploy applications and services in one language through less than a handful of carriers to hundreds of millions. No such thing in Europe.

And this is why the US should lead in every aspect really: it is an evolved, competitive economy and it enjoys the tremendous upside of being (almost) completely aligned as to the framework: language, currency, carriers, billing systems, legal system, etc. This is the reason why the US has indeed leapfrogged Europe, the continent, when it comes to basic mobile applications: economies of scale are much easier to achieve there.

Software, Services, Interfaces

When one looks at Nokia in its current state as the sole indicator of where European mobile innovation is, one might be disappointed (as I pointed out numerous times, e.g. here). However, when one looks at how concert tickets are being sold via mobile, public transport, parking fees and vending machines all using mobile as a wallet solution, or indeed Obama making his latest speech available via SMS (there are more than 10x as many mobile phones in Africa than PCs according to Tomi Ahonen), then one can and should still be awed. And, no, in spite of its President the US is not (yet) close in this respect.
I hope, however, the US will catch up on this front sooner rather than later, too. Because of the size of the market and the aforementioned advantages, it would unleash incredible opportunities that would bring all of us fantastic new services and applications. And, Mr Scoble, it does not matter if these are 160 characters or polished web pages; it depends on what you want to do with it (as you, being one of the most prolific Twitterati, surely know).

I did not text anymore because I hated the UI and could not stand the clunky interfaces (in spite of T9; I’m too old, I guess). I started again with the iPhone. Why? Because – distinct what some people say – it’s a great interface: it displays the conversation, it looks neat and I have a full keyboard (the touch screen works much better than I feared; and I used a Blackberry for years and years). But that is not a question of the device or the technology, it is solely a question of the software. I would be much happier if I could also use my iPhone (or any other phone) to buy my newspaper (which I can with an RFID-equipped credit card in this country and which I could do in, say, Austria, a country with 2/3 the population of Illinois and a footprint smaller than Maine).

What Scoble misses (or omits in his post) is that the next leap in innovation will be a service-driven one (just as we saw on the Internet: first hardware, then basic apps, now sophisticated services).

Mobile has had the hardware phase, it is going through a “basic” app phase, and some European, African and Asian countries have entered the value-added services phase already, some years and years ago in fact! Compared to the US, they’re leading, by a lot! They’re perhaps just too small for the Robert Scoble to realize they’re there… But, as I said above: this is not about Europe leading the US (apart from the fact that it would appear to being Asia that is truly leading and has been for a while): it is about the evolution of an incredibly powerful communication device that is being unlocked for more and more applications and services; and this is independent from country and nationality!

Along those lines: why, Mr Scoble, should it be a bad thing that Europeans now “must” visit Cupertino and Mountain View. California is nice, isn’t it? Not a bad thing to go visit every now and then at all! We’re living in a large world, Mr Scoble, not only on a single continent, and mobile is a facilitator spurning new ecosystems, not only a device.

Image credit drawing: http://www.aartkom.cz

AdMob on iPhone ad impressions and why Andrew Bud is wrong

Mobile advertising firm AdMob has released some numbers on ad impressions on iPhone vs other smart phones and the result is, well, that Apple is basically a 50kg flyweight boxer competing against Sumo wrestlers 5 times it weight (8% smartphone footprint but more than 40% ad impression share).

Now, very (!) crudely put, this does not mean that it is 8 times as successful on mobile advertising. It does mean however that users are 8 times more likely to use applications where ads are being displayed. Here’s some of their stats:

iPhone Apps (in AdMob’s network):

  • The top iPhone apps had more than one million users in the UK in May 2009
  • 5% of iPhone apps had more than 100,000 active users in May 2009
  • 14% of iPhone apps had between 10,000 – 100,000 active users in May 2009
  • 27% of iPhone apps had between 1,000 – 10,000 active users in May 2009

Mobile web browsing market in May 2009:

UK:

  • 48.7% of ad requests came from Apple handsets (iPhone and iPod Touch)
  • 28.4% of ad requests came from the iPhone
  • 282,493,761 ad requests from users in the UK

US:

  • 45.1% of ad requests came from Apple handsets
  • 25.7% of ad requests came from the iPhone
  • 3,804,373,544 ad requests from users in the US

Global:

  • 31.4% of ad requests came from Apple handsets
  • 18.6% of ad requests came from the iPhone
  • 7,997,946,483 ad requests from users around the world

Interestingly, MEF and MBlox Chairman Andrew Bud (who is being quoted at the end of the article) said that Apple’s app store compared to Nokia’s Ovi Store like a niche boutique to Tesco (or, if you are in the US, Walmart). Is that so? No it is not. And here’s why:

Apple is a boutique with more items on sale than a Tesco megastore. And its (less) customers buy trolleys full of wares. Moreover, their high-spending customers leave the store with a spring in their step and committed to come back the next day.

Nokia is a super-store with gazillion potential (!) customers where 1 in 20 stroll through aisles stocked with not so cool things and most of them walk out without buying anything and, on top of that, feeling fairly downtrodden and frustrated about what was on offer.

So, for the time being, I’d choose the Apple boutique. If that choice changes will depend on whether Nokia will manage to stock their shelves with more compelling wares and improve on their tills (less queuing, more bang for your buck, etc). Oh, and get those cold strip-lights replaced, please!

Top 10 Mobile Phones in June 2009

Here’s our monthly update on the best-selling phones as derived from accessory sales by Swedish company Krusell. They seem to be having a new product line: the iPhone shows up now (and as a “new entry” no less). It is arguably to show the limited value of this table in terms of overall sales.
It is noteworthy that June’s #1 phone (Nokia 6300) is a handset that was introduced to the market more than 2 years ago. Now it is a very solid performer (as my wife will tell you) and has been used as a very good-value phone (£0.00 when bought on a pay-as-you-go) by a lot of carrier. Or is it that the phone is now so shabby it needs to be covered by a plush holster? :p

I thought it is also noteworthy that Nokia’s new flagship the N97 (or any other N-series Nokia) is not featuring at all… It might be early days for the N97 but the others?

Well, make of it what you will, here’s the top 10 list (oh, wait, it’s a top 11 this month; woah):

1. (3) Nokia 6300
2. (-) Apple iphone 3G
3. (-) HTC Touch Diamond 2
4. (2) Nokia 3109
5. (-) Nokia E51
6. (1) Nokia 5800
7. (5) Nokia E71
8. (6) HTC Touch HD
9. (-) HTC Magic
10. (-)HTC Touch Pro2
11. (4) Samsung SGH-i900/i910 Omnia
() = Last month’s position.

iPhone App Store once again: how much?

It is early July and we have not been reading analysts’ estimates on how much Apple may or may not make from application downloads through its app store for at least, what, 2 weeks (here’s a piece from a while ago). High time for another round then… This time, the number is “a few hundred million at best”, per quarter that is. And to be perfectly fair, the number was tagged as a guestimate. With another guestimate putting Apple’s iPhone revenue to $1.5 bn, the revenue per iPhone to Apple is thought to be around $600. Compare this to c. $27 in apps revenue per device (total number of apps divided by total number of devices). It’s 5%.
It is, I think rightly, pointed out that Apple uses applications as a lever for its hardware sales (“there’s an app for that”), and it is undeniable that a device gains more value the more you can do with it. So if you have a device that cannot only make phone calls, take photos (and now video), moonlight as a music player and a sat nav, etc but also finds restaurants, taxis, flight times and undertakers (yes, it does!), allows you to play all sorts of games and do other silly or enlightening things, the perceived value of the device increases and – relative to that – the perceived fair price for it decreases, which means that every little app increases the value of the iPhone a tiny bit, which in turn contributes to another little piece of profit to Apple in addition to its revenue share from the app itself (lowered price sensitivity due to higher perceived value arguably should result in higher sales).

Now this is largely known and acknowledged that Apple is – at least to an extent – replicating the iPod/iTunes model (though Apple also happened to provide the first commercially successful “cure” to free music downloads; hence a slightly different proposition here). But is this all bad?

Let’s have a look at the thing from an app provider’s perspective: if we take the above numbers (“a few hundred million” per quarter), the annual total would be, say $1 bn for Apple, which in return means that the app store “ecosystem” would generate c. $3.3 bn p.a. across the value chain (Apple takes 30% revenue share). That’s not too shabby for a device with such a small market share.

Also: iTunes (which is the world’s largest music retailer) took longer than the app store to generate the downloads it does today, and it is still early days, is it not?

Page 6 of 15

Powered by WordPress & Theme by Anders Norén