Category: OEM Page 5 of 15

Good bye Symbian?

First, Samsung announced it would drop Symbian from its smartphones in 2010 in favour of its new, home-brew bada OS. Then Nokia said it would drop Symbian (albeit not immediately) from its flagship N-series devices replacing it with Maemo, the OS that premiered on a Nokia device on the recently released geek dream, the N900.

It is said that there are

no current plans for Maemo devices in the […] X-Series range or the popular [?] E-Series enterprise range

but the word “current” suggests that this might well change soon, too.

This would leave Symbian without its two largest OEM supporters. Will there still be a future for it?

Symbian of course boasts a still very impressive number of legacy devices, and it will therefore be here for a while. However, what does the long-term outlook look like? Android, LiMo, etc all “boast” a nimbler, more agile set-up, allowing for faster development and, arguably, better user experience. This is not necessarily Symbian’s fault (it carries with it its legacy around) but it makes it that much harder for it to reinvent itself.

I am not sure if there is place (and – timewise – the runway) to reinvent itself without the backing of big OEMs. I would be surprised if carriers would use it; they – even more than OEM – require adaptability and customization, which the newer platforms seem better suited to serve. Vodafone’s choice of LiMo for their first two Vodafone 360 devices is testament to that.

The ever-bright Tomi Ahonen suggested a comparison with DOS/Windows and MacOS: he compares Symbian to DOS, Maemo to Windows and iPhone to MacOS: MacOS led in UI and leads to this day. DOS outsold MacOS in spite of its dramatic inferiority because of the legacy instal base. Windows then overlaid DOS and rolled out on all the legacy devices with MacOS, as a result, always playing second fiddle despite its superiority.

The market place in mobile looks different though: DOS was nigh dominant (outside the mainframe and large enterprise side of things) whereas Symbian “only” covers about 5% of the current market. It is big but probably not big enough to bridge the DOS/Windows migration gap. With Android, Blackberry, Windows Mobile, LiMo, JavaFX (if that ever takes of properly), etc all on the map, too, the situation is very different to the DOS/Windows/MacOS world. Would Nokia be quicker in execution, I might still look at it differently but, unfortunately, it doesn’t seem to be that way.

So is it good bye, Symbian, then?

An Example Why Nokia Struggles

Yesterday, Nokia announced the “Nokia 5330 Mobile TV Edition”,

“an entertainment hub that combines mobile broadcast TV (DVB-H), social networking, music and gaming in one compact 3G device.”

Let that sink in: it is – apparently – not a phone. Mentioned nowhere. Well, it is of course but one might ponder if that is the message you want to get across. Focus?

Be not mistaken though, it offers some rather incredible specs: a full six hours (!) of mobile TV broadcast without re-charge. That is 3 football (my US readers, scil. soccer) matches (although I am not sure where, when and why one would do that). Compare that to the iPhone where you could watch maybe 30 minutes of highlights IF you have downloaded the respective clips when you were in a WiFi zone last. The headset doubles as an antenna.

QVGA on a 2.4″ screen, 3.2 megapixel camera (presumably with the trusty Carl Zeiss lenses, LED flash, video, free music via the “Comes with Music” service. It also says (well in the punchy headline above anyway) that it will also have specific gaming capabilities.

Phone calls? That is so last year… It is not a phone, it is an entertainment hub, baby!

The device but even more so the press release exemplify the challenges Nokia faces. It is not the technology; the Fins are good at that. It is not distribution network; they have excellent carrier relationships the world over. But the package and its presentation makes it almost anti-climactic – and probably unfairly so because the thing does even look pretty neat!

Now, if one needs TV broadcast is a discussion all by itself (the fact that you can set reminders “to make sure key episodes aren’t missed” sounds almost quaint in the age of TiVo and the iPhone’s Sky+ app).

But even apart from this, it is an example that demonstrates the approach: Nokia tries to answer calls querying its continued leadership by building monolithic technology beacons. But that is not why users flog to the iPhone; they merely want something that looks good and works beautifully. Dear Nokia, IF you equip a phone (a phone, not a multimedia hub!) with every gadget under the sun, this is cool – it really is! But do not sell it on technology, sell on user experiences. Users do not generally care much for tech talk (well, maybe some boy racers and hardcore coders do), they care for ease. Give them ease!

Apple’s overriding design goal is (and has been for a while) to de-clutter the user environment and experience. Then they execute nicely on it. That is what makes them so superb. Try to emulate this. You have all the tools. Now get the pitch right, will you?

What about this Dell Phone?

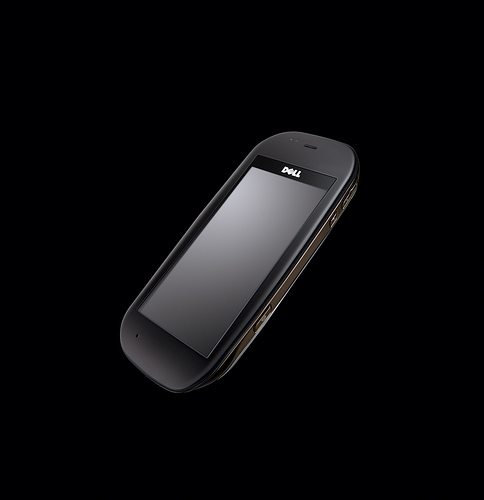
Dell, after a lot of denials, finally confirmed release of its first smartphone, the Dell Mini 3. The device will run on Android (as well as on China Mobile’s specific Android flavour, called OPhone) and features a 3.5” touchscreen. Otherwise? Erm, not much known. No WiFi for China to be sure, at least not at the start.

In a move that was ridiculed by some, Dell chose China Mobile and Claro Brasil as its first partners to distribute it. Some sources suggested this may be “crazy” but I am wondering why that is so? Because it’s not – no offence – Idaho? China Mobile has 508m subscribers, that is 200m more than the population of the US. Claro has 28m subscribers in Brazil, its holding company America Movil has 194.3m subscribers. That’s not shabby! And there is larger growth potential in these markets, too. The raised eyebrows may simply come from the fact that this is (or at least appears to be) the first time that a US vendor chose emerging markets as its launch territories. I would suggest that this is only the beginning: it is these markets where the large majority of user growth resides. Good move that.

Now to the more critical points, and a small one at first: They could have done better on the marketing. Apple shows everyone how it’s done: come out with a bang and woe them. I do not think there is a need to outperform competitors on the technical side but a strong launch allows you to tell your story rather than leave it to a plethora of commentators to pave the way.

The larger question will be if and what the Dell smartphones offer that others don’t. Will a Dell phone connect more seamlessly with a Dell computer (or any computer for that matter?). Will it have some nifty little features that have the power to make a difference? Never mind that Michael Dell may not have the coolness factor of Steve Jobs; that’s fine. But will the devices be good? Dell has shown it can do it (with its PDA Axim that of course died together with the rest of the market). The smartphone market is only starting to evolve, so the timing might be better this time. Let’s see…

N-Gage dies (again)

Nokia’s N-Gage game service has just been declared dead, well dying anyway. always been a concept that has under-delivered painfully. In its first iteration, the device, it was a gutsy but maybe not entirely thought-through attempt to combine phone and dedicated handheld gaming device (it was always going to lose as one simply looked outright silly even when putting the thing towards ones ear to make a call – even when stood at a Star Trek convention, and that is telling). The “new” iteration, the software platform, struggled to take off. Nokia tried mightily to produce showcases demonstrating the superior gaming abilities of the platform compared to “regular” feature and smart phones but the efforts were thwarted from a number of angles:

Too expensive

It was a costly affair to deliver a game optimized for the N-Gage platform. When there is no proven distribution model that can guarantee decent returns, there would always be limited uptake from developers and publishers.

Too small a niche

N-Gage was always geared towards dedicated gamers. All marketing was directed this way, the positioning was distinctly high-end, no non-game applications were shown (or even contemplated, I guess). The power of the platform thus was funneled into a niche of a niche, i.e. high-end gaming. I would suggest that one could as easily have positioned it as a powerful media platform full stop. One that allows for beautiful execution of any number of simple or complex apps (and a game is basically “only” one app category).

There’s an app for that

The iPhone then was arguably the final punch. In spite of developer frustrations growing over discoverability within this pile of 100,000+ apps, the platform has spurned exceptional games galore, and not only casual ones either. Real Racing is as punchy a racing title as one will ever get one on a handheld. And with people flogging to the app store in drones (rather than visiting it once to rarely if ever return), it appeared a less risky (and certainly more fashionable) move to leave it at that. Notably, Apple got the positioning piece (see above) right: even though it is a powerful gaming platform in its own right (anecdotally, the good folks at Firemint managed to string Real Racing to up to an impressive 82 fps), it never looked at this as a sole or even the main focus of the platform. There is a good reason why their already famous moniker says

there’s an app for that

rather than

there is a full 3D, 60+ fps, multi-player, high-end, Bluetooth and WiFi-enabled fighting game with dedicated combo mode for that.

And Mark Ollila, Nokia’s Director of X-Media Solutions and a games and general industry veteran, nails all of this down when he says that

One lesson is the complexities of offering rich games content on a global scale. […] How do you handle the billing, the local marketing intricacies and the type of gaming experiences that work in different markets? And what do consumers actually want – is it the high-end games with connected features that N-Gage was delivering, or a much broader catalogue?

At the heart of it is the conceptually different approach of monolithic, super-rich and highly integrated platform versus a more modular approach: in Apple’s app store ecosystem (or in Android’s for that matter), you can integrate most if not all of N-Gage’s features, too: multi-player gaming, communities, trial versions, etc. But you don’t have to. The former lacked flexibility, which made it susceptible to the nimbler, faster moves of a modular system.

Well then. It at least gives Nokia the opportunity to focus solely on building out the Ovi platform and fix the bugs it has been plagued with at the start. Nokia clearly feels the pains of the rapidly changing market place and it struggles to adapt swiftly (which is – and one should appreciate this – much harder when you are running a product portfolio that has a market share of well double your nearest competitor and stretches all the way from the most basic feature phones to the most advanced smart phones) but it has people that should be capable to turn it around. Not easy, mind you but they’re a mighty player that has shown its ability to innovate numerous times, never forget that.

More Fragmentation: Android & Motorola’s Motoblur

A new round of fragmentation looms. It is something I have been fearing for a while now: that OEM (and carriers) would make use of the open source of the likes of Android and LiMo to produce their very own flavour of apps. So after Vodafone’s 360 announcement (with customized LiMo storefronts, etc), Motorola announced so-called “signature apps” from a number of developers that are all delivered through Motorola’s new “Motoblur” user interface, which

is based on the Google-backed Android platform for mobile systems. Motorola [will] offer an additional SDK for its APIs beyond what is available for Android.

And then it said that

Over a period of time–we’re not there yet–we’ll allow the APIs to be available so people can develop many more applications than we can think of ourselves, but it’ll take us a little bit of time to mature ourselves to a place that we could open up APIs.

Ouch. An additional SDK. Which is not yet there yet. Whilst the Motoblur UI looks actually quite nice, this sounds suspiciously like another round of walled gardens, onerous internal and external QA, fragmentation and pretty much a fall back into the traps of the J2ME uber-customized world where one needs to support hundreds of devices for a commercial roll-out (with the trouble of course being that, all too often, that work meant that it would no longer be commercially very sensible). Oh dear…

It makes one want to call out for a quick advancement of HTML5 with Gears and all, so that one won’t need apps after all. The issue of connectivity and usability, etc would of course still be there. Such despair…

O2, Orange/T-Mobile, and now Vodafone: iPhone everywhere in the UK!

After the news broke that Orange will add the iPhone to its roster from just before Christmas, today we read that Vodafone UK will do the same, only a little later, some time in Q1/2010. Vodafone said that not having the iPhone was basically the reason for losing 200k customers in the last quarter alone. Vodafone had previously been shipping the device in 12 other territories.

With Orange and T-Mobile merging their UK operations, the new set-up which sees basically all large operators offering the device should make for some juicy deals. Analysts reckoned the contract tariff for to come down by £4-5 per month. Orange did not say anything specific but “indicated” that it would be cheaper than O2’s deals.

According to the article, Virgin Mobile (an MVNO that sails on the Vodafone network) is also “understood” to be desperate to secure the right to sell the phone. Happy days…

Oh Nokia, where art thou?

Nokia struck again, it seems. This time? No, not another multi-billion dollar acquisition such as Navteq but another tiny start-up, namely the “boutique” travel social network Dopplr, which the Finnish telecoms giant allegedly gobbled up for anywhere between €10-15m. Hm. Hm Hm…

Dopplr’s Business Case

Let’s see what Dopplr does (besides its co-founder [and angel investor] being an old Nokia hand): the idea is to share trips with friends so that a) people coincidentally going to the same place at the same time (“what??? you will be in Barcelona in the second week of February, too???”) will find each other and b) they can share cool and “unique” tips from other travelers. It is (was?) one of the group of location-aware social networks that have been and are still waiting to come out of cover.

Nokia’s Master Plan

The deal is great for the Dopplr guys who seem to have made a nice return and the pieces of the jigsaw on a very, very, very high level seem to make sense: Nokia is assembling a location-based empire. They acquired Navteq in what was Finland’s largest acquisition ever, they bought German location social network Plazes, and now Dopplr. And it now all comes together at Ovi Maps (which looks quite good!). Makes all sense, huh? The rationale was – arguably – to do to sat-nav systems what they did to (small) digital cameras: kill them and incorporate it into their phones (or multimedia devices). When Nokia moved to Carl-Zeiss lenses, mobile phone camera were basically on par with low- and mid-tier digital cameras. Why carry 2 devices if 1 will do the same job. Easy! And boy did it work!

So, let’s do the same with maps. And, more importantly perhaps, do not maps (and location-awareness in general) find a completely new way of justification in mobile phones, i.e. in devices that are, well, intrinsically mobile? Yes, it does. When Steve Jobs premiered the original iPhone, he famously ordered coffee from the nearest Starbucks, using a maps application. Simple, right? Wooing the masses but nothing much in it, right?
But! On the maps side, Nokia competes against Google Maps (this is what Jobs was using), which is free (if one leaves aside the probably not insignificant investment that will have gone into this service with its various extensions such as Streetview et al). It also has an open API and many, many people use this. It is embedded on the iPhone (Jobs again) and most people I know use it on their Blackberry because it is better than RIM’s own offering. A free download to most phones, Nokias included.

The Impact of (Fairly) Open Networks

Now, I never got these highly specialized things anyway. I find them way to complex to handle: when I am going on a business trip, I am normally much too busy to feed data in some travel network or other. And when I am going on a personal vacation, I am a) even busier and b) want to be left alone (normally). Oh, and did you see that Twitter plans something like this, too?
But even aside from this, when it comes to “being found”, all my friends (real and virtual) knew through my blog, through Twitter and Facebook that I was going to France this summer. Do I really need another, specialized service for this, over and above the ones that can provide that information and also everything else? In other words: does it make sense to try and hone a super-focused service when similar (if not identical) results can – and already are being – achieved through smart filters on networks that have somewhat of a head-start when it comes to active users? I mean, Facebook has more than 300m users, MySpace – even if it seems to be struggling a little lately – will have more than 150m. And then you have Twitter, Bebo, Hi5, Orkut, StudyVZ, etc, etc, etc. – that is more than Nokia sells all year.

Now, the existing players are adding geographical awareness as an additional feature to their services. I mean, even YouTube is doing it!

But the real point is: whoever uses one of these (say, when you are in Brazil, you use Orkut), there is a certain likelihood that your friends will, too. Otherwise, you would not be on it. Need more? I doubt it.
On top of that, it is – arguably – much easier to integrate a location-based function into a network that already has hundreds of millions of users (and I am not talking of hundreds of millions phone users because they only are potential users of any service that might come with the phone) than to build one. Nokia does certainly have a great starting point (it sells more devices per year than Facebook and Twitter users combined; see – old – numbers here) but they are not with Nokia because it provides such a great network but because their phones are good.

When it comes to services, it has become an issue of today’s mash-up world where access and resulting services go across a variety of – more often than not – open offerings rather than tight proprietary ones, and Nokia seems to be struggling of getting to grips with this. Some commentators compared it with Yahoo!‘s M&A swoop in order to try and grab back the love it lost to Google and others. Even if one isn’t so harsh, it seems obvious that the thought pattern behind Nokia’s thinking might be a little outdated. I stand to be corrected (and would love to be since Nokia has brought a lot of really great stuff to the world) but that is what is worrying me. So congratulations again to the Dopplr team again but, dear Nokia, for the time being I remain skeptical as to the commercial sense of it (and, yes, I appreciate that €10-15m is but a fly speck on your balance sheet if it fails…).

Page 5 of 15

Powered by WordPress & Theme by Anders Norén