The Carnival of the Mobilists is hosted this week over at “A Consuming Experience” and deals with handsets, learning, Amazon’s recent entry into mobile payments (on which I also blogged here) as well as an excellent post from Ajit Jaokar expanding on a talk he gave at CTIA (which I sadly missed). Go there, read it and become a better person… 😉 It’s here.
 A couple of weeks ago, I pondered Spotify’s impact on music business models and suggested that mobile may have a role to play in the monetization end of it (which is, unless you’re Twitter, an inherent part of a business model indeed). It didn’t take them long:
Today, the UK arm of 3 – always one of the more creative carriers – announced a handset (and not a bad one either) to be bundled with Spotify Premium (i.e. on the go and no ads): users will pay £99 up front, and then £35 a month for 24 months for a tariff including a Spotify Premium subscription covering both PC and mobile, 750 minutes voice calls, unlimited texts, data and Skype-to-Skype calls. Listen up: all bandwidth included. For a streaming service. Now we’re talking!
3 said that the Spotify Premium service was
worth £240
which suggests that they might want to stick to the £9.99 price point (which would surprise me). But then it is hard to tell which bit of such announcements is marketing and which actual price-setting for the sake of royalties and such like…
3 also said
that the deal with Spotify would extend to other products in the coming months, including 3’s mobile broadband service.
 Again, I am curious about the price point: the way it is, it would be a nice marketing deal for Spotify but it could be said that not much was going for taking exactly that offer vs just signing up as it is already. A little discounted however (with the difference paid for by 3’s marketing department) might change the ball game altogether…
It’s all good though: I for one am truly intrigued by the prospect of having more than 6 million tracks (equating to, what?, 6 terabyte or so of music) on my phone!
And one little thing on the side: it is – again – an app and not the mobile web that they choose – in spite of bandwidth apparently not being an issue at all. It is thus another argument for the superiority (for the time being) of apps over mobile web when it comes to UI and input constraints.
 So here’s something new: today, on 15 October 2009, is the global Blog Action Day. This year’s iteration is targeted to raise awareness to Climate Change. I would like to use the opportunity to alert everyone to the former UN Secretary General Kofi Annan’s appeal to fight climate change. As part of his “Time for Climate Justice” initiative, he teamed up with the good folks of Duran Duran (a mobile link after all: they were amongst the first artists with who I worked on activating mobile as a platform to enhance fan communication back in 2002!), Lily Allen, All American Rejects and countless others, etc to produce a new version of Midnight Oil’s “Beds are Burning” (it is a free and you can download from iTunes here) and produced a video to go with it. Download it, share it, watch it, act!
So, come on, overcome your fashionable cynicism, do something!
 Yesterday, I blogged about Motorola’s Motoblur UI, which adds an additional SDK for its specific APIs beyond the standard Android stacks. I reckoned that this might mean more fragmentation, which would push it a step closer to the nightmare that was/is J2ME.
I received two quick reactions to this: one reader commented that this was only bad if you wouldn’t have good tools and compilers. To him (@tederf), I would respond that, while it is certainly true that good tools reduce the friction, raise efficiencies and alleviate overall pain, the smallest common denominator is always just that. In my previous companies, we used to produce up to seven or eight different J2ME builds in order to maximise performance of our games on the huge spread of handsets. Could we have done with one build? Probably. Would the result have been great? Almost certainly not!
Anyway, the more interesting reaction came from the good folks at Motorola themselves. They reckoned (via Twitter; they are @motoblur) that:
with all due respect, I feel you’ve misunderstood motoblur, and android fragmentation concerns are a wee bit overblown.
Now, now. I offered them a guest post here in order to explain this further. I have unfortunately not yet had a response (which I take, applying Twitter attention spans, as lasting silence). But I still wanted to use the opportunity to elaborate a little more on this (and, no, I will not lament Moto’s lost opportunity to feature their wares on this humble site).
 To clarify a couple of things outright:
- I would be delighted would I be mistaken (and note that I am not a techie, so this is a distinct possibility!).
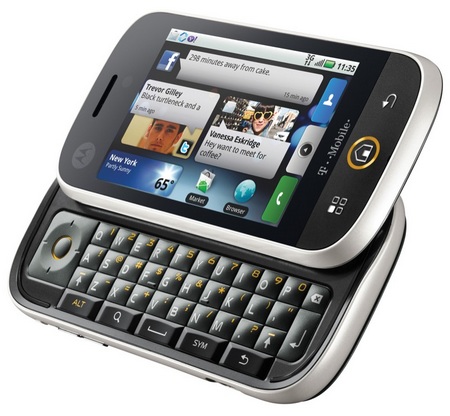
- I would be equally delighted would Motorola manage to regain some of its lost ground. The world clearly would be a better place with another strong manufacturer regaining old strengths (although maybe with better UI this time around – which Motoblur certainly seems to offer [see picture on the right of the Motorola CLIQ!).
But let’s go back to the general issue of Android fragmentation threats (the fact that I pointed this out – again – en cas de Moto is of course purely coincidental).
So let’s dive in: with open source software, there is always the intrinsic possibility that fragmentation will occur. Why do people customize it? Because they can! vendors, developers and operators that make up the Open Handset Alliance (which releases Android) can tweak is in whichever way they like (or “need” to) and for any number of reasons: to protect IP, to optimize performance on their network or for certain devices or simply because they feel they need some distinguishing factors, some degree of uniqueness. The result can be, however, as one analyst puts it that
there will be multiple flavors of Android, all of them incompatible with each other. That, in turn, necessitates different versions of each application or updates to accommodate the entire device ecosystem. On the whole, such activity negates the cost efficiencies inherent in the idea of a standard, open operating system, and potentially makes the Android Market a confusing place to shop for widgets.
And that’s what you call fragmentation. Interestingly, there were rumours that Google had made the Open Handset Alliance members sign “non-fragmentation agreements” but it seems that this is either not true or not enforceable.
Others point out that HTC, Samsung, Dell, Verizon, (may I add Motorola?) all have phones on the way that run on different software to the others. Reports of version conflicts, lack of backward compatibility, etc, etc. I mean, hell, there is even an “alternative” Android app store (with 223 apps as of tonight)… Sounds familiar?
Dear Motoblur, if it is different with your SDK, please enlighten us! I am sure I will not be the only one applauding!
Image Credit: http://www.visionmobile.com
Chetan Sharma’s blog Always On Real-Time Access is this week’s host for the Carnival of the Mobilists. This week’s edition features posts looking at mobile and social networking, mobile application development, 5 reasons why mobile VoIP has (so far?) failed, another iteration looking into the shortfalls of mobile advertising to date, a presentation on concepts and technologies behind real-time demand data, and last but not least – for all of us who weren’t there – a CTIA round-up. Lots of goodies, so go read it here.
 A new round of fragmentation looms. It is something I have been fearing for a while now: that OEM (and carriers) would make use of the open source of the likes of Android and LiMo to produce their very own flavour of apps. So after Vodafone’s 360 announcement (with customized LiMo storefronts, etc), Motorola announced so-called “signature apps” from a number of developers that are all delivered through Motorola’s new “Motoblur” user interface, which
is based on the Google-backed Android platform for mobile systems. Motorola [will] offer an additional SDK for its APIs beyond what is available for Android.
And then it said that
Over a period of time–we’re not there yet–we’ll allow the APIs to be available so people can develop many more applications than we can think of ourselves, but it’ll take us a little bit of time to mature ourselves to a place that we could open up APIs.
 Ouch. An additional SDK. Which is not yet there yet. Whilst the Motoblur UI looks actually quite nice, this sounds suspiciously like another round of walled gardens, onerous internal and external QA, fragmentation and pretty much a fall back into the traps of the J2ME uber-customized world where one needs to support hundreds of devices for a commercial roll-out (with the trouble of course being that, all too often, that work meant that it would no longer be commercially very sensible). Oh dear…
It makes one want to call out for a quick advancement of HTML5 with Gears and all, so that one won’t need apps after all. The issue of connectivity and usability, etc would of course still be there. Such despair…
 The United Nations’ agency for telecoms, ITU, has released a set of numbers on mobile and broadband penetration globally. There have been many times more mobile phones than fixed-line telephones on the planet for a while now but now this also applies to broadband connections: by the end of 2009, the ITU expects 600m mobile broadband subscriptions globally compared to only 500m for fixed-line equivalents.
This is not to say that all is good already. The divide between the so-called first and third worlds is immense: the broadband penetration in Europe is 20%, in Africa only 0.1%. And it is the latter where the exponential further growth of mobile (telephony and broadband) will lie then: the competition mobile networks have from fixed lines is much lower in territories with less legacy networks built. And in rural parts of Africa (and elsewhere), the cost of putting up the respective infrastructure makes the installation of fixed line networks simply untenable.
The cost of ICT spend represent a whopping 41% of an African average monthly income. In the Americas (average of North and South), this is c. 7% and in Europe just over 1%.
Here’s some other bits from the ITU’s facts and figures:
- 4.6bn estimated mobile subscribers by end of 2009.
- 25% of the world’s population uses the Internet.
- China has overtaken the US as the country with the biggest broadband subscriber base (but still has “only” 6.2% penetration rate on a subscription (as opposed to household) basis.
- Of the world’s population (6.9bn), 70.8% (or 4.9bn) have access to a TV at home (not equal to number of TV sets) and 27.3% (1.9bn) have access to a PC at home. By number of households, this looks as follows: 1.7bn households globally, 1.3bn of which have a TV and 600m a PC. The gap is expected to narrow quickly due to declining prices and ongoing convergence.
- The US accounts for 82.6% of all mobile broadband subscriptions in the Americas (North and South). In Asia and the Pacific, 70% of such subscriptions are in Japan and South Korea.
- The top 5 most highly developed ICT economies (listen up, Mr Scoble) are:
- Sweden,
- South Korea,
- Denmark,
- Netherlands, and
- Iceland
Japan ranks on # 12, the US ranks on # 17, Canada on # 19 and Russia on # 50.
The ITU provides some reports as downloads: The World in 2009 [PDF] as well as a statistical profile on the state of the information society in Africa [PDF].