Category: 1 Page 13 of 21

Oh Nokia, where art thou?

Nokia struck again, it seems. This time? No, not another multi-billion dollar acquisition such as Navteq but another tiny start-up, namely the “boutique” travel social network Dopplr, which the Finnish telecoms giant allegedly gobbled up for anywhere between €10-15m. Hm. Hm Hm…

Dopplr’s Business Case

Let’s see what Dopplr does (besides its co-founder [and angel investor] being an old Nokia hand): the idea is to share trips with friends so that a) people coincidentally going to the same place at the same time (“what??? you will be in Barcelona in the second week of February, too???”) will find each other and b) they can share cool and “unique” tips from other travelers. It is (was?) one of the group of location-aware social networks that have been and are still waiting to come out of cover.

Nokia’s Master Plan

The deal is great for the Dopplr guys who seem to have made a nice return and the pieces of the jigsaw on a very, very, very high level seem to make sense: Nokia is assembling a location-based empire. They acquired Navteq in what was Finland’s largest acquisition ever, they bought German location social network Plazes, and now Dopplr. And it now all comes together at Ovi Maps (which looks quite good!). Makes all sense, huh? The rationale was – arguably – to do to sat-nav systems what they did to (small) digital cameras: kill them and incorporate it into their phones (or multimedia devices). When Nokia moved to Carl-Zeiss lenses, mobile phone camera were basically on par with low- and mid-tier digital cameras. Why carry 2 devices if 1 will do the same job. Easy! And boy did it work!

So, let’s do the same with maps. And, more importantly perhaps, do not maps (and location-awareness in general) find a completely new way of justification in mobile phones, i.e. in devices that are, well, intrinsically mobile? Yes, it does. When Steve Jobs premiered the original iPhone, he famously ordered coffee from the nearest Starbucks, using a maps application. Simple, right? Wooing the masses but nothing much in it, right?
But! On the maps side, Nokia competes against Google Maps (this is what Jobs was using), which is free (if one leaves aside the probably not insignificant investment that will have gone into this service with its various extensions such as Streetview et al). It also has an open API and many, many people use this. It is embedded on the iPhone (Jobs again) and most people I know use it on their Blackberry because it is better than RIM’s own offering. A free download to most phones, Nokias included.

The Impact of (Fairly) Open Networks

Now, I never got these highly specialized things anyway. I find them way to complex to handle: when I am going on a business trip, I am normally much too busy to feed data in some travel network or other. And when I am going on a personal vacation, I am a) even busier and b) want to be left alone (normally). Oh, and did you see that Twitter plans something like this, too?
But even aside from this, when it comes to “being found”, all my friends (real and virtual) knew through my blog, through Twitter and Facebook that I was going to France this summer. Do I really need another, specialized service for this, over and above the ones that can provide that information and also everything else? In other words: does it make sense to try and hone a super-focused service when similar (if not identical) results can – and already are being – achieved through smart filters on networks that have somewhat of a head-start when it comes to active users? I mean, Facebook has more than 300m users, MySpace – even if it seems to be struggling a little lately – will have more than 150m. And then you have Twitter, Bebo, Hi5, Orkut, StudyVZ, etc, etc, etc. – that is more than Nokia sells all year.

Now, the existing players are adding geographical awareness as an additional feature to their services. I mean, even YouTube is doing it!

But the real point is: whoever uses one of these (say, when you are in Brazil, you use Orkut), there is a certain likelihood that your friends will, too. Otherwise, you would not be on it. Need more? I doubt it.
On top of that, it is – arguably – much easier to integrate a location-based function into a network that already has hundreds of millions of users (and I am not talking of hundreds of millions phone users because they only are potential users of any service that might come with the phone) than to build one. Nokia does certainly have a great starting point (it sells more devices per year than Facebook and Twitter users combined; see – old – numbers here) but they are not with Nokia because it provides such a great network but because their phones are good.

When it comes to services, it has become an issue of today’s mash-up world where access and resulting services go across a variety of – more often than not – open offerings rather than tight proprietary ones, and Nokia seems to be struggling of getting to grips with this. Some commentators compared it with Yahoo!‘s M&A swoop in order to try and grab back the love it lost to Google and others. Even if one isn’t so harsh, it seems obvious that the thought pattern behind Nokia’s thinking might be a little outdated. I stand to be corrected (and would love to be since Nokia has brought a lot of really great stuff to the world) but that is what is worrying me. So congratulations again to the Dopplr team again but, dear Nokia, for the time being I remain skeptical as to the commercial sense of it (and, yes, I appreciate that €10-15m is but a fly speck on your balance sheet if it fails…).
US Mobile Advertising Snapshot August 2009

I had covered the monthly Scorecard for Mobile Advertising Reach and Targeting (what a mouthful) from Millenial Media before (see here for the May figures), so here’s an update on this (and note that these are all US-only figures). The firm covers just under 50m users, which seemingly represents 79% of the mobile web (but only 11 of the top 25 sites as per Nielsen). However, it should provide for a very decent overview of the state of advertising on the mobile web. So here it goes:

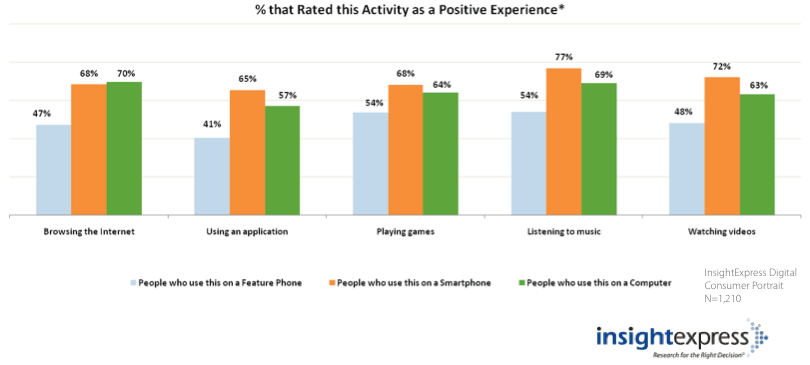
The first really noteworthy piece has not actually anything to do with advertising but with user satisfaction: would you actually have thought that users enjoy most things more when done on their smartphone than on their computer, including playing games and watching video? The computer only leads (and by a meager 2% higher rates) for web browsing (70% vs 68% on smartphones). Wow! Here’s the graph:

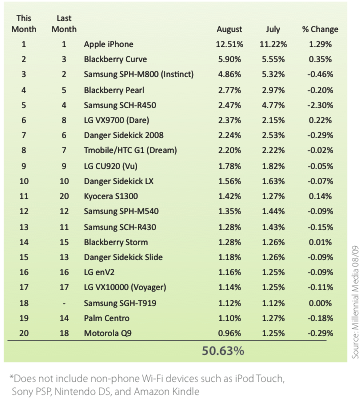
This is very encouraging and probably also owed to the market leader when it comes to ad impressions received on a mobile device, which is – moan – the iPhone of course. The last snapshot I covered had the Samsung Instinct in front but this has slipped back to a still respectable #3 now. Blackberry’s Curve takes 2nd place. Here’s the top 20 list:

Compared to their old format, Millenial Media is no longer spitting out a comprehensive chart showing the CPEU (cost per engaged user) per demographic/targeting method. They have adopted their proprietary “Mydas” tool, which appears to enable them to mix things together in an optimal way. It is understandable since this is their business but the look under the bonnet was great. Alas, no more. So here’s what we still learn:

  • iPhone and iPod Touch impressions are still growing with double-digit numbers (month on month they grew 68% in June, 29% in July and 15% in August).
  • Average monthly page views is 111 (up 5 views).
  • The top 20 phones (see above) make for 50.63% of all device traffic, which is drop by nearly 4% compared to the previous month.
  • A whopping 26.15% of all ad impressions were achieved on devices on a WiFi connection (bandwidth is king!).
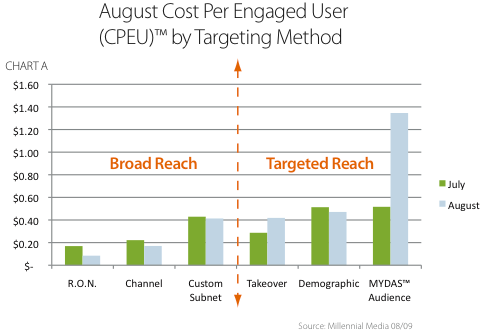
  • Cost per Engaged User for audience targeting increased very significantly from ¢52 to $1.35, which is owing to Millenial’s aforementioned Mydas thing (or so they say). Most CPEU rates decreased however. Here’s the chart:

So what does it teach us? Well, due to the new format unfortunately less than previously… but then: I’d love to have that Mydas touch… 😉

EA Mobile, Namco Bandai and the State of Carrier Decks

After many rumours and ominous statements that it was “reviewing its activities” Namco Bandai confirmed today that EA Mobile will thenceforth act as its distributor for mobile games outside the US and outside any app store.
After Taito and Eidos, EA Mobile just gobbled up another major distribution deal and the exodus from J2ME games distributed via carriers continues. It also means that EA’s dominance over the operator decks has just increased a little more yet again. It had estimated (back in June) that its 2009 mobile revenues would reach $185m (although this arguably includes Apple’s and other people’s app stores as well as embeds).

What is worrying is that this cements the oligopoly of games distribution in all major markets. EA Mobile, Gameloft occupy the top 2 slots very comfortably with Glu an equally comfortable but distant third. I-Play, Digital Chocolate, Real and Connect 2 Media are fighting for place and Xendex, Handy Games and a few others seek (and sometimes find) niches to prosper. THQ Wireless, Vivendi Games Mobile have departed. Player X found a new home under the mighty wings of Zed. And then? If the above companies all manage to maintain a healthy business, this might be enough; there are silverback gorillas in every market segment. If not though, this might become a doomed sub-sector; the limelight would then be on the (failed) ecosystem operators tried to build: overly fragmented with everyone of them wanting it just so and just their way rather than agreeing on a largely unified structure and processes pressed margins from a system that has been tough from the outset (handset fragmentation and international spread mean fairly high cost per capita anyway).
The accumulation of external properties arguably also mean that EA will need to run a business that is almost a combination of a publisher and an aggregator (with its very own challenges). The issue of shelf position (will they give Tetris and the Sims undue preference over Space Invaders, Pac-Man and Cooking Mama?), the commercials of their own deals (they anecdotally paid Hasbro a handsome sum), and the generally dominant position will all come into play and it is inconceivable (well, is it really?) that their partners will continue to play ball.

It might of course only be a brief interregnum on the way to an app store world. Smartphones are very much on the rise and, in that world, such stores seem to rule. Apple has taken the lead, Android followed suit and new stores are springing up almost by the day, which also includes operator-led ones: Orange already has one, Verizon Wireless has announced one (mobile web-based) and so has Vodafone (which might actually be bigger than Apples) as well as many others. The OEM all do the same (even though some carriers want to disallow them): Nokia Ovi, Blackberry App World, Sony Ericsson, LG, Samsung, you name them, they have it. The question of course is if that might mean the same thing all over again: will they again want it all just so? Will they again have it just their way so that a user would have the unique flavour of operator X on handset Y in this unique way, meaning that – again – thousands of SKUs would be required to service them? Groundhog Day? I hope not!
Image credit: http://www.antitrustreview.com/files/2007/07/files51lsaydhrsl.-ss500-.jpg

Carnival of the Mobilists #192

The 192nd iteration of the Carnival of the Mobilists is under way. This week’s edition is hosted by C Enrique Ortiz on his About Mobility blog and features an overview of Opera Mini 5, a background story on app stores (juicy: written by a Qualcomm exec), some stuff on mobile learning and, last but not least, my own “little” contribution on mobile’s role in the transformation of the music business (which also received a “favourite of the week” note; thanks C Enrique!).

Check it out, it is well worth a read! You’ll find it here.

Mobile to Rescue Music Business?!

It seems to be music week this week: Apple running its somewhat anticlimactic “It’s only Rock’n’Roll” event today, lots of folks pondering Spotify Mobile and now this: the good folks at Forrester Research have released an interesting report entitled “Music Release Windows: The Product Innovation That The Music Business Can’t Do Without”. This is some statement.
The Old Model is Broken

Forrester was kind enough to let me have a glance at the report, so let me dive into its revelations and the underlying rationales, which starts off with looking at the broken model of the industry: in (latter part of) the 20th century, the music industry was mainly fueled by record sales (first vinyl, then CD). With the introduction of digital media and, in particular, ubiquitous broadband connectivity in many parts of the world, it shifted to digital downloads. Unfortunately, it mainly shifted for downloads that people did not pay for. iTunes has only taken a piece of the action. And iTunes’ ¢99 per song model has then contributed to people no longer buying whole albums but only the songs they like most, which somewhat squashes profitability.
Live events, etc used to be a support for record sales. They have recently become the biggest revenue generator for some recording artists (as well as for some labels, at least if they managed to conclude so-called 360-deals with artists) but they cannot alone make up for the shortfall. On top of all that, people like my 14-year-old son use a plethora of services (Spotify, Last.FM, YouTube and probably dozens more of which I do not know) to quench their thirst for music.

Change the Product, not the Business Model

The researchers suggest to re-think the product offering in order to engage the fan more holistically: leverage diverse assets through those maligned 360 deals: they might “feel” a bit tight around the hips but the opportunities are immense: labels and (capable) artist management can create a very rich offering of diverse content. This then ties in into step #2, which sees the industry moving away from (or rather beyond) the classic album model where an artists would release one album per year (or so) and sustain the buzz in promotion thereof (and in between) with concerts, interviews, singles and EPs. With digital distribution, there is no need for that (an album on CD might be maintained as one part of the mix however): one can produce a continual stream of creative products from the artist. This will help build sustainable and longer-term relationships with fans.

The final piece is – put simplistically – the introduction of release windows similar to what the film industry is doing for decades: releases are structured successively with higher product (read: better monetizable) tiers coming first. It is re-vamping a trusty old model though: you want it first and exclusive, you pay more.

The bottom line is – oh, the bliss of buzzwords – the 4 C’s, which are content, convenience, cost and community: The higher the cost, the greater the convenience and the better the choice of content. The authors basically plead a re-introduction of scarcity in order to re-build the perceived value. Convenience ranks above content in terms of the creation of value: and this is where mobile plays a role: it is always with the user, it is always on, it is readily accessible (at least the new generation of phones is). It is arguably why services like Spotify are believed to be a valid revenue stream for labels, at least on mobile…

Community is the Glue

Is community just thrown in for good measure? No, of course not. According to Forrester, “Community enhances social value.” It is the glue that will be the key differentiator from piracy (or so they hope): the thinking is that a sense of community will build some sort of moral cohesion (another C). Here though, Forrester tails off a little. It says:

“Social functionality should be deployed right across the hierarchy.”

Nothing wrong, you say? No, it is not. However, “deploying functionality” is way short of what is needed to build social value. What makes a community? Emphatic engagement with fans, not a set of tools that sits somewhere on the various sites and offerings being operated by some far-away call center. Whilst the principle is right, the suggested execution remains a little shallow. Forums & networks is all they have to offer. Hm. Everyone has them already, so will this work?
The principle does work, I believe, However, the execution is much, much more complex than the analysts reveal. Here, one can make or break this.

Release Windows

The analysts suggest that a release should be tiered by windows: start with a preview, then go into the mainstream for-pay channels (2-3 weeks delayed) and finally release to “free-to-air” (6 weeks delay). The premier window is suggested to being the one where incremental value can be unlocked: first releases, premium value-added content (and no DRM!), etc; users only get this if they pay. Elegant packaging and programming is crucial to convince people of the richness of this. Then they will not defect to P2P sites. CD releases remain in the mainstream window and then, finally after six long weeks, the Spotifys of this world will be able to get it through their ad-supported model, TDC Play, the Danish flat-rate all-you-can-eat model that generated more than 100m downloads in 15 months would be able to add it to their package, etc.

Mobile is in the premium tier (with very few others): Forrester believes that carriers’ and OEM’s efforts, investment and – last but certainly not least – billing relationships merit this. I would suggest that the eye-opener ringtone where one could charge huge premiums for monophonic (!) 20-second-loops would contribute to this conviction, too.
In the “modern world” with smartphones and flat rate data plans, a lot of it of course hinges on how such services tie in with a) the handset (app vs. mobile web), b) the provider(s), namely labels, artists, operators, handset manufacturers, other (mobile) distributors as well as iTunes, and c) the users, i.e. will they adopt it or will they defect to the (free) web side of things after all. The crackdown on piracy in many countries will have something of a disciplinary effect but the jury on this is probably still out.

Is that It?

There must be more in order to create compelling services and products. Otherwise, I cannot see people doing it in sufficient numbers. It could be seen online with Spotify where, anecdotally, only 17,000 in the UK have signed up to the premium service; I cannot believe that the premium music market should be limited to that. The analysts suggest the creation of

“truly 21st century products […] blend[ing] interactivity, multimedia, multi-platform, convenience and social to create something totally new.”

That sounds awesome but how do you create it? The starting point needs to be the relationship between artist and fan. I have long held that this bond is more than actual musical tastes; it is a lifestyle decision, which is why fans crave to belong to “their” artists’ circles. As early as 2002, a “Britney Spears Mobile Fanclub” was successfully running, and that did not even involve her label! What it did involve though was access (or at least the promise thereof) to Britney (who was, at that time, arguably one of the biggest recording artists in the world). The service combined text (real-time backstage reports from Britney herself!), live concerts, editorial, merchandise, and special promotions to create a rich and comprehensive experience around the artist. And this at a time when a ringtones were just on the rise and premium SMS not widely available! The principle works! It does take however (and that’s a big IF) active involvement of a complex ecosystem of artists, management, labels, merchandise firms, media, etc.
The new generation of artists is of course significantly more tech-savvy (see e.g. upcoming singer Remi Nichole‘s video blogs and tweets): one sees a much higher willingness to participate actively and – even more importantly – authenticly in engaging the fans (“audience” is probably an overcome term in this respect). This can work, and on mobile it can work as a revenue generator, too! But the core is the revised approach to the people (and this is not limited to the music industry): they are not sheep that want to be exploited; if you treat them that way, they bolt. Treat them honestly, fairly, transparently, and you have at least a fighting chance!

Carnival of the Mobilists #191

This week, the Carnival of the Mobilists is hosted by Phil Barrett on his blog “Burning the Beacon” (I like the title). He gives us the heads-up on posts covering things (seemingly) mundane as SIM cards, a look at augmented reality (also check my post on this here), mobile learning and on how to connect with young users in today’s world. Oh, and speaking of today’s world, he also features a post pondering the implication of technology in our lives. Go on then, head over here and read it!

Judi Dench Movie Launches on Mobile First!

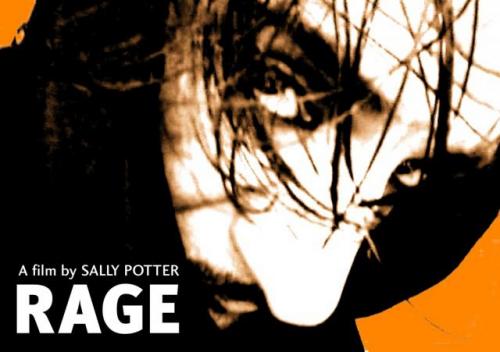
On today’s is a stunningly beautiful Indian summer morning in England’s North-West and I have been indulging in the Guardian‘s weekend supplement. One of the features was an interview with Dame Judi Dench, the iconic actress of Shakespearean as well as James Bondian fame. It is well worth a read but the little bit that caught my attention for the sake of this blog was to be found at the very end: Dench’s upcoming movie (Jude Law and a few others star, too), “Rage”, a project with arthouse director Sally Potter, will see its world premiere not in some swish viewing room or cinema in SoHo but on mobile phones. The prosaic announcement read:

Rage premieres on mobile phones on 21 September and in cinemas on 24 September. For details, go to ragemovie.com.

And that was that.

I find it noteworthy not only that it would happen at all but also that it appears to be somewhat normal, so that no one would actually bother to point it out specifically. Sometimes, progress moves in indiscernible little steps that can happen on stunningly beautiful mornings. This is one of them.

Page 13 of 21

Powered by WordPress & Theme by Anders Norén