
 Nokia’s N-Gage game service has just been declared dead, well dying anyway. always been a concept that has under-delivered painfully. In its first iteration, the device, it was a gutsy but maybe not entirely thought-through attempt to combine phone and dedicated handheld gaming device (it was always going to lose as one simply looked outright silly even when putting the thing towards ones ear to make a call – even when stood at a Star Trek convention, and that is telling). The “new” iteration, the software platform, struggled to take off. Nokia tried mightily to produce showcases demonstrating the superior gaming abilities of the platform compared to “regular” feature and smart phones but the efforts were thwarted from a number of angles:
Too expensive
It was a costly affair to deliver a game optimized for the N-Gage platform. When there is no proven distribution model that can guarantee decent returns, there would always be limited uptake from developers and publishers.
Too small a niche
N-Gage was always geared towards dedicated gamers. All marketing was directed this way, the positioning was distinctly high-end, no non-game applications were shown (or even contemplated, I guess). The power of the platform thus was funneled into a niche of a niche, i.e. high-end gaming. I would suggest that one could as easily have positioned it as a powerful media platform full stop. One that allows for beautiful execution of any number of simple or complex apps (and a game is basically “only” one app category).
There’s an app for that
 The iPhone then was arguably the final punch. In spite of developer frustrations growing over discoverability within this pile of 100,000+ apps, the platform has spurned exceptional games galore, and not only casual ones either. Real Racing is as punchy a racing title as one will ever get one on a handheld. And with people flogging to the app store in drones (rather than visiting it once to rarely if ever return), it appeared a less risky (and certainly more fashionable) move to leave it at that. Notably, Apple got the positioning piece (see above) right: even though it is a powerful gaming platform in its own right (anecdotally, the good folks at Firemint managed to string Real Racing to up to an impressive 82 fps), it never looked at this as a sole or even the main focus of the platform. There is a good reason why their already famous moniker says
there’s an app for that
rather than
there is a full 3D, 60+ fps, multi-player, high-end, Bluetooth and WiFi-enabled fighting game with dedicated combo mode for that.
And Mark Ollila, Nokia’s Director of X-Media Solutions and a games and general industry veteran, nails all of this down when he says that
One lesson is the complexities of offering rich games content on a global scale. […] How do you handle the billing, the local marketing intricacies and the type of gaming experiences that work in different markets? And what do consumers actually want – is it the high-end games with connected features that N-Gage was delivering, or a much broader catalogue?
At the heart of it is the conceptually different approach of monolithic, super-rich and highly integrated platform versus a more modular approach: in Apple’s app store ecosystem (or in Android’s for that matter), you can integrate most if not all of N-Gage’s features, too: multi-player gaming, communities, trial versions, etc. But you don’t have to. The former lacked flexibility, which made it susceptible to the nimbler, faster moves of a modular system.
 Well then. It at least gives Nokia the opportunity to focus solely on building out the Ovi platform and fix the bugs it has been plagued with at the start. Nokia clearly feels the pains of the rapidly changing market place and it struggles to adapt swiftly (which is – and one should appreciate this – much harder when you are running a product portfolio that has a market share of well double your nearest competitor and stretches all the way from the most basic feature phones to the most advanced smart phones) but it has people that should be capable to turn it around. Not easy, mind you but they’re a mighty player that has shown its ability to innovate numerous times, never forget that.
 In the last two days, two forecasts informed us about the value of the mobile app market in – convenient as ever – the distant future that is 2013. US analyst firm
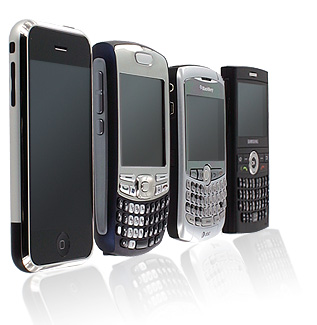 If we estimate a 20% growth year-on-year for smartphones (vs. 5% for the overall phone market, which seems to be loosely in line with the general dynamic), then we would end up with something like 900m smartphones by 2013. Yankee Group predicts that smartphones in the US will quadruple by then (from 40m to 160m) and does not seem to be very far off. Wireless Expertise thinks the global number will be 1.6bn, which again, might not be that far off.
 Now, I am not predicting total doom and gloom, in the contrary. I do think that Apple’s wake-up call has brought a much-needed new wave of innovation and I also believe that this will be successfully incorporated by some carriers and OEMs. But by all of them? Not very likely.
 Nokia struck again,
 But! On the maps side, Nokia competes against
 But even aside from this, when it comes to “being found”, all my friends (real and virtual) knew through my blog, through Twitter and Facebook that I was going to
 On top of that, it is – arguably – much easier to integrate a location-based function into a network that already has hundreds of millions of users (and I am not talking of hundreds of millions phone users because they only are potential users of any service that might come with the phone) than to build one. Nokia does certainly have a great starting point (it sells more devices per year than Facebook and Twitter users combined; see – old –
 After many rumours and ominous statements that it was “reviewing its activities” Namco Bandai
 What is worrying is that this cements the oligopoly of games distribution in all major markets. EA Mobile, Gameloft occupy the top 2 slots very comfortably with Glu an equally comfortable but distant third. I-Play, Digital Chocolate, Real and Connect 2 Media are fighting for place and Xendex, Handy Games and a few others seek (and sometimes find) niches to prosper. THQ Wireless, Vivendi Games Mobile have departed. Player X found a new home under the mighty wings of Zed. And then? If the above companies all manage to maintain a healthy business, this might be enough; there are silverback gorillas in every market segment. If not though, this might become a
 It might of course only be a brief interregnum on the way to an app store world.
 Nokia has
 Mobile advertising firm
 On GetJar’s side, I wonder if this is the one of the first steps into a new direction (Sony Ericsson was not the first app store deal they signed;