Tag: mobile games Page 8 of 17

Glu Mobile: You only live Twice (or Thrice)

After Greg Ballard’s announced and Jill Braff’s fairly sudden exits and the persisting rumours of financial frailty, many were waiting for Glu Mobile to fall.

However, at least in revenue terms, they seem to be doing OK: according to reports, Deloitte has put them at #129 in the fastest-growing US technology firms in their “Technology 500” list. The results, alas, are based

on fiscal reports between 2004-2008, during which time Glu grew by 1,000 per cent.

All good but let us remind ourselves what happened in those years: Glu acquired Macrospace (which was founded by Kristian Segerstrale, now of Playfish fame), iPhone, Superscape, MIG (did I forget anyone?). They went public, splashed out on licenses (much to the dismay of competitors who often felt priced out of the market) and only just managed to achieve positive cash-flow in Q2/2009 (i.e. not in the period covered by Deloitte and on decreasing revenues and with negative US-GAAP results).

What does it tell us then? That this strategy worked in terms of revenue growth? Yes, certainly. And I have often paid tribute to that. That it is a good company in terms of putting its working capital to good use? This is – although I truly and sincerely wish them really well – at best doubtful. What more? Ah, well, that Deloitte’s Technology 500 list is probably as trustworthy as the banks they audited… Ouch, did I just say that?

The Future of Advertising is in Engagement!

A lot is being said about mobile marketing, mobile advertising, capturing “consumer’s” imagination (if not only their eyeballs). And everyone says: “yes, I get that, social, mobile, always-on, always with them, cool!” Online ad spend outstrips TV already (at least in the UK), and mobile is arguably the next big thing; it is so much cooler, too: personal, accessible, always-on!).

So how do you execute? Banner ads? Text ads? Virals? “Ah, yes, virals are cool, I heard about them!”

There’s a busload full of mobile advertising networks out there, blind, premium blind, premium (check here for a great overview). And what do they do? Well, banner ads, text ads, the usual. Does it work? Anecdotally, sort of… Most developers and publishers I know that engage in this sort of activity make their money in two ways: either they are being commissioned by an advertiser to do it (good because you’re being paid!) or they use it as complementary (sic!) revenue; on a stand-alone basis, it would not feed them.

Why is the conversion not soaring? After all, mobile allows for unprecedented targeting (IF you do it. See here how not to do it): users have their phones always with them, it is always on, you can fall back on historical behaviours, etc, etc.

I would posit that it is because most advertisers still think of it in terms of consumers: beings that sit on the other (sic!) end of the message and who consume whatever I, advertiser, want to tell them. It is not, alas, true engagement, and this is where arguably the future lies.

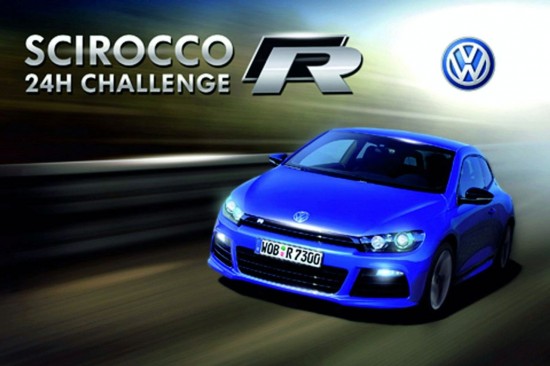
So how do you engage? Many options. A good one is by being sincere (Zappos, the online shoe retailer that was recently acquired by Amazon, is a great example). Another one is by engaging rather than preaching. Not so easily done with banners. Easier done with something more interactive. Such as – an example – games and apps. On Apple’s app store, there are some great successes for this type of thing: German car manufacturers seem to be good at this! Audi did one, German developer Fishlabs did a couple of games for Volkswagen, Artificial Life for BMW, and then there is Waterslide Extreme, which is basically a Barclaycard ad (and badly executed: they could so easily have accommodated the RFID function, which the original cinema and TV ad is meant to promote; alas, they ignored it!) which despite its shortfalls was incredibly successful. But these are exceptions to what I think might well become the rule. On the app side, there are e.g. Pizza Hut and Gap that were recently featured (for free!) in Apple ads. Wow!

It seems obvious when you think about it: games truly engage (users – not consumers! – interact with them actively) and they can do so in a much more subtle manner (less invasive). At the same time, the user (not: consumer) spends a lot more time with the brand than with a banner ad.

It is, alas, a space of unknown dangers and unprecedented adventure: never-before seen creatures (scil. formats) and strange folks (scil. developers) roam weird landscapes (scil. mobile platforms). This is how brands and their agencies often experience mobile. They "get" it, don’t get me wrong but they are still fairly unfamiliar with it. And because the big pots of gold sit with the brands and they don’t want to risk cutting access, they’ll rather (and rather too often) stick with what they perceive as the trusted old paths. It’s not so good then that the freshest fruit grows on the trees in this new land and no longer in the wastelands of banner ads…

Watch this space then. It will only be a question of time (I hope) before we’ll be seeing a new wave of non-intrusive, interactive, fun brand engagement. And games and apps will lead the way!

Mobile Browser-Based Flash Games?

Today, I read a press release from UK firm MoMac who announced the launch of a browser-based games platform, which uses Flash Lite. I had been looking at the use of Flash Lite for mobile gaming quite a while ago (2 years back in fact; see here and here). The front-runners on this (not browser-based but downloadable) was Mobitween, a French company that was bought by Zed last year. Back in 2008, the estimated install base of Flash Lite on mobile phones was already approaching half a billion, so just ever so slightly more than there are e.g. iPhones. In principle, all good.

But where did it go from there? uGenGames, the company’s original user-generated games site, seems to be stuck where it was back then. There is still the showcase of mobiGamz, a Flash-Lite-based gaming portal on Verizon Wireless. But otherwise? Nothing much…

So MoMac will do it in the browser then. I don’t think it makes that much of a difference but, given my early enthusiasm, wondered where the pitfalls (of which there apparently are some; otherwise it would have taken off more forcefully) might be. So where then?

I have argued in the interim the advantages of applications vs mobile web, and this still stands: apps often will give better usability and navigation tailored to the input constraints of (small) handsets when compared to browser-based solutions.

Discoverability might be another – albeit perhaps short-term – constraint: people are not (yet!?) used to looking for games (or other “applications”) on the web. That is arguably one reason of the huge success of the app store: it does what it says on the tin and it is very easy to discover.

Billing would be the third big differentiator: Apple managed what probably only a brand of Apple’s power can command, namely that people happily and without second thoughts sign up with credit cards and all via iTunes. To replicate this somewhere on the open seas of the wide web is almost certainly wishful thinking at best. The only other companies who have as easy a billing interface are the carriers who will almost always be more control-minded than independent service providers might wish for. MoMac claims that

the first casual games portal to go live on major MNO’s in October

and that might change things in this department a little. However, it will arguably take a few of those major MNOs in order to make it worthwhile for developers to address the platform.

A fourth point – and this is following from the above – is content. MoMac seems a little light on this side. It claims the availability of 30 games through its partner Booster Media and, with no disrespect (!), they do not seem to have the most compelling stuff available. This of course is nothing that comes with the concept but perhaps with the (current) offering, the announcement of which I believe might actually have come a little early because of this.

Anyway: the principle is (still) great, and I really wish them all the very best. Keep me up to date, guys; I’d love to publish a retraction of my take here…

App Bonanza or Analyst Bonanza?

In the last two days, two forecasts informed us about the value of the mobile app market in – convenient as ever – the distant future that is 2013. US analyst firm Yankee Group predicts the US app mobile market to be worth $4.2bn by then. Today, British analyst Wireless Expertise (run by former Netsize exec Anuj Kanna) topped this easily by predicting the (global) app market size to be $16.6bn by that time (free copy of the report here).

I can hear your moans…

However, let’s have a look at the numbers then, shall we? At the end of 2008, there were 4.1bn mobile phones in the market. Because apps tend to thrive most on smartphones (and the analysts seem to thrive on them, too), let’s have a look at that sub-sector. I would estimate the smartphone share to being somewhat under 10% (Symbian claims c. 250m devices in market, Apple has some 30-odd million, so RIM, Windows Mobile, Android, Palm, etc should probably be OK with the balance of some 100m). In Europe and the US, the share is much larger but in the big volume markets China and India it is bound to be much smaller, at least for the time being. Global smartphone shipments in 2008 were around 140m.
If we estimate a 20% growth year-on-year for smartphones (vs. 5% for the overall phone market, which seems to be loosely in line with the general dynamic), then we would end up with something like 900m smartphones by 2013. Yankee Group predicts that smartphones in the US will quadruple by then (from 40m to 160m) and does not seem to be very far off. Wireless Expertise thinks the global number will be 1.6bn, which again, might not be that far off.

The question is however if people will really download this much stuff: Yankee Group predicts that the actual value of the market will rise 10-fold and that the average price point of an app will be $2.37. Why that is so, you ask? Well, pay $495 and you will know; I don’t…

Now, the good folks of Wireless Expertise see the thing quadrupling until 2013. They do, however, count “ordinary” mobile games as they are being sold through carriers amongst the apps, which means that their starting point is higher, namely $4.6bn in 2009, so they’re looking at this quadrupling. They raise some smart points on app stores and how they (well, it) changed the way users access and consume content, how carriers will need to look for alternatives to increasingly commoditized voice and messaging propositions, etc. But why there should be a 400% rise in e.g. traditional J2ME mobile games remains – whilst it would be wonderful – pretty much in the dark.

Talking of J2ME and feature phones: I do not know how they are being woven into the equation but there would certainly be a wide field for any self-respecting crystal-ball-reader here: on the one hand, app consumption on such devices has traditionally been fairly shabby but, on the other hand, this could well change if connectivity, bandwidth, UI and the right price plans would come together to offer a compelling mobile web solution. So then apps would need to be translated into widgets or something like that. Would users then pay for them? Don’t know. Or would it be the “Freemium” model according to which “Free gets you to a place where you can ask to paid?”

The challenge of these reports is their “simplified” assumptions: if only one of them fails, you go “oops”, and your prediction is halved (or worse). On Wireless Expertise’s case, this is particularly clear: their assumption is that there will be a dual strategy of (presumably OEM-driven app stores) and mobile web-based widget stores. Now, they further assume that Ovi, Windows Market, etc will all be as successful as Apple’s App Store. By early (anecdotal) data, this could not be further from the truth (see here for what that may mean). Nokia in particular struggles to get its head around a viable and compelling media strategy (cf. here and here). And hence the beautiful hockey stick would actually fall flat on its face.
Now, I am not predicting total doom and gloom, in the contrary. I do think that Apple’s wake-up call has brought a much-needed new wave of innovation and I also believe that this will be successfully incorporated by some carriers and OEMs. But by all of them? Not very likely.

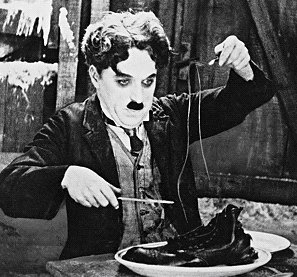
And so we see: the reports are a touch on the optimistic side when it comes to volumes and assumptions. But, hey, that’s their job, I guess, and after all they have at least dropped their masks now: Yankee Group call it fairly openly a “gold rush”. And what happens then we had been shown a long time ago: you end up eating your shoelaces. So maybe this is less of an app bonanza and more of an analyst bonanza then…
EA Mobile, Namco Bandai and the State of Carrier Decks

After many rumours and ominous statements that it was “reviewing its activities” Namco Bandai confirmed today that EA Mobile will thenceforth act as its distributor for mobile games outside the US and outside any app store.
After Taito and Eidos, EA Mobile just gobbled up another major distribution deal and the exodus from J2ME games distributed via carriers continues. It also means that EA’s dominance over the operator decks has just increased a little more yet again. It had estimated (back in June) that its 2009 mobile revenues would reach $185m (although this arguably includes Apple’s and other people’s app stores as well as embeds).

What is worrying is that this cements the oligopoly of games distribution in all major markets. EA Mobile, Gameloft occupy the top 2 slots very comfortably with Glu an equally comfortable but distant third. I-Play, Digital Chocolate, Real and Connect 2 Media are fighting for place and Xendex, Handy Games and a few others seek (and sometimes find) niches to prosper. THQ Wireless, Vivendi Games Mobile have departed. Player X found a new home under the mighty wings of Zed. And then? If the above companies all manage to maintain a healthy business, this might be enough; there are silverback gorillas in every market segment. If not though, this might become a doomed sub-sector; the limelight would then be on the (failed) ecosystem operators tried to build: overly fragmented with everyone of them wanting it just so and just their way rather than agreeing on a largely unified structure and processes pressed margins from a system that has been tough from the outset (handset fragmentation and international spread mean fairly high cost per capita anyway).
The accumulation of external properties arguably also mean that EA will need to run a business that is almost a combination of a publisher and an aggregator (with its very own challenges). The issue of shelf position (will they give Tetris and the Sims undue preference over Space Invaders, Pac-Man and Cooking Mama?), the commercials of their own deals (they anecdotally paid Hasbro a handsome sum), and the generally dominant position will all come into play and it is inconceivable (well, is it really?) that their partners will continue to play ball.

It might of course only be a brief interregnum on the way to an app store world. Smartphones are very much on the rise and, in that world, such stores seem to rule. Apple has taken the lead, Android followed suit and new stores are springing up almost by the day, which also includes operator-led ones: Orange already has one, Verizon Wireless has announced one (mobile web-based) and so has Vodafone (which might actually be bigger than Apples) as well as many others. The OEM all do the same (even though some carriers want to disallow them): Nokia Ovi, Blackberry App World, Sony Ericsson, LG, Samsung, you name them, they have it. The question of course is if that might mean the same thing all over again: will they again want it all just so? Will they again have it just their way so that a user would have the unique flavour of operator X on handset Y in this unique way, meaning that – again – thousands of SKUs would be required to service them? Groundhog Day? I hope not!
Image credit: http://www.antitrustreview.com/files/2007/07/files51lsaydhrsl.-ss500-.jpg

Fishlabs Slides to Advergaming Fame

Fishlabs, the German high-end 3D studio have long been one of my favourite developers (see here for a previous post). And with the ascent of the iPhone also appears to come the rapid rise to fame for them. Today, they have released numbers on one of their latest advergames, which they did for Barclaycard. For those not familiar: Barclaycard runs a large advertising campaign where a guy slides on a water slide through the city buying stuff whilst passing through markets, shops, etc. It took me a while to understand it (even though I am one of their customers) but it is to promote their new RFID-enabled credit cards.

Fishlabs produced an iPhone game for this (aptly called “Waterslide Extreme”). Interestingly, other than a Barclaycard logo on the main menu screen, I could not (yet) find any mention of the brand. Anyhow, Barclaycard seems to be super-happy as Fishlabs now has reported a whopping 2m downloads in one (!) week, which have generated 16m “engagement minutes”, presumably meaning that players engaged with the brand.
The – free – game is said to top the iPhone download charts in no less than 57 countries, including all the biggies like the US (where, reportedly, 54% of iPhone and iPod Touch users reside), the UK and Germany.

I just wonder if this is such good marketing (and I am not an advocate for unwanted in-your-face advertising at all): one mention of the brand (and very subtly, too) would surely make for only the most discrete of “engagements” with the brand.

So good on Fishlabs! But advertisers might want to consider giving these things a little more thought. Imagine the potential result for the image of the Barclaycard brand if, through a somewhat more thoughtful and smarter brand treatment, all of those 2m users would actually perceive it as a fun goodie brought to them by Barclaycard. Just to think of it… 😉

Gamevil valued at $70m

gamevil-eyeGamevil’s very own, indominable Kyu C Lee (@kyuclee) was kind enough to share with me the total number of shares in relation to Gamevil’s IPO (on which I reported earlier today). The total number of shares in the company is 5,484,780. Therefore, the company is floating stock representing c. 14.5% of the total, which values them at a fairly impressive $145m 69.65m or so.

Very respectable, folks! Well done!

Page 8 of 17

Powered by WordPress & Theme by Anders Norén