Tag: mobile content Page 8 of 12

iPhone content is recession-proof, too!

Is it becoming boring or is it becoming more and more exciting? However you view Apple‘s forays into mobile, it is very, very remarkable (and I do indeed think exciting) indeed: in ads in the NY Times and the Washington Post (see here), the company reports 300,000,000 downloads in 5 months (I leave the zeros in for mere impact…). That’s 2.1m downloads per day – on a single handset model, which isn’t even the single best-selling one (well, it probably is of recent, but not historically) and is normally only available through one carrier per country (which means that it could also have been, say, 10m downloads per day if extrapolated to the total user base). Woah! Is anyone still skeptical about the equation pretty hardware + pretty UI + hassle-free shop-front + single platform + single distribution outlet = success for content?
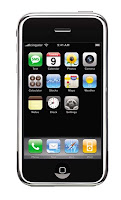
The iPhone’s fashion factor does, I think, not matter when it comes to the download numbers: If the above chain would not work, people might smile slightly embarrassed and continue fiddling around with the pinch-z
oom of pictures, etc but they would not come back time and again to get more content for the thing; I mean: just running around with it and placing it onto bistro, bar, cafe and probably even Starbucks tables will be enough to prove your membership in the circle of the hip and trendy media crowd.
There’s only anecdotal reports (or rather rumours) about how much money is being made by developers on the platform (we still suspect a lot of it will be in the “free” category but one rather reputable games publisher apparently said that they’re making more money on the AppStore than through all of Vodafone Global) but these numbers are – in any event – huge!
And it does show that content works if you let it work, i.e. if you make it easy to publish on a platform and if you don’t try to be your customer’s nanny and determine what’s good for them. If people would realize this, and that would be the only lasting impact of the iPhone, that would surely be a lot! Thank you, Mr Jobs!

Lower Handset Sales in 2009

The financial crisis will – what a surprise – also catch the handset manufacturers. A report tells us that handset sales are bound to fall in 2009, by 5.6% or 1.215 billion units, to be precise. The backend of 2008 already sees the impact, too: growth predictions have been reduced from 10.4% year-on-year to 8.9%.

This is in line with reports from Blackberry maker RIM who reduced its forecasts today. Even mighty Nokia is expected to lower its forecasts.
It can probably be expected that this will also impact the mobile content market: it is widely accepted that consumers tend to spend on mobile content in the first 3 months after they got a new phone. So: no new phone, no new content… Moreover: the above reduction in growth does not actually show the whole picture. Mobile content uptake is much higher on high-end phones. However, these are normally bought by way of upgrades, and it is there that the most severe drops are being predicted.

“While new subscriber additions are continuing at a healthy pace and are poised to grow by 563.9 million in 2008 and by 506.5 million in 2009, an overwhelming majority of the new subscribers are coming from the rural areas of emerging regions,” Teng said. “These subscribers primarily are purchasers of low-cost, entry-level handsets. However, the pricier feature-phone and smart-phone market segments are driven by existing subscribers who are upgrading their mobile devices to take advantage of new features and advanced data services. As the economic climate deteriorates, these customers are delaying their purchases.”

All doom and gloom then? Well, maybe not: others predict that the recession (at least in the US) will actually drive the number of wireless-only households. And, after all, a mobile game at €/$/£ 5.00 a pop is not the world, is it?

Juniper to the Rescue…

We can depend on the researchers from Juniper after all (or maybe they simply felt bad after reading my post on their last report). Whichever the reason, apparently the mobile content industry could be worth a hefty $167bn (!) if – yes, if – the operators would resolve to allowing a workable commercial environment, namely by limiting themselves to lower revenue shares. Whatever the caveats (which are, as usual, hidden in the expensive main report) this number is topping even the loftiest predictions to date; right on in times of the doom and gloom. The key apparently lies in whether operators would act as dumb pipes (no richness for anyone) or a smart pipe (lots of play money for all players on the value chain). In their own words:

“If MNOs are to benefit financially, they need to move away from their Dumb Pipe roots to the Smart Pipe model, though they will clash with the content providers which already dominate the Smart Pipe. A compromise needs to be found.”

A smart pipe is understood as one where operators would offer flexible, application-centric value configurations, allowing lean, efficient content offerings from third parties. A dumb pipe is one where content (and value) would merely rush through the pipe without any value being added by the operator. The prevailing model in the mobile games world, namely the on-portal approach where operators implement comprehensive vertically-integrated models (“walled gardens”) is suggested to be somewhat doomed as content providers would gain bargaining power (presumably through consolidation of the supply side plus entry of meatier traditional media players in music, video and TV).

This is all pretty speculative though, and without some background it is quite frankly impossible to analyse the numbers some more. Mobile content appears to include (as per their report from March) games, music, video, TV, social networking, adult content, gambling and so on, and so forth. However, the exact calculatory basis is again hidden in the depths of the report, so I don’t know (do they e.g. take the gross gambling revenue or on;y the rake, which is only a few percentage points of the former). Anyhow, due to these foggy conditions, commentators seem to either merely re-print the PR blurb or mock it (Stuart Dredge thinks that “only gas could do that kind of money”), which is a shame really; just think what you could with this much money…

China Mobile puts on turtleneck

The theme starts becoming lame, I know (and I herewith promise to look for new semi-funny references to Steve Jobs). However: if the world’s largest operator by subscribers changes its dress culture, that is to say swaps from a tightly controlled walled garden to a free store concept, that surely merits this. So, without further ado: China Mobile plans to launch its very own AppStore. Its Chairman & CEO Wang Jianzhou (who was, I think, not sighted in Mr Job’s favourite garment) announced this at the GSMA Mobile Asia Congress in Macau. Now, with a whopping 436.1m subscribers, this opens fairly interesting vistas for mobile content – if, yes if, one can hit Chinese taste, that is. They specifically cite Apple’s success with its iPhone as a trigger for them to do it. Truly impressive that a company so big would move so quickly.

This will surely hit the news wires some more in the coming days but I will now retire and brush up on my Mandarin…

Et tu, Juniper?

It must be truly bleak: even the best friend of every young telecoms entrepreneur on the fundraising trail whose reports rarely failed to feature as a footnote in an investment memorandum for the next big digital thing now sounds a word of caution. Juniper (whose reports I still cannot afford) issued its latest report on mobile gaming and it actually reduces (for the first time, I’m sure, even if I haven’t checked) its prior predictions on the growth and size of the sector in the next, erm, 20 years…

They see growth stifled by the restrictive operator business models. Dare I say it? May they be right? They refer to Apple‘s AppStore, which is the anti-christ to every operator’s walled garden: free for all, free price-setting, Darwinian survival of the fittest (or least-charging), thousands of applications, games, etc, etc, and relatively generous revenue shares on top (although 80% of $0.00 is not very much at all).

Juniper points however to 2 important and true factors: the tolls demanded by the operators to access their precious customer base are very high indeed considering that many do not provide a very compelling service in return. Secondly, marketing and marketing opportunities on-deck normally – well – suck. This was all well and good as long as their were no alternatives (other than the likes of Jamba, Thumbplay and few others). But with the ascent of the iPhone, everyone seems to erupt into a frenzy of trying to replicate the “beautifully simple and compelling UI” for which the purveyors of the Big Black Turtleneck are so famed for. This, Juniper fears, will lead to players exiting that business (I have heard unconfirmed rumours that SEGA decided to call it day on internal J2ME development following their huge success with Super Monkey Ball on the iPhone). 
Other than that though, not much new. And Juniper would not be Juniper if they would not predict “significant” growth in the next 5 years (conveniently long in order to be basically unpredictable): they see the market to roughly double in the next 5 years, which would be 20% growth per year (on today’s terms), which is not all that bad after all. 

Mandalay buys AMV

Twistbox owner Mandalay has bought European D2C firm AMV for $22.8m in cash, shares and deferred consideration. AMV operates the D2C brands Bling et al.. The new European HQ is to be at AMV’s UK location in Marlow, which presumably means a demotion of Twistbox’s Charismatix branch.

The rationale of the deal appears to be this:

The combination of Twistbox’s global on-deck distribution with AMV’s direct-to-consumer expertise uniquely positions Mandalay Media to deliver compelling consumer propositions while maximizing revenues for its wireless operator and content partners,” stated Twistbox CEO Ian Aaron.

Whether or not this position is “unique” does not really matter. And why a D2C offering maximizes operator revenues is at least unclear, too, but hey, who cares? What is true is that Twistbox runs some operator decks and has – through the old Charismatix links and its adult footprint – some decent links on a number of carriers in Western Europe. To bolster this with £10m of D2C revenue (this is the number the AMV website would make us believe) makes sense as the sensitivity of carriers to accept competing offerings outside their decks might well lessen. In this case Mandalay/Twistbox/AMV may indeed be onto something. The remaining question might be if the (current) breadth of distribution they have is enough. But it’s not the end of days…

Mandalay/Twistbox has by now ramped up a decent amount of venture cash (see here for a previous round) and is yet still seen to be breaking into the top tier. Come on, guys!

No ad-supported content after all? Really?

We will all remember that ad-supported content was the flavour of the month a short while ago. There were successful trials and a lot of hype all around, hell, there are even MVNO based on this model. Now, however, there is a survey that suggests that people will pay to avoid ads (if you are a true believer, look at the end of this post though…). Who’s right then?

But, alas, the nasty consumer wants to have it all, it seems. I quote:

While the vast majority (56%) believes that content downloads to mobile phones should be free of charge, there is a growing number of consumers that are so averse to advertising that they are now willing to pay a premium in order to avoid it, signifying a shift in how operators need to be tailoring their offering. A substantial 25% of respondents said that they would rather pay for a download if it guarantees them immunity from advertising.

Now, what then? Free content? And who is paying us poor sods who produce it? Hmm. Now, it gets even more confusing: according to the study, in particular the younger demographic shuns ads. 35% of the 16-24 year-olds would rather pay than get ads vs. only 17% of the (presumably battle-hardened and more cynical) 35-44 year-olds; one would have thought so that the elders with their higher spending power were more likely to pay… Hmm, hmm.

There is another interesting twist to this though. Another quote:

One symptom of this trend is the increased resistance to targeted advertising on mobile phones. Whilst 47% of people feel that adverts tailored to their individual tastes and interests are a good idea overall, half of those who were willing to receive targeted ads on the internet were not happy to receive them on their mobiles.

This would suggest that there is a trend (or rather demand) to bridge the boundaries between media: offer content and do, by all means, use advertising to finance it but do stream the latter to other user screens (presumably the PC first and foremost). Are there any models out there to address that? I haven’t heard of any and I must say that I find implementation of this rather tricky to achieve. Just another study then? Hmm, hmm, hmm.
NOW, just when I clicked “publish”, I received one of my favourite newsletters, the very recommendable VentureBeat, who published an interview with Nielsen’s SVP Mobile Media, Jesse Goranson, and, what can I say, he says it’s all good: according to yet another study he cites (which I cannot access), 53% of advertisers (ah, not consumers then) anticipate a rise in mobile ad-spend in the next year. Goranson does, however, also state a flux and indeed uncertainty about where it is going to go revenue-wise. More hmmm’s then, I guess. Good night!

Page 8 of 12

Powered by WordPress & Theme by Anders Norén