Tag: iphone Page 6 of 16

O2, Orange/T-Mobile, and now Vodafone: iPhone everywhere in the UK!

After the news broke that Orange will add the iPhone to its roster from just before Christmas, today we read that Vodafone UK will do the same, only a little later, some time in Q1/2010. Vodafone said that not having the iPhone was basically the reason for losing 200k customers in the last quarter alone. Vodafone had previously been shipping the device in 12 other territories.

With Orange and T-Mobile merging their UK operations, the new set-up which sees basically all large operators offering the device should make for some juicy deals. Analysts reckoned the contract tariff for to come down by £4-5 per month. Orange did not say anything specific but “indicated” that it would be cheaper than O2’s deals.

According to the article, Virgin Mobile (an MVNO that sails on the Vodafone network) is also “understood” to be desperate to secure the right to sell the phone. Happy days…

App Bonanza or Analyst Bonanza?

In the last two days, two forecasts informed us about the value of the mobile app market in – convenient as ever – the distant future that is 2013. US analyst firm Yankee Group predicts the US app mobile market to be worth $4.2bn by then. Today, British analyst Wireless Expertise (run by former Netsize exec Anuj Kanna) topped this easily by predicting the (global) app market size to be $16.6bn by that time (free copy of the report here).

I can hear your moans…

However, let’s have a look at the numbers then, shall we? At the end of 2008, there were 4.1bn mobile phones in the market. Because apps tend to thrive most on smartphones (and the analysts seem to thrive on them, too), let’s have a look at that sub-sector. I would estimate the smartphone share to being somewhat under 10% (Symbian claims c. 250m devices in market, Apple has some 30-odd million, so RIM, Windows Mobile, Android, Palm, etc should probably be OK with the balance of some 100m). In Europe and the US, the share is much larger but in the big volume markets China and India it is bound to be much smaller, at least for the time being. Global smartphone shipments in 2008 were around 140m.

If we estimate a 20% growth year-on-year for smartphones (vs. 5% for the overall phone market, which seems to be loosely in line with the general dynamic), then we would end up with something like 900m smartphones by 2013. Yankee Group predicts that smartphones in the US will quadruple by then (from 40m to 160m) and does not seem to be very far off. Wireless Expertise thinks the global number will be 1.6bn, which again, might not be that far off.

The question is however if people will really download this much stuff: Yankee Group predicts that the actual value of the market will rise 10-fold and that the average price point of an app will be $2.37. Why that is so, you ask? Well, pay $495 and you will know; I don’t…

Now, the good folks of Wireless Expertise see the thing quadrupling until 2013. They do, however, count “ordinary” mobile games as they are being sold through carriers amongst the apps, which means that their starting point is higher, namely $4.6bn in 2009, so they’re looking at this quadrupling. They raise some smart points on app stores and how they (well, it) changed the way users access and consume content, how carriers will need to look for alternatives to increasingly commoditized voice and messaging propositions, etc. But why there should be a 400% rise in e.g. traditional J2ME mobile games remains – whilst it would be wonderful – pretty much in the dark.

Talking of J2ME and feature phones: I do not know how they are being woven into the equation but there would certainly be a wide field for any self-respecting crystal-ball-reader here: on the one hand, app consumption on such devices has traditionally been fairly shabby but, on the other hand, this could well change if connectivity, bandwidth, UI and the right price plans would come together to offer a compelling mobile web solution. So then apps would need to be translated into widgets or something like that. Would users then pay for them? Don’t know. Or would it be the “Freemium” model according to which “Free gets you to a place where you can ask to paid?”

The challenge of these reports is their “simplified” assumptions: if only one of them fails, you go “oops”, and your prediction is halved (or worse). On Wireless Expertise’s case, this is particularly clear: their assumption is that there will be a dual strategy of (presumably OEM-driven app stores) and mobile web-based widget stores. Now, they further assume that Ovi, Windows Market, etc will all be as successful as Apple’s App Store. By early (anecdotal) data, this could not be further from the truth (see here for what that may mean). Nokia in particular struggles to get its head around a viable and compelling media strategy (cf. here and here). And hence the beautiful hockey stick would actually fall flat on its face.

Now, I am not predicting total doom and gloom, in the contrary. I do think that Apple’s wake-up call has brought a much-needed new wave of innovation and I also believe that this will be successfully incorporated by some carriers and OEMs. But by all of them? Not very likely.

And so we see: the reports are a touch on the optimistic side when it comes to volumes and assumptions. But, hey, that’s their job, I guess, and after all they have at least dropped their masks now: Yankee Group call it fairly openly a “gold rush”. And what happens then we had been shown a long time ago: you end up eating your shoelaces. So maybe this is less of an app bonanza and more of an analyst bonanza then…

Oh Nokia, where art thou?

Nokia struck again, it seems. This time? No, not another multi-billion dollar acquisition such as Navteq but another tiny start-up, namely the “boutique” travel social network Dopplr, which the Finnish telecoms giant allegedly gobbled up for anywhere between €10-15m. Hm. Hm Hm…

Dopplr’s Business Case

Let’s see what Dopplr does (besides its co-founder [and angel investor] being an old Nokia hand): the idea is to share trips with friends so that a) people coincidentally going to the same place at the same time (“what??? you will be in Barcelona in the second week of February, too???”) will find each other and b) they can share cool and “unique” tips from other travelers. It is (was?) one of the group of location-aware social networks that have been and are still waiting to come out of cover.

Nokia’s Master Plan

The deal is great for the Dopplr guys who seem to have made a nice return and the pieces of the jigsaw on a very, very, very high level seem to make sense: Nokia is assembling a location-based empire. They acquired Navteq in what was Finland’s largest acquisition ever, they bought German location social network Plazes, and now Dopplr. And it now all comes together at Ovi Maps (which looks quite good!). Makes all sense, huh? The rationale was – arguably – to do to sat-nav systems what they did to (small) digital cameras: kill them and incorporate it into their phones (or multimedia devices). When Nokia moved to Carl-Zeiss lenses, mobile phone camera were basically on par with low- and mid-tier digital cameras. Why carry 2 devices if 1 will do the same job. Easy! And boy did it work!

So, let’s do the same with maps. And, more importantly perhaps, do not maps (and location-awareness in general) find a completely new way of justification in mobile phones, i.e. in devices that are, well, intrinsically mobile? Yes, it does. When Steve Jobs premiered the original iPhone, he famously ordered coffee from the nearest Starbucks, using a maps application. Simple, right? Wooing the masses but nothing much in it, right?
But! On the maps side, Nokia competes against Google Maps (this is what Jobs was using), which is free (if one leaves aside the probably not insignificant investment that will have gone into this service with its various extensions such as Streetview et al). It also has an open API and many, many people use this. It is embedded on the iPhone (Jobs again) and most people I know use it on their Blackberry because it is better than RIM’s own offering. A free download to most phones, Nokias included.

The Impact of (Fairly) Open Networks

Now, I never got these highly specialized things anyway. I find them way to complex to handle: when I am going on a business trip, I am normally much too busy to feed data in some travel network or other. And when I am going on a personal vacation, I am a) even busier and b) want to be left alone (normally). Oh, and did you see that Twitter plans something like this, too?
But even aside from this, when it comes to “being found”, all my friends (real and virtual) knew through my blog, through Twitter and Facebook that I was going to France this summer. Do I really need another, specialized service for this, over and above the ones that can provide that information and also everything else? In other words: does it make sense to try and hone a super-focused service when similar (if not identical) results can – and already are being – achieved through smart filters on networks that have somewhat of a head-start when it comes to active users? I mean, Facebook has more than 300m users, MySpace – even if it seems to be struggling a little lately – will have more than 150m. And then you have Twitter, Bebo, Hi5, Orkut, StudyVZ, etc, etc, etc. – that is more than Nokia sells all year.

Now, the existing players are adding geographical awareness as an additional feature to their services. I mean, even YouTube is doing it!

But the real point is: whoever uses one of these (say, when you are in Brazil, you use Orkut), there is a certain likelihood that your friends will, too. Otherwise, you would not be on it. Need more? I doubt it.
On top of that, it is – arguably – much easier to integrate a location-based function into a network that already has hundreds of millions of users (and I am not talking of hundreds of millions phone users because they only are potential users of any service that might come with the phone) than to build one. Nokia does certainly have a great starting point (it sells more devices per year than Facebook and Twitter users combined; see – old – numbers here) but they are not with Nokia because it provides such a great network but because their phones are good.

When it comes to services, it has become an issue of today’s mash-up world where access and resulting services go across a variety of – more often than not – open offerings rather than tight proprietary ones, and Nokia seems to be struggling of getting to grips with this. Some commentators compared it with Yahoo!‘s M&A swoop in order to try and grab back the love it lost to Google and others. Even if one isn’t so harsh, it seems obvious that the thought pattern behind Nokia’s thinking might be a little outdated. I stand to be corrected (and would love to be since Nokia has brought a lot of really great stuff to the world) but that is what is worrying me. So congratulations again to the Dopplr team again but, dear Nokia, for the time being I remain skeptical as to the commercial sense of it (and, yes, I appreciate that €10-15m is but a fly speck on your balance sheet if it fails…).

US Mobile Advertising Snapshot August 2009

I had covered the monthly Scorecard for Mobile Advertising Reach and Targeting (what a mouthful) from Millenial Media before (see here for the May figures), so here’s an update on this (and note that these are all US-only figures). The firm covers just under 50m users, which seemingly represents 79% of the mobile web (but only 11 of the top 25 sites as per Nielsen). However, it should provide for a very decent overview of the state of advertising on the mobile web. So here it goes:

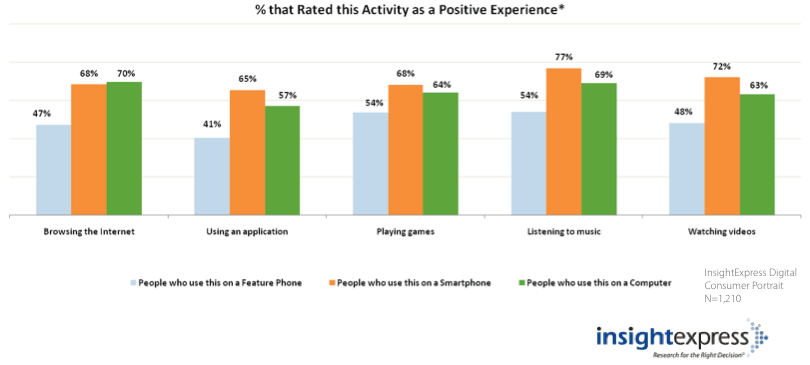
The first really noteworthy piece has not actually anything to do with advertising but with user satisfaction: would you actually have thought that users enjoy most things more when done on their smartphone than on their computer, including playing games and watching video? The computer only leads (and by a meager 2% higher rates) for web browsing (70% vs 68% on smartphones). Wow! Here’s the graph:

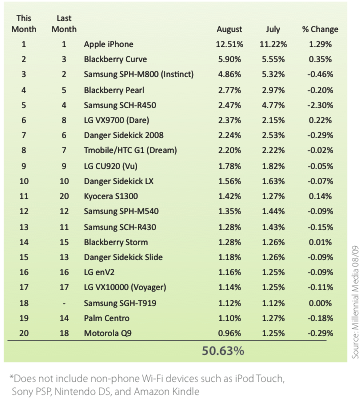
This is very encouraging and probably also owed to the market leader when it comes to ad impressions received on a mobile device, which is – moan – the iPhone of course. The last snapshot I covered had the Samsung Instinct in front but this has slipped back to a still respectable #3 now. Blackberry’s Curve takes 2nd place. Here’s the top 20 list:

Compared to their old format, Millenial Media is no longer spitting out a comprehensive chart showing the CPEU (cost per engaged user) per demographic/targeting method. They have adopted their proprietary “Mydas” tool, which appears to enable them to mix things together in an optimal way. It is understandable since this is their business but the look under the bonnet was great. Alas, no more. So here’s what we still learn:

  • iPhone and iPod Touch impressions are still growing with double-digit numbers (month on month they grew 68% in June, 29% in July and 15% in August).
  • Average monthly page views is 111 (up 5 views).
  • The top 20 phones (see above) make for 50.63% of all device traffic, which is drop by nearly 4% compared to the previous month.
  • A whopping 26.15% of all ad impressions were achieved on devices on a WiFi connection (bandwidth is king!).
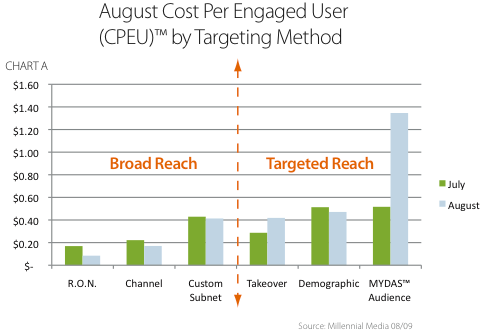
  • Cost per Engaged User for audience targeting increased very significantly from ¢52 to $1.35, which is owing to Millenial’s aforementioned Mydas thing (or so they say). Most CPEU rates decreased however. Here’s the chart:

So what does it teach us? Well, due to the new format unfortunately less than previously… but then: I’d love to have that Mydas touch… 😉

Is Spotify finding the Business on the Move?

Spotify was a breath of fresh air when it hit the markets. Finally, there was someone who combined the ease of iTunes with unsurpassed breadth in catalogue. Lots of songs. Always available. And even the ads weren’t all that bad (which is why few people upgraded to the ad-free premium version [more on this below], much to the dismay of label executives who – rightly – fail to see the greater good of dependable revenue streams from those few ads; although they are getting more, mind you).

Then, back in July, Spotify submitted its iPhone app to Apple. And the big wait began. After lots of back and forth and speculation if it would or would not, Apple finally approved the app. So now it’s live, and not only on the app store (where it ranked #1 on the UK store when I checked tonight) but also on Android Market. A Symbian version is in the works.

All reviews I have read are raving: from “very impressed” (and that’s the Daily Telegraph no less) to having “to pry it out of my cold, dead iPhone” (Wired), everyone waxes lyrical about the thing. It comes with a load of stuff, too: streaming all your favourites from over 6m tracks on the go sounds promising, and one can also sync up to 3,333 (what a number!) songs for offline use in the networks’ broadband doldrums.

The trouble (!?) is: you can only use it as a premium subscriber, which means forking out £10 per month. Which brings me conveniently to the key point, which is the business underlying model.

The labels are fairly happy, it seems. Because they got shares in Spotify itself. Some more equal than others though: the majors are said to have received a disproportionately high stake). The same report claims though that ad income is only £82,000 and, in the UK, only 17,000 users had signed up for the premium version. However, shareholders and all that, Spotify still has to pay the labels a fee per streamed track, irrespective of the user paying or not. Tricky model, that. Note though that this might be different in other countries: according to reports, the world’s largest major, Universal Music is making more money from Spotify in Sweden than from iTunes!

Anyhow, all this was before the mobile app, and mobile may well be the game-changer for them… The launch of the iPhone app, glorified niche audience or not, seems to have gone fairly well (#1 position on fhe app store within days of launch). Spotify reckons that mobile is where its future lies. And this had been echoed (and well ahead of the actual launch!!!) by others in the industry, and perhaps rightly so: if users are used to (and in love with) a service they are more likely to pay for it if that means they can also have it whilst on the road. For the marriage of music with the world’s leading MP3 player come mobile phone, the iPhone, this seems to be made in heaven: I can have the smallest model and still carry 6m+ tracks around with me? Wow! Here’s value-add!

The much-discussed freemium model it is then: get them hooked on the free desktop app and convert them to paying users on mobile. It has long been known that users are more likely to pay if stuff is portable (I can still recall the disbelief of music executives when they realized that people would pay more for a monophonic ringtone than for a full-blown music track). And whilst now the link between (free) basic service on the desktop and (premium) mobile service is new, the principle is old and proven: and it is simply added value (plus the little things like being used to paying on mobile and having convenient existing billing models in place). If the user perception is that they are getting value for money, they are willing to pay. And if it is for such a fairly special thing such as music (don’t we all love and nurture our very own musical mix tastes?), the step is even easier to make.
Spotify fully expects this to fly: they are upgrading their servers already. Labels are said to be still a little jumpy but I reckon their experiences over the last decade or so have shown that their is a need to re-think incumbent models…

Handmark powers Samsung’s App Store

Samsung’s new app store (no one can do without one these days!) will be operated by Handmark and is set to go live on 14 September (2009, that is), I read. The respective site is (sort of) live and appears to accept registrations of prospective vendors. Go here if you feel like it… Launch will be in the UK, France and Italy first. No word when the others follow.
According to the press release, the content available will consist of Windows Mobile and Symbian s60 titles and will be available on the Omnia, I8910HD, Omnia II and Omnia Lite (so a true omni-store then). Billing is available via both credit cards and operator billing, which is – on the face of it – good (i.e. plain and simple credit card-billing doesn’t often work; Apple’s app store is an exception, I’d say, because input is via iTunes with which people are already familiar).

I’ll spare you the rest of the lyrical odes to the various partners… But let’s try and break this down: how big will this thing then be? Samsung is a force in mobile and its Omnia phones have had some very significant success indeed: in some markets (Germany was one), the Omnia outsold the iPhone by some margin (in December 2008, the Omnia had a 14.9% share of the German smartphone market compared to the iPhone 3G with 7.6%). It also launches in India now. I could not get my hands on solid sales numbers though (in the top 10 list by accessory sales for June, the Omnia came in on #10)… However, anecdotally, it is behind Nokia, RIM and Apple in global smartphone market share. So if we say that, on a global basis, there will be about the same number of devices around, that would make the phones a good success for Samsung.

However, when it comes to usage, I am not sure if the Omnia can compete with the iPhone. If we take ad impressions as an indicator (and it really is just that), we’ve seen that the iPhone’s 8% market share translates into 40% ad impressions. And because a lot of apps (and web “apps”) use ads, I think it is probably safe to assume that usage is higher. And this is arguably the crux of app successes: they need to be available but they also need to be discoverable and usable, and all of this with a lot of ease. Will they succeed? I hope so as it would do a ton of good to the industry would there be more than the niche player Apple. Their new TouchWiz SDK (see here) should help ease development for better UI, and the features of the store they announced look decent so far, so let’s keep our fingers crossed!

Image credit: GSM Arena

iPhone = (also) Business Phone?

The all-the-rage iPhone (can someone please come up with a worthy competitor, please, so we have other things to talk about, too?) is said to be increasingly the businessman’s (and woman’s!) phone of choice. Satisfaction rates outstrip Blackberry and anyone else out there competing…
I am not sure how it is elsewhere but in the UK where O2 holds the reigns on the iPhone, it appears that this might only be true for the ones that work for very generous employers (or those whose IT departments are not very cost-conscious) or that have only domestic businesses to pursue. Because when one attempts to make one’s iPhone travel-proof (and, remember, the data usage is what makes it such a delight!), you get somewhat of a rough awakening: transferring your all-you-can-eat data plan to international territories, fail. No such thing. No can do. The only thing one can do is buy a data packet of either 10MB (for £20) or 30MB (for £50). And this even though I am on one of the dearer packages on offer.
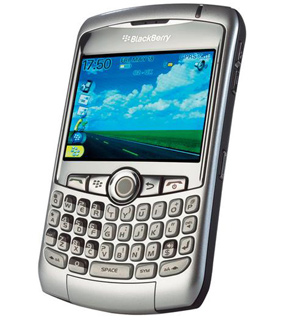
Now, would I own a Nokia N-97 with a Vodafone contract, I would roam as freely as a bird (well, they don’t actually say anything about data roaming…)! If I would be on a Blackberry Enterprise package (on O2!), it costs £20 to extend to international roaming. No worries about data consumption. Keep the e-mails flowing… Anything like that for the iPhone? Nope…

As a customer, I say: shame on you, O2! It is terrible! I am going on a vacation with my children to Germany (where O2 is also present!) and France and one of the biggest cost items will likely be my phone bill. Not so good at all!

Page 6 of 16

Powered by WordPress & Theme by Anders Norén