Tag: google Page 5 of 8

Motoblur & Android Fragmentation: The Follow-Up

Yesterday, I blogged about Motorola’s Motoblur UI, which adds an additional SDK for its specific APIs beyond the standard Android stacks. I reckoned that this might mean more fragmentation, which would push it a step closer to the nightmare that was/is J2ME.

I received two quick reactions to this: one reader commented that this was only bad if you wouldn’t have good tools and compilers. To him (@tederf), I would respond that, while it is certainly true that good tools reduce the friction, raise efficiencies and alleviate overall pain, the smallest common denominator is always just that. In my previous companies, we used to produce up to seven or eight different J2ME builds in order to maximise performance of our games on the huge spread of handsets. Could we have done with one build? Probably. Would the result have been great? Almost certainly not!

Anyway, the more interesting reaction came from the good folks at Motorola themselves. They reckoned (via Twitter; they are @motoblur) that:

with all due respect, I feel you’ve misunderstood motoblur, and android fragmentation concerns are a wee bit overblown.

Now, now. I offered them a guest post here in order to explain this further. I have unfortunately not yet had a response (which I take, applying Twitter attention spans, as lasting silence). But I still wanted to use the opportunity to elaborate a little more on this (and, no, I will not lament Moto’s lost opportunity to feature their wares on this humble site).

To clarify a couple of things outright:

  1. I would be delighted would I be mistaken (and note that I am not a techie, so this is a distinct possibility!).
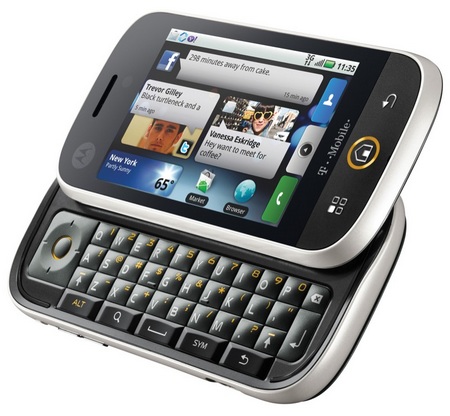
  2. I would be equally delighted would Motorola manage to regain some of its lost ground. The world clearly would be a better place with another strong manufacturer regaining old strengths (although maybe with better UI this time around – which Motoblur certainly seems to offer [see picture on the right of the Motorola CLIQ!).

But let’s go back to the general issue of Android fragmentation threats (the fact that I pointed this out – again – en cas de Moto is of course purely coincidental).

So let’s dive in: with open source software, there is always the intrinsic possibility that fragmentation will occur. Why do people customize it? Because they can! vendors, developers and operators that make up the Open Handset Alliance (which releases Android) can tweak is in whichever way they like (or “need” to) and for any number of reasons: to protect IP, to optimize performance on their network or for certain devices or simply because they feel they need some distinguishing factors, some degree of uniqueness. The result can be, however, as one analyst puts it that

there will be multiple flavors of Android, all of them incompatible with each other. That, in turn, necessitates different versions of each application or updates to accommodate the entire device ecosystem. On the whole, such activity negates the cost efficiencies inherent in the idea of a standard, open operating system, and potentially makes the Android Market a confusing place to shop for widgets.

And that’s what you call fragmentation. Interestingly, there were rumours that Google had made the Open Handset Alliance members sign “non-fragmentation agreements” but it seems that this is either not true or not enforceable.

Others point out that HTC, Samsung, Dell, Verizon, (may I add Motorola?) all have phones on the way that run on different software to the others. Reports of version conflicts, lack of backward compatibility, etc, etc. I mean, hell, there is even an “alternative” Android app store (with 223 apps as of tonight)… Sounds familiar?

Dear Motoblur, if it is different with your SDK, please enlighten us! I am sure I will not be the only one applauding!

Image Credit: http://www.visionmobile.com

More Fragmentation: Android & Motorola’s Motoblur

A new round of fragmentation looms. It is something I have been fearing for a while now: that OEM (and carriers) would make use of the open source of the likes of Android and LiMo to produce their very own flavour of apps. So after Vodafone’s 360 announcement (with customized LiMo storefronts, etc), Motorola announced so-called “signature apps” from a number of developers that are all delivered through Motorola’s new “Motoblur” user interface, which

is based on the Google-backed Android platform for mobile systems. Motorola [will] offer an additional SDK for its APIs beyond what is available for Android.

And then it said that

Over a period of time–we’re not there yet–we’ll allow the APIs to be available so people can develop many more applications than we can think of ourselves, but it’ll take us a little bit of time to mature ourselves to a place that we could open up APIs.

Ouch. An additional SDK. Which is not yet there yet. Whilst the Motoblur UI looks actually quite nice, this sounds suspiciously like another round of walled gardens, onerous internal and external QA, fragmentation and pretty much a fall back into the traps of the J2ME uber-customized world where one needs to support hundreds of devices for a commercial roll-out (with the trouble of course being that, all too often, that work meant that it would no longer be commercially very sensible). Oh dear…

It makes one want to call out for a quick advancement of HTML5 with Gears and all, so that one won’t need apps after all. The issue of connectivity and usability, etc would of course still be there. Such despair…

droidcon: Android Conference, Berlin (4 Nov 2009)

As Android continues to roll out (at least 18 devices by year-end), the ecosystem around it starts to sprout, too. To highlight this, an Android-centered business and development-oriented conference, Droidcon, will hit Berlin on 4 November, and I will be giving a keynote on licensing models and open source (full programme here).

It looks like a very exciting event, so I’d like to encourage everyone to come (there are 4 parallel tracks, so you do not have to listen to my ranting…)! Register here (and, no, I do not earn a commission).

I’ll post a little preview on what I will be talking about more specifically ahead of the event, so stay tuned.

Vodafone 360: the Good, the Bad and the Ugly

After much huffing and puffing, Vodafone unveiled yesterday what everyone had been waiting for for months and months: its new Vodafone 360 concept, which will replace Vodafone Live! It launches on – drumroll – LiMo-OS Linux phones from Samsung with touchscreen and GPS and, for the H1, AMOLED display (yum!), WiFi, HSDPA, etc, etc, etc. and also supports a fairly big range of Nokia (not on the N97 though!) and Sony Ericsson devices (although, judging by the screenshots, it doesn’t look as sexy on those).

The 360 thing is, according to the press release

a brand new set of internet services for the mobile and PC which gathers all of a customer’s friends, communities, entertainment and personal favourites (like music, games, photos and video) in one place.

It has an address book with nodes into Facebook, IM (Windows and Google) and will “soon” also cover Twitter, Hyves and StudiVZ (the German Facebook clone). Two tailor-made (!) handsets that use a proprietary (!) interface based on LiMo’s release 2 mobile Linux OS. Users can create groups across different networks (which is very neat!), an app store with 1,000 apps at launch (no word so far what this comprises) and syncing with your computer.

So is this the big thing then? Here’s the good, the bad and the ugly:

The Good

  • The service reaches out. It acknowledges (this is a big step for most carriers!) that users have a life outside their carrier. Facebook, Live Messenger and Google Talk are a bit thin, I’d say, but let’s cut them some slack; the others will follow.
  • It has a couple of neat twists built-in: I mentioned a few above but there is also a feature that uses some spooky thing called the “Vodafone’s proximity algorythm” and which basically automatically favourites your most-loved people: the most frequently contacted people (like your mom?) come closer to the front.
  • At least on the custom-built devices, it looks much better than previous attempts by carriers to make something look and feel a little more user-friendly.
  • I hear that the whole widget-thing should be really neat. Now, I haven’t seen any of it as yet but the concept sounds good.
  • It works across different operating systems (at least LiMo and Symbian).

As a funny side remark, the PR blurb points out that

The beauty of Vodafone 360 is that all the services work together and they are easy to use.

So they weren’t before, huh? 😉 — sorry, couldn’t resist…

The Bad

Some commentators mentioned that the cloud-hosted address book and generally aggregation of contacts, networks etc through a provider rather than through the handset would tie people to the provider more closely (which might not actually be anything Vodafone would object to). I am not sure how tough it would really be (as you have your computer back-up), so easy on that.

It is still very much a closed-circuit affair: It is Vodafone and no one else. It is proprietary, tailor-made and not open. This is not good (and, yes, I know that the oft-cited iPhone is proprietary and tailor-made, too). Alas, its applications are not – unless your name is Spotify; then it takes a little longer… 😉

The Ugly

The underlying proprietary thinking is nothing I can see working longer term. In a world that is (Vodafone press speak)

a substantiator of Vodafone’s new brand expression – ‘power to you’ – which is focused on putting the customer in control and enabling simple and easy to manage communications, both mobile and fixed

this is also a little bit of a contradiction.

But I will say that it seems to be the nicest operator-built environment I have seen so far. And for this to come from the world’s largest operator is no mean feat and might actually yield some results. Go on, guys, tweak it, improve it, show us!

Oh Nokia, where art thou?

Nokia struck again, it seems. This time? No, not another multi-billion dollar acquisition such as Navteq but another tiny start-up, namely the “boutique” travel social network Dopplr, which the Finnish telecoms giant allegedly gobbled up for anywhere between €10-15m. Hm. Hm Hm…

Dopplr’s Business Case

Let’s see what Dopplr does (besides its co-founder [and angel investor] being an old Nokia hand): the idea is to share trips with friends so that a) people coincidentally going to the same place at the same time (“what??? you will be in Barcelona in the second week of February, too???”) will find each other and b) they can share cool and “unique” tips from other travelers. It is (was?) one of the group of location-aware social networks that have been and are still waiting to come out of cover.

Nokia’s Master Plan

The deal is great for the Dopplr guys who seem to have made a nice return and the pieces of the jigsaw on a very, very, very high level seem to make sense: Nokia is assembling a location-based empire. They acquired Navteq in what was Finland’s largest acquisition ever, they bought German location social network Plazes, and now Dopplr. And it now all comes together at Ovi Maps (which looks quite good!). Makes all sense, huh? The rationale was – arguably – to do to sat-nav systems what they did to (small) digital cameras: kill them and incorporate it into their phones (or multimedia devices). When Nokia moved to Carl-Zeiss lenses, mobile phone camera were basically on par with low- and mid-tier digital cameras. Why carry 2 devices if 1 will do the same job. Easy! And boy did it work!

So, let’s do the same with maps. And, more importantly perhaps, do not maps (and location-awareness in general) find a completely new way of justification in mobile phones, i.e. in devices that are, well, intrinsically mobile? Yes, it does. When Steve Jobs premiered the original iPhone, he famously ordered coffee from the nearest Starbucks, using a maps application. Simple, right? Wooing the masses but nothing much in it, right?

But! On the maps side, Nokia competes against Google Maps (this is what Jobs was using), which is free (if one leaves aside the probably not insignificant investment that will have gone into this service with its various extensions such as Streetview et al). It also has an open API and many, many people use this. It is embedded on the iPhone (Jobs again) and most people I know use it on their Blackberry because it is better than RIM’s own offering. A free download to most phones, Nokias included.

The Impact of (Fairly) Open Networks

Now, I never got these highly specialized things anyway. I find them way to complex to handle: when I am going on a business trip, I am normally much too busy to feed data in some travel network or other. And when I am going on a personal vacation, I am a) even busier and b) want to be left alone (normally). Oh, and did you see that Twitter plans something like this, too?

But even aside from this, when it comes to “being found”, all my friends (real and virtual) knew through my blog, through Twitter and Facebook that I was going to France this summer. Do I really need another, specialized service for this, over and above the ones that can provide that information and also everything else? In other words: does it make sense to try and hone a super-focused service when similar (if not identical) results can – and already are being – achieved through smart filters on networks that have somewhat of a head-start when it comes to active users? I mean, Facebook has more than 300m users, MySpace – even if it seems to be struggling a little lately – will have more than 150m. And then you have Twitter, Bebo, Hi5, Orkut, StudyVZ, etc, etc, etc. – that is more than Nokia sells all year.

Now, the existing players are adding geographical awareness as an additional feature to their services. I mean, even YouTube is doing it!

But the real point is: whoever uses one of these (say, when you are in Brazil, you use Orkut), there is a certain likelihood that your friends will, too. Otherwise, you would not be on it. Need more? I doubt it.

On top of that, it is – arguably – much easier to integrate a location-based function into a network that already has hundreds of millions of users (and I am not talking of hundreds of millions phone users because they only are potential users of any service that might come with the phone) than to build one. Nokia does certainly have a great starting point (it sells more devices per year than Facebook and Twitter users combined; see – old – numbers here) but they are not with Nokia because it provides such a great network but because their phones are good.

When it comes to services, it has become an issue of today’s mash-up world where access and resulting services go across a variety of – more often than not – open offerings rather than tight proprietary ones, and Nokia seems to be struggling of getting to grips with this. Some commentators compared it with Yahoo!‘s M&A swoop in order to try and grab back the love it lost to Google and others. Even if one isn’t so harsh, it seems obvious that the thought pattern behind Nokia’s thinking might be a little outdated. I stand to be corrected (and would love to be since Nokia has brought a lot of really great stuff to the world) but that is what is worrying me. So congratulations again to the Dopplr team again but, dear Nokia, for the time being I remain skeptical as to the commercial sense of it (and, yes, I appreciate that €10-15m is but a fly speck on your balance sheet if it fails…).

Mobile App Market worth $25 bn by 2014!?

Juniper is a research firm that regularly puts out 5-year forecasts, which it then varies equally regularly with new 5-year forecasts. So following on from the app vs web debate, Juniper rides to the rescue of the app world with its latest (well, not so fresh anymore really), predicting a not so modest $25 bn industry from mobile applications by 2014. There you have it, Google…

The big hockey stick will kick in from 2011 and it will come from value-added services rather than revenues from one-off downloads. Games will remain the biggest

So with this I wholeheartedly agree (as I pointed out here): the sector went from innovation through handsets to innovation through apps and is starting to enter innovation through services. If it will be a $25bn market in 5 years time, I don’t know. But then: the report is from April, so maybe they have varied it since.

The underlying rationale however is correct: mobile applications are merely a facilitator for the delivery of services to mobile devices, and there lies a lot of revenue hidden. So upwards, onwards!

So, Google: App Store or Web? Or Both?

Last week, there was the Mobilebeat conference on, and – amongst many other things – a lot of guys felt they had to air their opinions on the future of mobile apps or, errh, no apps. They spoke so elaborately about it that even the revered FT (albeit in its blog section) and the BBC felt compelled to run stories. Amongst others, the CEO of “indie” app store Get Jar and Google’s wonderful Vic Gundotra, VP Engineering and also equipped with this most valleyed of all Silicon Valley job titles, i.e. “Evangelist” (I would really like one like this, too!), in his case for developers spoke about where they saw information and entertainment on mobile phones going in the future and how the ecosystem would look like.

Now, let’s get serious.

What was Said?

First, GetJar‘s CEO sees the market for mobile applications becoming – get this – as big as the Internet (woah!). He then said also that it would peak at about 10m apps (in total?) by 2020. Hmm. GetJar then went on to warn that the number of developers would drop “drastically” and that only about 10% would be able to survive. The others would take their skills elsewhere. So where then? To the web? (This is of course interesting also because GetJar will deliver Sony Ericsson’s App Store…).

It is here where Google comes in. Gundotra said that, according to Google (and who would question them), the web had won. Even (!) Google was struggling with the device fragmentation in mobile and many, many applications could be delivered through “incredibly powerful” browsers as well. He even borrowed Steve Jobs for his argument, pointing out that the Apple CEO had announced that the iPhone was “Built for the Web” upon its launch.

There were others who contributed: Nokia’s Head of Services reminded everyone that Nokia was there to help with its Qt (Cutie, geddit?) cross-platform application network . The Symbian Foundation’s Executive Director, Lee Williams queried the need for more app stores and called, instead, for more than “just a bucket of apps”, which should look like an aisle with the very stuff that specific consumer is interested in and which (s)he could wander down at leisure.

They all however concluded that it [scil. the mobile web] was not there yet. Hm again… Let’s try to disentangle this all:

The Needle in the Haystack
Upon the launch of the app store and the wondrous stories of the iShoot developer Ethan Nicholas who coded in his bedroom after work only to resign from his day job weeks later because he made more money than he had ever thought. A lot of developers read that and, since it is the wet dream of every games developer (earn cash with an honest game without the “suits” fiddling with your game in between; anyone remember Copeland’s skateboarding turtle?), embarked on the journey themselves. And then they found, oops, it does not work that way? Why not? Well, because there are more than 400 applications going live every day. And with the sheer number of them, it could well be that the best app ever written is already out there but buried deep a couple of categories down in the app store.

This is no big surprise. It is how it works in any sector: one smart kid is not enough, you also need the environment and a lot of other building blocks to have a winner (as reigning F1 World Champion Lewis Hamilton is painfully realizing this year).

In the app store’s (and a gazillion other) case, this means that you have to make sure that you gain some attention. From Apple (or any other app store operator), from the press, from the users out there. And this is not news. There have been very well written pieces about this galore (see here for just one of them).

So will this mean the fall of a lot of the developers that went about their business thinking the app store magic would do away with centuries of business logic (there is a reason why companies have sales & marketing departments, you know…)? Yes, very probably. But does that mean the app model is flawed? No.

The Hit Dilemma

One of the Mobilebeat participants, namely Playfish, creators of some of the most successful Facebook games who released on the iPhone, too, complained about the hit-driven nature of games on the App Store. Whilst I am painfully aware of this dilemma, one has – again – to point out that this is pretty much how most of the economy works, too, unless, that is, one builds a superior and dominant brand (Tetris would be the example for the games world).

Other industries know this, too. Everyone knows IBM is a leading computer maker. Hardly anyone remembers that the Dutch electronics giant Philips used to be one of the biggest players in that market (not even Wikipedia mentions this); their CeBIT booth was bigger than IBM’s throughout the 70’s and early 80’s (my dad worked for Philips then; I need to dig out some pictures). What happened? Hey, they missed some crucial disruptive innovations and they were history…

What I want to say is that no one is immune to the demand for constant innovation and improvement (otherwise some Firefox will sneak around the corner and steal market share). The reason why this hit dilemma is more painful in mobile games than elsewhere is the relatively small size of the market to date: it is more difficult to build reserves than in other, more established sectors.

How Many App Stores? Mee too, me three, me four, …
With Apple’s roaring success with the app store, the whole industry stampeded to put out their own, and they have been moderately successful or failed. But it is early days! Why did they fail? Because they equally had hoped that one thing and one thing only (just name your bucket of apps an “app store”) would heal the painful failure of the sector in converting otherwise gladly paying users to also using, consuming, contributing to entertainment and information on their mobiles. Now, this overlooked that Apple’s model did not only consist of a storefront. It also consisted of a fairly simple developer programme (with a click-through agreement), a fair(er) revenue share to the developers and unprecedented ease of use in getting to the app of one’s choice. Try and apply this to, say, the launch of Nokia’s Ovi Store…

So do users need more than one store? No, not in general. If you can get all you ever need, want or desire from one destination, you don’t need another one. This however becomes a little precarious with a view to monopolizing channels. You would never know if there are not some that are a little more equal than you… So, having Firefox, Chrome, Opera, etc. next to Internet Explorer did the world a ton of good. And having Nokia, Sony Ericsson, the carriers working on alternatives to Apple’s app store is arguably of equal value. Will the user care? It depends on the execution: Google’s superior search algorithms made the old-style catalogue model previously found in search engines superfluous; why do I need to sort something if I have a little fairy that races to get me what I want in no time? So: if I have a bucket that comes with a little fairy, I don’t need long, long supermarket aisles. I’d rather get it home-delivered by the search fairies.

It’s the Usability, stupid!

Now to the key question: separate apps or web? Now in Google’s case, their pleading is somewhat obvious: well, they would, wouldn’t they?

Google, on the other hand, has apps out on most platforms for most of their web services: Be it Gmail (great Blackberry app!), Maps, or – all in one – their iPhone Google app, it comes as an app. And why?

Because it would otherwise be unusable! OK, let me rephrase that: the delivery of browser-based applications through mobile phones suffers some very severe setbacks today, amongst which usability on a small screen, constant connectivity and bandwidth. Whilst the latter two are arguably solvable some time soon, the former is a little trickier: when delivering to a mobile device, you not only have to download all underlying data (graphical assets, etc) but also an interface that works on that device. And because of the small form factor of mobile phones (even in the case of large-screen touchscreen phones like the iPhone), this is likely that your user experience will be significantly worse than on a large screen equipped with mouse, touchpad, etc. Apps can bridge this usability gap, and I would argue that this is precisely why Google is producing them. The underlying content can often (not always) well be delivered from the cloud but the UI of small devices is crucial to their sensibility.

With both (mobile) browser technology and handsets improving, the space available for services that can sensibly (and with superior costs) be delivered from the cloud (i.e. through the web) will increase, and steeply. However, there will always be applications that will either be impossible to deliver via the web (name a high-end 3D racing game on the web) or where a specific mobile UI would greatly improve the usability of any service.
It is another question if these will be delivered via flexible widgets or larger, more comprehensive apps (functionally, a lot of apps effectively are covert widgets); this will simply be (and remain) a question on the complexity of any given task and the ease and superior (or not) delivery an app would provide over a browser-based service. There will be an equilibrium between the two but I posit that there will remain large areas where browser-based delivery will not be able to compete with specific applications (that will draw on data from the cloud as well). Incidentally, 58% of Wired readers agree with me (and another 17% don’t care; check the bottom of the article) 😉

This can be seen on the (“normal”) web, too: Google Docs (Google’s online suite of office applications) is, despite a lot of effort and being free to use, an utter underdog to MS Office or Open Office (the only numbers I could find give Google Docs a market share of between 1% and 5%). It is, I think, because downloadable office “apps” are so much more usable (and react instantaneously irrespective of my ISP’s moods) than online services. The complexity of the computing (and – more importantly – the bandwidth necessary to deliver it) is just too overwhelming (see here for a previous post on this).

More evolved mobile apps often are (and/or will be) a hybrid: they offer a front-end that optimizes the data drawn from an online environment for use on a specific mobile device. It will not be an “either/or” but an “and”. Anything else would anyway be so last century!

In Conclusio:

Whenever possible, services will move online because it is cheaper to produce. Whenever necessary, they will be delivered through dedicated apps because it is required to use them!

Page 5 of 8

Powered by WordPress & Theme by Anders Norén