Tag: Apple Page 9 of 17

Mobile Innovation; in Response to Scoble

Egoblogger extraordinaire Robert Scoble has never been known to be shy, and so he declared with his usual great fanfare that Europe did not matter any more in terms of mobile innovation. Why did he say that, you ask? Well, Nokia apparently took him to visit their research lab in Cambridge (no, not in Espoo) as part of a (Nokia-)sponsored geek tour. And Scoble was not impressed. Because (1) everyone appears to have been texting when he was on the tube (how quaint), (2) the N97 isn’t cooler than the iPhone and (3) Symbian is much clunkier than the iPhone’s OS or Palm’s WebOS, Scoble deduces that Europe has had it.

He reduces this loss of leadership in mobile innovation to handsets or, more specifically, to the coolness factor of handsets (“London’s cool kids are [not] hot and bothered” about the N97). And, with that somewhat tight limitation, he might actually be right. Nokia has been losing ground on the coolness and usability front for quite a while. However, when it comes to technical ability, their devices are still quite hot. Scoble basically uses the iPhone plus the first Android-based (Taiwanese [sic!]) phones to declare that the king is dead.

Hardware is a Commodity
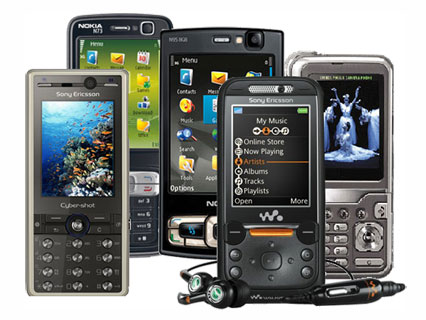
Now, let’s try to differentiate a little. Would you say the US have the lead in computer manufacturing? Well, probably not. IBM’s ThinkPads are Chinese, then there is Sony, Samsung, Toshiba, and there is HP and Dell. There is of course also Apple (“designed in California”). Does it matter at all where the hardware is from? No, not at all, and no one really cares anymore. And why not? Because hardware is basically a commodity, that is in a world where one does not actually see that much of the hardware because the interfaces are software-driven. And these are from Microsoft, etc.

In mobile, this has not been true in the past because their were such vast differences in the available hardware that the usability was severely impaired should you have been using, say, a low-end Motorola device as opposed to a high-end Nokia. This is where the myth of European mobile superiority comes from. And, with Apple, RIM and maybe Palm again, this is firmly in North American hands. There are of course Samsung and LG, the Korean powerhouses who drive their market share up and up. Android devices G1, G2 and Magic are from Taiwanese HTC. However, given how far mobile software and indeed services have come: does it really matter either way today? I say it does not.

Here’s the Innovation: Services

If one wants to see where mobile innovation is happening, one would need to go to South Korea, Japan, Finland (not the Nokia research labs but, say, the public transport system where you can pay via SMS for the past couple of years already), Austria (mass deployment of mobile RFID-payments), South Africa (mobile wallets and very evolved mobile marketing services), Malaysia, the Philippines and even Kenya (mobile money transfers). Certainly not the US though, I’m afraid. They are still the country where “can you hear me now?” campaigns rule.
The iPhone has changed a lot of things of course. However, American Idol arguably did a lot more. It brought, shock, horror, texting to the Americans. SMS being, of course, a service. And why, Mr Scoble, should that be bad? Carriers (other than in the US) have made 25% of their revenues and 50% of their profits over the last 10 years with this unassuming little thing. That’s not too shabby, is it? The iPhone (and Palm’s WebOS) have introduced a new level of ease of use, and one that was long overdue. One that woke Nokia, which had comfortably dominated the space with less and less innovation on the software side, up (and Nokia might be a little slow to open their eyes properly). And one that will improve service levels all over the world.

Where the Big Market is

However, let us also not forget that the best-selling phone of all times is the Nokia 1100. No, it doesn’t do Java. It has a battery life of close to 20 years though and comes with a flashlight installed. Both very handy things to have in rural parts of developing or emerging countries. Nokia is having a fairly comfortable market share in these countries. I am not sure if that is a good thing to rest on though: as these markets, they demand more sophisticated devices. And because the computer penetration is much lower than in Europe, Japan, South Korea and North America, the significance of evolved mobile devices will be even more important. Nokia thought this would carry it through. However, we are seeing now that that might not be so: its smartphone market shares are rapidly decreasing.

Europe is not Europe
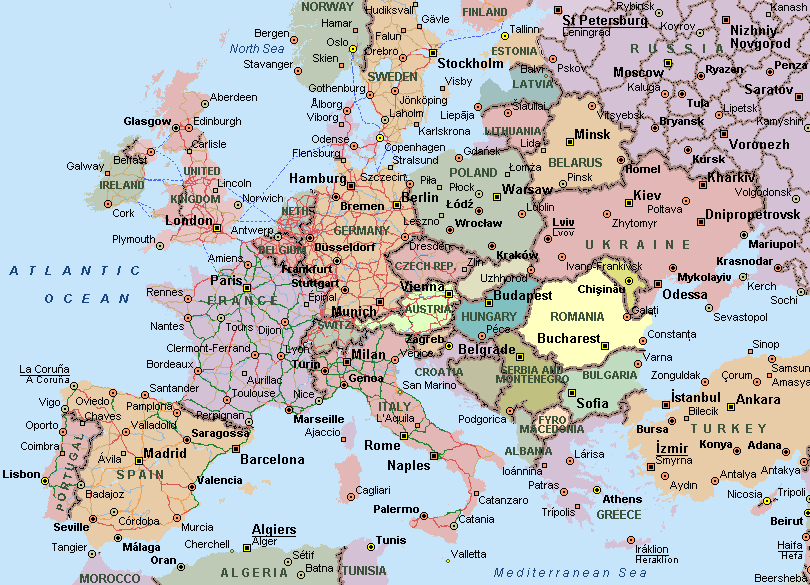
One last word on Europe: distinct to what Mr Scoble appears to have in mind, Europe is not a country, and this is not meant to be sarcastic. Europe is a pile of little countries and in each of them a couple of carriers rule like little kings. It makes for an extremely complex (and, consequently, low-margin) playground to deploy services. The US (as well as some of the huge Asian countries) have the incredible opportunity to deploy applications and services in one language through less than a handful of carriers to hundreds of millions. No such thing in Europe.

And this is why the US should lead in every aspect really: it is an evolved, competitive economy and it enjoys the tremendous upside of being (almost) completely aligned as to the framework: language, currency, carriers, billing systems, legal system, etc. This is the reason why the US has indeed leapfrogged Europe, the continent, when it comes to basic mobile applications: economies of scale are much easier to achieve there.

Software, Services, Interfaces

When one looks at Nokia in its current state as the sole indicator of where European mobile innovation is, one might be disappointed (as I pointed out numerous times, e.g. here). However, when one looks at how concert tickets are being sold via mobile, public transport, parking fees and vending machines all using mobile as a wallet solution, or indeed Obama making his latest speech available via SMS (there are more than 10x as many mobile phones in Africa than PCs according to Tomi Ahonen), then one can and should still be awed. And, no, in spite of its President the US is not (yet) close in this respect.
I hope, however, the US will catch up on this front sooner rather than later, too. Because of the size of the market and the aforementioned advantages, it would unleash incredible opportunities that would bring all of us fantastic new services and applications. And, Mr Scoble, it does not matter if these are 160 characters or polished web pages; it depends on what you want to do with it (as you, being one of the most prolific Twitterati, surely know).

I did not text anymore because I hated the UI and could not stand the clunky interfaces (in spite of T9; I’m too old, I guess). I started again with the iPhone. Why? Because – distinct what some people say – it’s a great interface: it displays the conversation, it looks neat and I have a full keyboard (the touch screen works much better than I feared; and I used a Blackberry for years and years). But that is not a question of the device or the technology, it is solely a question of the software. I would be much happier if I could also use my iPhone (or any other phone) to buy my newspaper (which I can with an RFID-equipped credit card in this country and which I could do in, say, Austria, a country with 2/3 the population of Illinois and a footprint smaller than Maine).

What Scoble misses (or omits in his post) is that the next leap in innovation will be a service-driven one (just as we saw on the Internet: first hardware, then basic apps, now sophisticated services).

Mobile has had the hardware phase, it is going through a “basic” app phase, and some European, African and Asian countries have entered the value-added services phase already, some years and years ago in fact! Compared to the US, they’re leading, by a lot! They’re perhaps just too small for the Robert Scoble to realize they’re there… But, as I said above: this is not about Europe leading the US (apart from the fact that it would appear to being Asia that is truly leading and has been for a while): it is about the evolution of an incredibly powerful communication device that is being unlocked for more and more applications and services; and this is independent from country and nationality!

Along those lines: why, Mr Scoble, should it be a bad thing that Europeans now “must” visit Cupertino and Mountain View. California is nice, isn’t it? Not a bad thing to go visit every now and then at all! We’re living in a large world, Mr Scoble, not only on a single continent, and mobile is a facilitator spurning new ecosystems, not only a device.

Image credit drawing: http://www.aartkom.cz
AdMob on iPhone ad impressions and why Andrew Bud is wrong

Mobile advertising firm AdMob has released some numbers on ad impressions on iPhone vs other smart phones and the result is, well, that Apple is basically a 50kg flyweight boxer competing against Sumo wrestlers 5 times it weight (8% smartphone footprint but more than 40% ad impression share).

Now, very (!) crudely put, this does not mean that it is 8 times as successful on mobile advertising. It does mean however that users are 8 times more likely to use applications where ads are being displayed. Here’s some of their stats:

iPhone Apps (in AdMob’s network):

  • The top iPhone apps had more than one million users in the UK in May 2009
  • 5% of iPhone apps had more than 100,000 active users in May 2009
  • 14% of iPhone apps had between 10,000 – 100,000 active users in May 2009
  • 27% of iPhone apps had between 1,000 – 10,000 active users in May 2009

Mobile web browsing market in May 2009:

UK:

  • 48.7% of ad requests came from Apple handsets (iPhone and iPod Touch)
  • 28.4% of ad requests came from the iPhone
  • 282,493,761 ad requests from users in the UK

US:

  • 45.1% of ad requests came from Apple handsets
  • 25.7% of ad requests came from the iPhone
  • 3,804,373,544 ad requests from users in the US

Global:

  • 31.4% of ad requests came from Apple handsets
  • 18.6% of ad requests came from the iPhone
  • 7,997,946,483 ad requests from users around the world

Interestingly, MEF and MBlox Chairman Andrew Bud (who is being quoted at the end of the article) said that Apple’s app store compared to Nokia’s Ovi Store like a niche boutique to Tesco (or, if you are in the US, Walmart). Is that so? No it is not. And here’s why:

Apple is a boutique with more items on sale than a Tesco megastore. And its (less) customers buy trolleys full of wares. Moreover, their high-spending customers leave the store with a spring in their step and committed to come back the next day.

Nokia is a super-store with gazillion potential (!) customers where 1 in 20 stroll through aisles stocked with not so cool things and most of them walk out without buying anything and, on top of that, feeling fairly downtrodden and frustrated about what was on offer.

So, for the time being, I’d choose the Apple boutique. If that choice changes will depend on whether Nokia will manage to stock their shelves with more compelling wares and improve on their tills (less queuing, more bang for your buck, etc). Oh, and get those cold strip-lights replaced, please!

Top 10 Mobile Phones in June 2009

Here’s our monthly update on the best-selling phones as derived from accessory sales by Swedish company Krusell. They seem to be having a new product line: the iPhone shows up now (and as a “new entry” no less). It is arguably to show the limited value of this table in terms of overall sales.
It is noteworthy that June’s #1 phone (Nokia 6300) is a handset that was introduced to the market more than 2 years ago. Now it is a very solid performer (as my wife will tell you) and has been used as a very good-value phone (£0.00 when bought on a pay-as-you-go) by a lot of carrier. Or is it that the phone is now so shabby it needs to be covered by a plush holster? :p

I thought it is also noteworthy that Nokia’s new flagship the N97 (or any other N-series Nokia) is not featuring at all… It might be early days for the N97 but the others?

Well, make of it what you will, here’s the top 10 list (oh, wait, it’s a top 11 this month; woah):

1. (3) Nokia 6300
2. (-) Apple iphone 3G
3. (-) HTC Touch Diamond 2
4. (2) Nokia 3109
5. (-) Nokia E51
6. (1) Nokia 5800
7. (5) Nokia E71
8. (6) HTC Touch HD
9. (-) HTC Magic
10. (-)HTC Touch Pro2
11. (4) Samsung SGH-i900/i910 Omnia
() = Last month’s position.

AR: the next acronym to watch out for?

AR GameAR stands for Augmented Reality and it is one of the dreams of game developers: merge the virtual and real worlds in a game and explore new horizons. This has been a pretty futuristic feature until recently: shown off at trade shows but never really seeing the (commercial) limelight. And even in the brave new world of the iPhone, it doesn’t fly – yet.
A dozen or so AR game developers have now launched an initiative to make Apple allow them to manipulate live video feeds (which they need to in order to run their games). The respective API is currently missing (developers are not allowed to use private APIs under Apple’s publishing guidelines). They threaten to otherwise go to Android. Hmm…

So far, AR games are few and far between and they haven’t really left the scholarly confines of Georgia Tech and other ivory towers, simply because there is no market for them as yet. Many people place their faith for the next big thing in mobile gaming on AR but because the necessary parameters (video feeds eat lots of bandwidth) have not been met, they cannot really capitalize on their wares. Go here for a good overview of the status quo (featuring the Georgia Tech apps and others).

So, is it there yet? I’d like it to but I doubt it: it is not only Apple but – possibly more importantly – the carriers: what do they have to gain if a few people consume a disproportionately high amount of bandwidth to play their games? Very little under the current costing framework of the industry. Little short-term chances I would therefore say… A pity that!

iPhone App Store once again: how much?

It is early July and we have not been reading analysts’ estimates on how much Apple may or may not make from application downloads through its app store for at least, what, 2 weeks (here’s a piece from a while ago). High time for another round then… This time, the number is “a few hundred million at best”, per quarter that is. And to be perfectly fair, the number was tagged as a guestimate. With another guestimate putting Apple’s iPhone revenue to $1.5 bn, the revenue per iPhone to Apple is thought to be around $600. Compare this to c. $27 in apps revenue per device (total number of apps divided by total number of devices). It’s 5%.
It is, I think rightly, pointed out that Apple uses applications as a lever for its hardware sales (“there’s an app for that”), and it is undeniable that a device gains more value the more you can do with it. So if you have a device that cannot only make phone calls, take photos (and now video), moonlight as a music player and a sat nav, etc but also finds restaurants, taxis, flight times and undertakers (yes, it does!), allows you to play all sorts of games and do other silly or enlightening things, the perceived value of the device increases and – relative to that – the perceived fair price for it decreases, which means that every little app increases the value of the iPhone a tiny bit, which in turn contributes to another little piece of profit to Apple in addition to its revenue share from the app itself (lowered price sensitivity due to higher perceived value arguably should result in higher sales).

Now this is largely known and acknowledged that Apple is – at least to an extent – replicating the iPod/iTunes model (though Apple also happened to provide the first commercially successful “cure” to free music downloads; hence a slightly different proposition here). But is this all bad?

Let’s have a look at the thing from an app provider’s perspective: if we take the above numbers (“a few hundred million” per quarter), the annual total would be, say $1 bn for Apple, which in return means that the app store “ecosystem” would generate c. $3.3 bn p.a. across the value chain (Apple takes 30% revenue share). That’s not too shabby for a device with such a small market share.

Also: iTunes (which is the world’s largest music retailer) took longer than the app store to generate the downloads it does today, and it is still early days, is it not?

Game Aggregators: New World Order

The times they are a-changing. Everyone has realized this by now (or so we should think). The question therefore is not so much will there be change but how will it look like.
Some of the weakest links in the mobile games value chain would be, it appears, the aggregators. Why is that? Because they do have the least defensible position: they do not own IP, they do not hold unique positions, they do not produce anything, they seem to be at the mercy of both of the groups they are partnering with: game developers to continue granting them distribution rights to their games, network operators and other distribution outlets to continue allowing them to use their channels to get to the end users. As if this would not be enough, now has arisen a creature that seemingly does away with all these middle-men anyway. It is called app store. So is it all doom then for games aggregators? There is a report out (too expensive for me to buy) that would seem to suggest as much, or so we are told.

The argument, in short, is that, with an OEM app store the number of distribution channels that any one developer/publisher needs to reach is drastically reduced (there are maybe 10 meaningful handset manufacturers in the market vs 300+ carriers and other distributors). Even the littlest companies have (or should have) the resource to deal with 10 partners; chapter closed.

Really?

The above works with a number of simple but crucial assumptions, and the boldest is this: carriers will happily let OEM take over the content real estate. Will they now? There are ample signs to doubt this. The giants of the space do not appear to be giving up, in the contrary: Vodafone has already announced its own app store – across handset brands (!) – and it is about to tighten its links with both China Mobile and Verizon Wireless (in the latter of which it holds a large stake). So what will all the OEMs (all with their own app store of course) do when carriers accounting for nearly half of the world’s subscribers wave them off? Cave in? You bet!

Anyway, does this change the game for aggregators? I believe it does and here’s why:

Carriers have traditionally struggled (with exceptions) to run an efficient, customer-friendly content offering. We have therefore seen an increasing trend to outsource the “decks” to third parties, which are – what? -, yes, aggregators.

Carriers are unlikely to concede defeat over the content side, not necessarily because they fear losing out on a lot of revenue (given their fairly average performance, SMS, voice, data, etc will outsell content as a source of revenue very, very significantly) but because of the strategic value of content as well as the unpredictability of its future impact: bear in mind that the emotional attachment to beloved brands, i.e. affinity (Transformers, Ice Age, Playboy, Tiger Woods, …), will remain higher than that to a network operator, and please do not take offense if you are working for one. Do not be mistaken: carriers are being trusted but they are not being loved. There is just not as much emotional attachment to a cellular network as there is to a rodent in love with an acorn…
Carriers do not have to give this piece up either (they call the shots on what goes onto a handset: see an example), they are not even losing money (they even gain: every cent earned through content sales is a cent more than carriers get from the iPhone app store sales…).

However, what carriers do have to do is catch up with the state of the art in selling, and that means an app store. However, it can also be a carrier-operated/driven app store.

An app store, too, does not however solve the dilemma of having to manage a huge amount of content in a way to allow the consumer a choice. One must not throw everything onto a big pile and let them pick out what they believe they like; this type of sales does not register too well: it is time-consuming, intransparent, messy, not good. So one needs someone to manage it. In comes the aggregator.

Or does it?

Aggregators that went around collecting content in a bucket only to throw it against the next wall to see what sticks are likely to struggle (or have died already: RIP Telcogames et al). However, aggregators that actually provide content management as a service to operators thrive (not exclusively on games, mind you). All the big guns in the space, Fox Mobile (f/k/a Jamba), Arvato Mobile, Buongiorno and recently Zed (through its acquisition of Player X) run riot in the space and bid hard for every deal that comes up (and lots of them do!) and gobble up the market. More on the classic D2C side, Thumbplay grew tremendously in the US, SendMe Mobile seems to go from strength to strength, and a lot of smaller ones, such as Rayfusion, etc. seem to more just hang in there, too. Why do they? Because the features that make an aggregator excellent – managing a wealth of content well – are the exact features carriers would look for when outsourcing their struggling content units. And because it is an aggregator’s core business model, they are really good at this, which is crucial in a low-margin business: be efficient or die.

Marketing and promotion is another point. We already see aggregation-type businesses become forces on Apple’s app store, such as Chillingo (from my very own town!). They publish well over 100 games and thrive on iPhone developers capitulating before the challenge to get noticed amongst the more than 50,000 apps currently available. Chillingo can provide marketing and promotion and make sure that a developer’s product gets not only live but noticed, too. It is very likely that there will be others in this space very, very soon.
So what seems to change is not the viability of being an aggregator but the aggregator’s service to their customers (the carriers!): whereas it may previously have been sufficient to use the “bucket against the wall” tactic, they now have to become better in providing a subtle selection without too much restriction. People will normally welcome a structured environment with pre-selected choices. Just make it a) easy and b) don’t limit randomly or indeed too much. And now get going! 😉

Disclaimer: I hold an indirect interest in Rayfusion.

iPhone Usage

Here’s a report about an interesting piece of research into the elusive animal that is the iPhone and Android user, or more precisely that animal’s usage of apps (“… there’s an app for that…”).

The researchers from Gravity Tank chose Android (well, the G1) next to the iPhone because Android Market and Apple’s App Store both allow “unlike older smartphones [sic!] easy access to a range of free or low-cost applications”. Now this is what the (mobile) world has become in the last 12 months…

Anyway, the survey finds that the average (!) user has 23.6 applications on his/her phone and uses 6.8 of them every day. 48 percent report shopping for apps more than once a week. About the same number (49 percent) report using apps on their phone for more than 30 minutes a day. Woah, nice!

But it goes on: 32% said they used portable gaming devices less because of their app-enabled phones. This reminds me of one of my predictions on how the iPhone would eat into the handheld gaming market (see here, here, here and here).

And it shows, more importantly maybe, that these owners of the “newer” smartphones use them as true multimedia devices rather than only phones: 31% read newspapers less, 28% use GPS devices less, 28% use MP3 players less (well, they have one of the better ones if they use an iPhone), and 24% are watching less TV. Media going mobile then, finally…

And then – another indication on how far we have gone – the NY Times starts to whine: it notes that “despite Apple’s relentless advertising of its App Store, it seems that the availability of applications is not the primary driver of phone-buying behavior.” Doh. Now, here’s a finding. 74% of the respondents said the device “allowed” them to check their e-mail and calendar, and it allowed them to consolidate multiple devices into a single device whereas “only” 67% cited the availability of new games and applications. Only 67%, huh? Brave new world!

Page 9 of 17

Powered by WordPress & Theme by Anders Norén