Tag: app store Page 8 of 10

The Others: Where Android, Symbian & LiMo are

The title of this post is not meant in any way derogatory but with all the hype about the iPhone it is sometimes easy to forget that we are talking about a niche product that will probably remain a niche product (albeit a powerful and cool one!). In the rest of the world (feature phones aside), a few consortia are fighting for the open-source market, which is – let’s face it – a considerably larger piece than the small premium segment served by Apple.

So, where were we? There is the LiMo Foundation, which is onto establishing a mobile Linux standard. There is the Symbian Foundation and there is Android, a Linux-based OS from the Open Handset Alliance led by Google. One by one then:
LiMo Foundation
LiMo boasts a membership based comprised of the Who’s Who in mobile. Powerhouses from around the world like Vodafone, Orange,
Verizon Wireless, NTT DoCoMo, Telefonica, SFR, TIM and SK Telecom, Samsung, NEC, LG, Panasonic, Huawei, Motorola, and ZTE (and quite a few more) are all in there. LiMo has released an SDK a while ago. Now though, they decided that enough is enough and that the world should know that their OS was actually making headway. In 2009, there will be new handsets based on LiMo’s s
tandards released by Orange, Telefonica, Vodafone, NTT DoCoMo, SK Telecom and Verizon Wireless. Now, that’s a statement. Non-phone devices are in the works, they say…
There are already more than 20 LiMo phones out there (without very many people having realized it). They include such mundane devices like Motorola’s U9, ROKR EM30, ROKR Z6 and ROKR E8 as well as the RAZR2. Panasonic and NEC pboth produced a whole raft of devices for NTT DoCoMo. See here for a list of available phones.
Symbian
Symbian of course is coming from a differen
t mould: having been (co-)owned by Nokia for, like, ever, there are already over 200m devices running on its OS. After going open-source, they are working on consolidating the sister formats S60, UIQ and MOAP(S) now into one. Membership-wise, they’re not doing badly either: they target to having more than 100 members by year-end. Membership with them is only $1,500 p.a. It remains to be seen to what extent they will extend their handset footprint beyond Nokia though. Little has been heard so far…
Android
Both foundations felt compelled to state their cause, also in response to Eric Schmidt’s continued mantra that 2009 will be very, very strong for Android. The Open Handset Alliance had gone off to a well-publicized start with the T-Mobile G1. They recently announced that it had sold 1m devices (regarding which some people pointed out that Apple shipped as many iPhones on the first weekend), and are now gearing up more devices for launch (Vodafone got its hands on the HTC Magic). Samsung, LG, HTC and Sony Ericsson have all announced Android devices this year, and the first Samsung (I7500) has just been officially confirmed.
Multiple Membership
Wait a minute? Samsung? Weren’t they part of the LiMo foundation? Well, yes, and that is part of the problem: a lot of the big players have their fingers in all the pies (and why should they not?). This is favouring Apple since they are a single organization producing hardware and software. It could also be argued that it is favouring Android because Google throws so much marketing and PR behind it. However, maybe not. The big OEMs and the big carriers all work according to their own agenda. And this might very well be a very different one to Eric Schmidt’s: to an OEM, production cost, stability and versatility without impacting standardization are key. To a carrier, a lot will (also) ride on the ability to customize the handset so as to give it a distinct branded feel. Less PR from someone like Google makes it easier to them to focus on their own brand.
So: rock-solid, clean code, transparent and clear SDKs, no hidden hooks will mean that a lot of the feature phones that create the vast majority of handset sales (even if sales of the “classic” J2ME ones had been declining in 2008 when compared to smartphones) will quite possibly see a larger and larger move towards the open platforms. It makes it cheaper to produce and, with Apple having given the world the app store idea, content should flow in sooner or later. They “only” need to keep the standards, well, standard!
The iPhone is of course looming large, and it is the one device that has shown the old school of the telco world how 21-st-century marketing can impact market perception and sales. They have also all realized that this might actually be a very good thing, hence the eager discussions many are purported to be having on getting their hands on the next generation. However, last time I looked, the streets were not full of Porsche Boxsters either. Quite a few Hyundais, Fiats, Peugeots, BMWs, Volvos, well, you get it…

Why an iPhone Deal with Verizon Wireless would be Cool

Today, interesting reports surfaced (or re-surfaced?) according to which Verizon Wireless and Apple are in discussions about bringing the iPhone to the former. However, because Verizon runs on a CDMA network and Apple has only ever supported GSM, commentators reckoned that this deal might be for Verizon’s next-generation LTE network. And this is when one can start dreaming…

To recap: Verizon will be amongst the (if not The) first tier-1 network operators rolling out the next generation of wireless networks under the LTE standard (see here for more on this). Under LTE, unprecedented wireless bandwidth will be available, comparable (or exceeding) what households in Western and Far-Eastern countries have in their homes today. But then you would have it of course wherever you are (well, if the respective technology is installed).
Due to the immense speeds, a lot of people think that the first big change will be on the (computer) broadband side of things: no need for wireline access if the speeds are the same and you can actually wander around and through town and always be with your provider. Simplicity, ease of use, bliss of connected life.

When it comes to mobile handsets (previously known as phones), the iPhone is of course (and despite the heckling by its many critics) arguably the most successful multimedia device known to man (so far). To marry this with these speeds? Ah, what would await us (see here for earlier thoughts). The iPhone (if they can fix the battery life) would be perfectly suited to bring the new lush wireless life to the masses (albeit first to the more affluent ones): rich graphics, innovative inputs and the fairly unique form factor would show the opportunities off rather beautifully and could hence aid to avoid the post-3G hangover where people asked themselves why on earth they should get 3G phones: there was nothing much to do with them (other than being able to make “faster” phone calls…).
The most common uses would arguably be music and apps with the latter being even more successful than the former: it is estimated that iTunes took 6 years to record 6.8 bn downloads; the App Store did 1 bn in only 9 months (or 1.3bn p.a.), which would equal 7.8 bn in 6 years if no further growth would occur. Anyway, with 1.1 bn downloads p.a. not being too shabby either, let’s take both, so what do we get?
On the music side, it would either mean quick and high-quality downloads or, more likely (?), streamed music. The same applies to the VOD and movie segments.
On the apps side, LTE would arguably push the envelope into two directions: (1) high-end, graphically rich games, and (2) ultra-connected social games that seamlessly bridge media platforms. Now: both types had their advent on the iPhone. Speak to any number of high-end games makers, and they will tell you that their life became much easier since the iPhone was there. Look at products like EA’s Scrabble (with full Facebook integration), Playfish‘s games (coming from the other end, i.e. from Facebook to iPhone), etc and you have the foundations laid here, too. With LTE, all this becomes mass-marketable to a much higher extent. And this would be real fun!

iPhone all-time top 20 apps, countdown to 1bn downloads

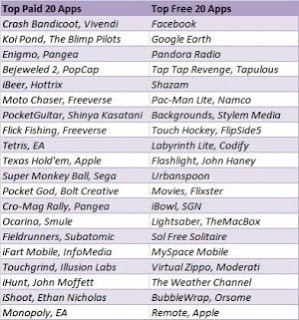
I’ve been raving about it many a time and I still won’t stop but then: Apple does neither. When, waaaay back in January, I looked last, the App Store had raced through 500 million downloads and I calculated this to equate 4,000 per minute. Well, that’s history: We’re now through a 948 million total (count taken on 13 April, 11.23pm UK time from Apple’s site [check the little clock]) and look at 6,000 downloads per minute (or 100 every second of every minute of every hour of every day!) or so some learned friends have summed it up to.
Apple also revealed a list of the top 20 all-time top downloads, both paid and free, which (courtesy of MoCoNews) is this:
So here’s the good stuff for my gaming friends: 14 out of the top 20 paid apps are games! Yes, baby! 6 out of the top 20 free ones are, too. Way to go! I haven’t looked at the pricing for the above paid apps but MoCoNews did: ¢99 is the prevailing price-point at the moment but $4.99 seems to be the price point of choice for “premium” games.

Microsoft App Store Better than Apple!?

Microsoft has a central market place for Windows Mobile applications in the making. It is the latest (and maybe the last) of the big smartphone platform makers to come forth with such a model. And – with a probably already somewhat reflexive jab to its Cupertino nemesis (yes, Mr Gates’ children are not allowed iPods), it vowed to be more open to outside software developers.

Apple is indeed not known for the most proactive approach to external partners but it does have a bit of a name for being a “good company”. Microsoft on the other hand is, rightly or wrongly, not really known for this. It would be a nice move. Other than that – also somewhat familiar – Microsoft’s store is said to be closely following Apple’s lead, even the revenue share (70% to developers) is apparently the same. The only difference would then be the openness. This is presumably being highlighted following a couple of incidents where developers complained that Apple had not accepted their applications without giving them a good reason. If Microsoft were to make this bit better, it would constitute a significant improvement as it would save developers from spending money on application development only to see them canned.
The rationale for Microsoft’s move is utterly simple: a) there are more Windows Mobile apps out than iPhone ones (20,000 they say). It is just a wee bit more difficult to find them, b) everyone else (RIM, Nokia, Android, hell, even Palm) does it, and c) Apple is insanely successful with it.

The big question that remains is if the integration of the store will be as seamless as Apple’s. The key differentiator is that Apple has managed (which no other OEM has so far) to impose a strictly regulated environment from end to end: its program has an easy entry (a few paragraphs with a click-through agreement), a fairly well-controlled development environment and a unified output (the store), which is the same anywhere in the world. Even the biggest OEMs have struggled to impose anything even resembling this kind of control. Windows Mobile runs on a number of the tier-2 players (HTC) that have done the opposite to Apple: HTC willingly gives away its branding in favour of a carrier brand and is content to provide the hardware. Since it can be expected that at least the larger carriers will be keen to run app stores of their own, Microsoft will struggle more than Apple (which was a highly anticipated new market entrant with a tremendous brand message) to assert this type of dominance over carrier specs. The recent rumours of lower Windows Mobile output won’t necessarily help either.
I would welcome a success from Microsoft; let Apple not grow overly content…

Smartphone Market Shares & Growth

World market leader Nokia had a bruising 2008, at least in the smartphone field. According to a study, the Finns’ market share in this segment dropped by 10% to a – well – still fairly respectable 40.8% in Q4/2008 (as compared to 50.9% a for the quarter in the previous year). Painful!

The big winners were RIM (growth of 84.9% year-on-year), Apple (111.6%) and Samsung (138%) although the latter grew from a fairly low share (1.8%). HTC was up 20% but its carrier-branded handsets (T-Mobile G1, etc) were not listed under its own tab but under “others”, so there might actually have been more (probable when considering that the company’s profits rose sharply in Q4/2008 on G1 sales).
Apple, interestingly, is said to have suffered a fall of sales during Q4/2008 with growth in that quarter driven by the Blackberry Storm, T-Mobile G1 and strong Samsung sales. On the OS side, Windows Mobile made headway, mainly via the successful HTC Touch line and the Samsung Omnia.
Overall smartphone sales in Q4/2008 were 38m and 140m for the whole year. This seems to tie in roughly with the numbers I discussed earlier this month.
The changes are of interest to the content industry, too. Smartphones make for a disproportionate amount of content consumption, and smartphones also lead the way for the new app stores that are breaking through everywhere after Apple showed its competitors just how much consumers are craving content. RIM is out of the blocks, as is Android. Nokia announced its Ovi Store and runs similar programmes with N-Gage, NCD and Comes with Music already and Windows Mobile has just announced the shop it will launch itself. Remains to be seen where Palm will go with its Pre and WebOS: it only had 0.9% of the market (some faithful Treo users!) and hence lots of catching up to do. And what about the newly coined JavaFX?
Here are the charts (courtesy of Gartner via Cellular News) for 1) Q4 2008 by vendor, 2) all of 2008 by vendor, 3) Q4/2008: by operating system and 4) all of 2008 by OS:

Worldwide: Smartphone Sales to End Users by Vendor

(Thousands of Units)

Company 4Q08 Sales Market Share4Q08 (%) 4Q07 Sales Market Share4Q07 (%) 4Q07-4Q08 Growth (%)
Nokia 15,561.7 40.8% 18,703.3 50.9% -16.8%
RIM 7,442.6 19.5% 4,024.7 10.9% 84.9%
Apple 4,079.4 10.7% 1,928.3 5.2% 111.6%
HTC 1,631.7 4.3% 1,361.1 3.7% 19.9%
Samsung 1,598.2 4.2% 671.5 1.8% 138.0%
Others 7,829.7 20.5% 10,077.3 27.4% -22.3%
Total 38,143.3 100% 36,766.1 100% 3.7%

Worldwide: Smartphone Sales to End Users by Vendor, 2008

Company 2008 Sales Market Share 2008 2007 Sales Market Share 2007 Growth
2007-2008
Nokia 60,920.5 43.7% 60,465.0 49.4% 0.8%
RIM 23,149.0 16.6% 11,767.7 9.6% 96.7%
Apple 11,417.5 8.2% 3,302.6 2.7% 245.7%
HTC 5,895.4 4.2% 3,718.5 3.0% 58.5%
Sharp 5,234.2 3.8% 6,885.3 5.6% -24.0%
Others 32,671.4 23.5% 36,176.6 29.6% -9.7%
Total 139,287.9 100% 122,315.6 100% 13.9%

Worldwide: Smartphone Sales to End Users by Operating System, 4Q08

Company 4Q08 Sales Market Share 4Q08 4Q07 Sales Market Share 4Q07 Growth
4Q07-4Q08
Symbian 17,949.1 47.1% 22,902.5 62.3% -21.6%
RIM 7,442.6 19.5% 4,024.7 10.9% 84.9%
Windows Mobile 4,713.9 12.4% 4,374.4 11.9% 7.8%
Mac OS X 4,079.4 10.7% 1,928.3 5.2% 111.6%
Linux 3,194.9 8.4% 2,675.9 7.3% 19.4%
Palm OS 326.5 0.9% 449.1 1.2% -27.3%
Other OSs 436.9 1.1% 411.3 1.1% 6.2%
Total 38,143.3 100% 36,766.1 100% 3.7%

Note: The “Other OSs” category includes sales of Sharp Sidekick devices based on the Danger platform.

Worldwide: Smartphone Sales to End Users by Operating System, 2008

Company 2008 Sales Market Share 2008 2007 Sales Market Share 2007 Growth
2007-2008
Symbian 72,933.5 52.4% 77,684.0 63.5% -6.1%
RIM 23,149.0 16.6% 11,767.7 9.6% 96.7%
Windows Mobile 16,498.1 11.8% 14,698.0 12.0% 12.2%
Mac OS X 11,417.5 8.2% 3,302.6 2.7% 245.7%
Linux 11,262.9 8.1% 11,756.7 9.6% -4.2%
Palm OS 2,507.2 1.8% 1,762.7 1.4% 42.2%
Other OSs 1,519.7 1.1% 1,344.0 1.1% 13.1%
Total 139,287.9 100% 122,315.6 100% 13.9%

Note: The “Other OSs” category includes sales of Sharp Sidekick devices based on the Danger platform.

Blackberry App World Gets a Pal

Blackberry Maker RIM launched a holding site ahead of the launch of its Blackberry App World (the equivalent to Apple’s AppStore), and it had a little surprise in hand: billing appears to be handled via PayPal (the fine print does not need translation: “to be able to purchase applications from BlackBerry App World, a PayPal Account is required”).

This is two things: a) a massive win for PayPal and b) and nice move from Blackberry because PayPal is one of the simpler mechanisms, which will feel, like, so totally easy to many users (everyone who has tried to download applications and pay via credit card on their Blackberry will know how onerous it is/was).
I am thrilled to see this coming on. Apple has had 9 months free reign, and it’s about time that its competitors step up and bring commercial stores out. Blackberry will be fantastically suited as – due to e-mail having been its central USP – its users traditionally are on data plans anyway, and will therefore be less reluctant to dig in properly.

Top 10 Smartphone Games & Apps 2008

Smartphone content vendor Handango releases a smartphone “yardstick” every year containing the top sellers from data in their store. Anecdotally, smartphone apps are more often sold via direct stores (rather than operator decks) than “normal” (not smart?) phones, owing of course to the better connectability (not necessarily connectivity) of high-end phones: input mechanisms (Querty, touchscreen, better D-pads), almost always 3G phones, etc make for a more satisfying user experience (try inputting a web URL via a basic phone keypad… painful!).


They had just under 10,000 apps on offer (spread across Blackberry, Windows Mobile [pro and standard], Palm, Symbian and Android). The average price point was a rather healthy $19, and users downloaded 1.12 apps on average.

Handango also says that games rose as part of overall “top category” sales (whatever that is) from 11% in 2007 to 19% in 2008. This is encouraging. Even so, there is no game amongst their overall best-sellers for 2008. Here’s the list (price points at the end of each line):
1. Spb Mobile Shell 2.1.4 (today screen plug-in) – $29.95
2. MobiTV (streaming television) – $9.99/month
3. Ringtone Megaplex (ringtones) – $19.95
4. Spb Backup 2.0.1 (file backup) – $24.95
5. Spb Pocket Plus 4.0.2 (today screen plug-in) – $29.95
6. Pocket Informant 8 (today screen plug-in) – $29.95
7. Spb Phone Suite 1.3 (phone features) – $19.95
8. VoiceControl (voice command) – $6.00
9. Colour Your Trackball (trackball customizer) – $4.95
10. eWallet (Professional Edition) (PIM manager) – $29.95

The top 10 games across platforms for smartphones is this:

1. Spb Brain Evolution 1.2 (puzzle game)
2. Aces Texas Hold’em® – No Limit (card game)
3. TETRIS (puzzle game)
4. Guitar Hero 3 Mobile (music game)
5. Bejeweled (puzzle game)
6. Aces Solitaire Pack (card game)
7. The Sims 2 (strategy game)
8. Jewelrumble 2 (puzzle game)9. Sudoku Puzzle Pack (puzzle game)
10. Solitaire Buddy Gold (card game)

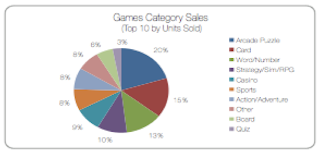
And here’s a chart of the game categories – and, no, still no first-person-shooters in the top 10:

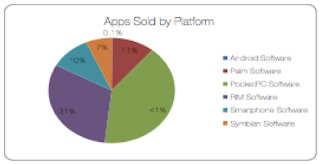
A noteworthy bit in the “Yardstick” is that Android already makes up for 10% of their sales (or so would the below graphic tell us). 

From this, it also occurs that Handango does not consider the iPhone to being very smart. Hm… Well, it’s probably that everyone who buys content on that one will buy not buy it from Handango but through the AppStore. OK then…

Page 8 of 10

Powered by WordPress & Theme by Anders Norén