
 A lot is being said about mobile marketing, mobile advertising, capturing “consumer’s” imagination (if not only their eyeballs). And everyone says: “yes, I get that, social, mobile, always-on, always with them, cool!” Online ad spend outstrips TV already (at least in the UK), and mobile is arguably the next big thing; it is so much cooler, too: personal, accessible, always-on!).
So how do you execute? Banner ads? Text ads? Virals? “Ah, yes, virals are cool, I heard about them!”
There’s a busload full of mobile advertising networks out there, blind, premium blind, premium (check here for a great overview). And what do they do? Well, banner ads, text ads, the usual. Does it work? Anecdotally, sort of… Most developers and publishers I know that engage in this sort of activity make their money in two ways: either they are being commissioned by an advertiser to do it (good because you’re being paid!) or they use it as complementary (sic!) revenue; on a stand-alone basis, it would not feed them.
Why is the conversion not soaring? After all, mobile allows for unprecedented targeting (IF you do it. See here how not to do it): users have their phones always with them, it is always on, you can fall back on historical behaviours, etc, etc.
I would posit that it is because most advertisers still think of it in terms of consumers: beings that sit on the other (sic!) end of the message and who consume whatever I, advertiser, want to tell them. It is not, alas, true engagement, and this is where arguably the future lies.
 So how do you engage? Many options. A good one is by being sincere (Zappos, the online shoe retailer that was recently acquired by Amazon, is a great example). Another one is by engaging rather than preaching. Not so easily done with banners. Easier done with something more interactive. Such as – an example – games and apps. On Apple’s app store, there are some great successes for this type of thing: German car manufacturers seem to be good at this! Audi did one, German developer Fishlabs did a couple of games for Volkswagen, Artificial Life for BMW, and then there is Waterslide Extreme, which is basically a Barclaycard ad (and badly executed: they could so easily have accommodated the RFID function, which the original cinema and TV ad is meant to promote; alas, they ignored it!) which despite its shortfalls was incredibly successful. But these are exceptions to what I think might well become the rule. On the app side, there are e.g. Pizza Hut and Gap that were recently featured (for free!) in Apple ads. Wow!
It seems obvious when you think about it: games truly engage (users – not consumers! – interact with them actively) and they can do so in a much more subtle manner (less invasive). At the same time, the user (not: consumer) spends a lot more time with the brand than with a banner ad.
It is, alas, a space of unknown dangers and unprecedented adventure: never-before seen creatures (scil. formats) and strange folks (scil. developers) roam weird landscapes (scil. mobile platforms). This is how brands and their agencies often experience mobile. They "get" it, don’t get me wrong but they are still fairly unfamiliar with it. And because the big pots of gold sit with the brands and they don’t want to risk cutting access, they’ll rather (and rather too often) stick with what they perceive as the trusted old paths. It’s not so good then that the freshest fruit grows on the trees in this new land and no longer in the wastelands of banner ads…
Watch this space then. It will only be a question of time (I hope) before we’ll be seeing a new wave of non-intrusive, interactive, fun brand engagement. And games and apps will lead the way!
 After much huffing and puffing, Vodafone
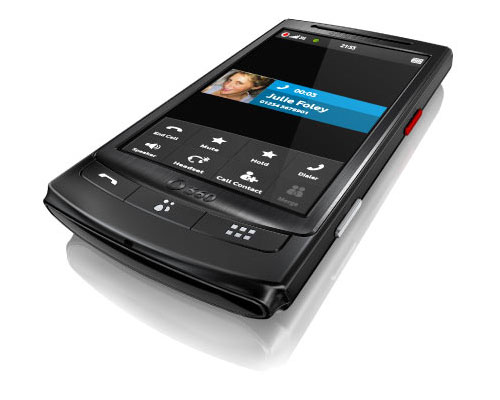 It has an address book with nodes into Facebook, IM (Windows and Google) and will “soon” also cover Twitter, Hyves and StudiVZ (the German Facebook clone). Two tailor-made (!) handsets that use a proprietary (!) interface based on LiMo’s release 2 mobile Linux OS. Users can create groups across different networks (which is very neat!), an app store with 1,000 apps at launch (no word so far what this comprises) and syncing with your computer.
 In the last two days, two forecasts informed us about the value of the mobile app market in – convenient as ever – the distant future that is 2013. US analyst firm
 If we estimate a 20% growth year-on-year for smartphones (vs. 5% for the overall phone market, which seems to be loosely in line with the general dynamic), then we would end up with something like 900m smartphones by 2013. Yankee Group predicts that smartphones in the US will quadruple by then (from 40m to 160m) and does not seem to be very far off. Wireless Expertise thinks the global number will be 1.6bn, which again, might not be that far off.
 Now, I am not predicting total doom and gloom, in the contrary. I do think that Apple’s wake-up call has brought a much-needed new wave of innovation and I also believe that this will be successfully incorporated by some carriers and OEMs. But by all of them? Not very likely.
 After many rumours and ominous statements that it was “reviewing its activities” Namco Bandai
 What is worrying is that this cements the oligopoly of games distribution in all major markets. EA Mobile, Gameloft occupy the top 2 slots very comfortably with Glu an equally comfortable but distant third. I-Play, Digital Chocolate, Real and Connect 2 Media are fighting for place and Xendex, Handy Games and a few others seek (and sometimes find) niches to prosper. THQ Wireless, Vivendi Games Mobile have departed. Player X found a new home under the mighty wings of Zed. And then? If the above companies all manage to maintain a healthy business, this might be enough; there are silverback gorillas in every market segment. If not though, this might become a
 It might of course only be a brief interregnum on the way to an app store world.
 The labels are fairly happy,
 The much-discussed freemium model it is then: get them hooked on the free desktop app and convert them to paying users on mobile. It has long been known that users are more likely to pay if stuff is portable (I can still recall the disbelief of music executives when they realized that people would pay more for a monophonic ringtone than for a full-blown music track). And whilst now the link between (free) basic service on the desktop and (premium) mobile service is new, the principle is old and proven: and it is simply added value (plus the little things like being used to paying on mobile and having convenient existing billing models in place). If the user perception is that they are getting value for money, they are willing to pay. And if it is for such a fairly special thing such as music (don’t we all love and nurture our very own musical mix tastes?), the step is even easier to make.
 Samsung’s new app store (no one can do without one these days!) will be operated by Handmark and is set to go live on 14 September (2009, that is),